Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
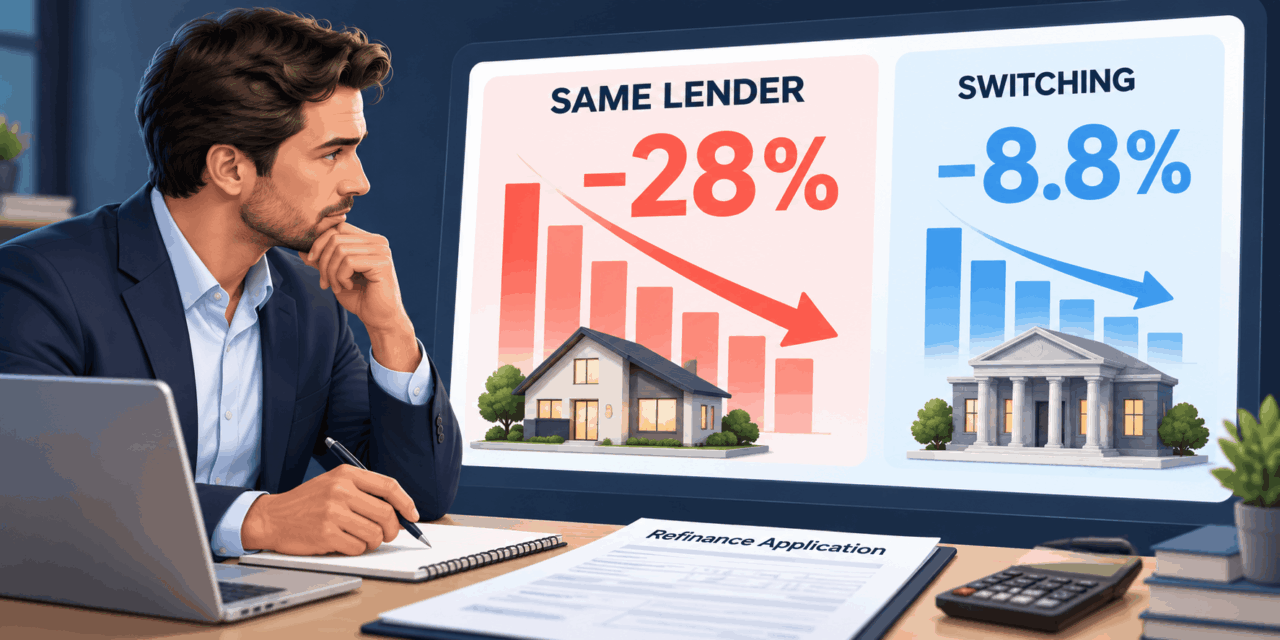
This audio version covers: Same-Lender Refinancing Fell 28% — More Than Three Times the 8.8% Fall in Switching. The Steepest Drop in the Release Was the Easier Option
The Broker Times · Data Snapshot
Where the Refinance Market Actually Went in September
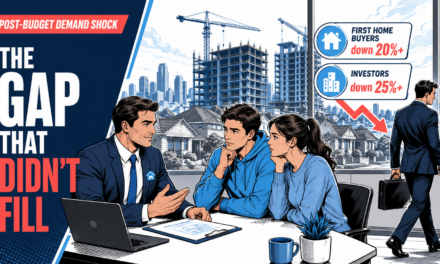
Equifax’s Consumer Market Pulse for September 2026 shows the two halves of refinancing moving at very different speeds — and only one cohort still growing.
The gap at the centre of the data
Year-on-year change in refinance demand, September 2026
−28%
Same-lender refinancing
The steepest fall of any segment in the release. NSW fell 31.3%.
−8.8%
Switching to another lender
Tasmania was the only state to grow, up 1.5%.
The point: both halves of refinancing fell, but the internal half fell more than three times as far. Of the borrowers still refinancing, a larger share are leaving their lender than a year ago.
One month earlier, the gap was different
Year-on-year change, August 2026 vs September 2026
Bars are scaled to the largest value shown and are indicative only. August figures as reported by Banking Day, 16 September 2026; September figures as reported by MPA and Australian Broker.
Who is still switching
Year-on-year change in lender switching, September 2026 — the three age cohorts reported
The wider September release
Year-on-year change in demand, September 2026
Falling
- Overall mortgage demand −19.2% — a sixth consecutive monthly decline
- First home buyer applications −22.1%
- Investors (two or more mortgages) −18%
- 18–25 year olds −25%; 26–35 year olds −22.5%
By state — overall demand
- NSW −21.2%
- ACT −21%
- Queensland −19.2%
- Victoria and South Australia −17.9%
- Western Australia −16.6%
What a broker can do with it this week
A three-step review of the existing book
Segment by capacity, not by rateIdentify which clients would clear a full assessment today, and which would not. The answer decides whether the conversation is a switch or a retention play.
Look at the over-55s firstThey are the only switching cohorts the September data shows growing. Lower LVRs and longer-held equity are the likely reason.
Record the comparison either wayIf a client stays put, the file should show what was considered and why staying was the recommendation.
The takeaway
Internal refinancing falling faster than external switching does not mean clients are happy where they are. On Equifax’s own reading, strict serviceability assessments are holding borrowers in place. The broker’s job in that market is to know which clients are genuinely stuck and which have simply stopped asking — and to have the file show the difference.
Sources: Equifax Consumer Market Pulse, September 2026, as reported by MPA (13 October 2026), Australian Broker (14 October 2026), The Adviser (15 October 2026) and Smart Property Investment (14 October 2026); August 2026 comparison figures as reported by Banking Day, 16 September 2026. Figures are as published by those sources and are not independently verified by The Broker Times.
News · Market Data
Same-Lender Refinancing Fell 28% — More Than Three Times the 8.8% Fall in Switching
Equifax’s September figures show both halves of the refinance market shrinking, but the easier half shrinking fastest. Of the age cohorts reported, only the over-55s were still switching in greater numbers.
Key takeaways
- Equifax’s September 2026 Consumer Market Pulse records same-lender refinancing down 28% year-on-year, against 8.8% for switching to a different lender.
- Overall mortgage demand fell 19.2%, a sixth consecutive monthly decline, with first home buyer applications down 22.1% and investors down 18%.
- Equifax attributes weak switching to strict serviceability assessments holding borrowers in place. That explanation accounts for soft external activity but does not, on its own, explain why the same-lender channel fell further.
- APRA’s APG 223 expects a new serviceability assessment whenever there are material changes to loan conditions — which can bring some same-lender restructures within the same test as a full switch.
- Of the age cohorts reported, lender switching grew among the 56–60s (3.2%) and over-60s (2.3%), while 26 to 35 year olds fell 14.2%. Figures for other cohorts were not reported.
In this article
The two numbers
Two figures in Equifax’s September data describe the same refinance market and move at very different speeds. Refinancing with a different lender fell 8.8% year-on-year. Refinancing with the same lender fell 28%.
Both are declines, so it would be easy to file them together as more evidence of a slow market. That would waste them. The second number is more than three times the first, and on the reporting of the release it is the steepest fall of any segment Equifax measured. The gap between those two numbers is more useful to a broker than either number alone, because it says something specific about where the remaining work in an existing client book actually sits.
It also runs against the intuition. Refinancing with the existing lender is normally the lower-friction path: no discharge, no new lender’s credit assessment from scratch, often no revaluation. When conditions tighten, the easier path is the one you would expect to hold up better. In September it did the opposite.
What else the September release says
The figures come from Equifax’s Consumer Market Pulse for the September 2026 reference period, reported across the trade press in the week to 15 October. Overall mortgage demand fell 19.2% year-on-year — a sixth consecutive monthly decline, and on MPA’s and Australian Broker’s reporting the weakest reading since October 2022. August had been down 14.1%.
| Segment | Change |
|---|---|
| Overall mortgage demand | −19.2% |
| Refinancing — same lender | −28% |
| Refinancing — different lender | −8.8% |
| First home buyer applications | −22.1% |
| Investors (two or more mortgages) | −18% |
| 18–25 year olds | −25% |
| 26–35 year olds | −22.5% |
The state picture is uniformly negative on overall demand: NSW down 21.2%, the ACT down 21%, Queensland down 19.2%, Victoria and South Australia down 17.9% each and Western Australia down 16.6%. Within the switching figure, MPA reported Tasmania as the only state to grow, up 1.5%, with NSW the weakest. Within the same-lender figure, NSW fell 31.3%.
First home buyers recorded the largest annual decline in that segment since December 2022, at 22.1%, while the average first home buyer loan sat at a record $743,000 — $634,000 for 18 to 25 year olds and $736,000 for 26 to 35 year olds. Investor demand, measured as borrowers with two or more mortgages, fell 18% after falls of 11.4% in August and 15.1% in July.
“Australian households are taking a decisive step back.”
Kevin James, chief solution officer, Equifax, as quoted in MPA and Smart Property Investment
One figure worth not misreading. The same release records credit card demand up 10%, including a sharp rise among Australians aged 56 and over, which Equifax linked largely to card switching ahead of the interchange fee cap that took effect on 1 October. That is unsecured credit behaviour. It is not a mortgage signal, and it should not be read into a retention conversation.
Why the gap is the interesting part
Equifax’s own explanation for soft refinancing is serviceability. On MPA’s reporting, James said that in the current climate strict regulatory serviceability assessments appear to be holding borrowers in place; The Adviser reported him describing those assessments as effectively locking borrowers into their current arrangements.
That explanation does real work for the external number. A borrower who cannot clear a new lender’s assessment does not switch, and the 8.8% fall in switching is consistent with that.
But follow the logic one step further and a question opens up. If borrowers are being held in place with their current lender, the same-lender channel is where you would expect that displaced activity to surface — as repricing requests, product switches and restructures. Instead that channel fell 28%, and it has been the weaker of the two for at least two consecutive readings. Banking Day reported the year-to-August figures as same-lender down 23% against external down just 0.8%.
Being locked in place explains why borrowers are not leaving. It does not explain why they have also stopped asking their own lender.
Equifax has not published an explanation for that second part, and nor has anyone else, so what follows is interpretation rather than reported fact. Three possibilities are worth a broker’s attention, and they point to different responses.
The measurement explanation. Demand indices of this kind are built on credit application and enquiry activity. Where a lender reprices a loan proactively through a retention desk, there may be no new application recorded at all. A fall in measured same-lender demand is therefore not necessarily a fall in same-lender repricing. If lenders are being more forward about discounting to hold a book in a shrinking market, measured internal demand would drop even as actual repricing held up.
The assessment explanation. Not every same-lender change is a light-touch exercise. APRA’s prudential practice guide for residential mortgage lending expects a new serviceability assessment whenever there are material changes to loan conditions. Where that applies, the easy internal path is not easy at all — it is the same test the borrower would face elsewhere, which would push internal and external activity down together.
The base effect. Year-on-year comparisons are only as flattering as the year they are measured against. A period of heavy repricing activity in the comparison window would depress the current reading without anything new happening at all.
A broker cannot resolve which of these dominates from published data. What a broker can do is notice that all three point the same way operationally: the client is less likely to start the conversation than they were a year ago.
What APRA’s framework actually says
Because serviceability is doing so much of the explanatory work here, it is worth being precise about what the framework actually requires, rather than what it is often described as requiring.
APRA’s Prudential Practice Guide APG 223 Residential Mortgage Lending, in the version currently published and dated 19 June 2025, states that authorised deposit-taking institutions must apply a buffer over a loan’s interest rate of “at least 3.0 per cent, unless determined otherwise by APRA”. The buffer applies to the rate the borrower will actually pay and excludes introductory or honeymoon rates.
The same guide addresses changed loan conditions directly. APRA expects an ADI to undertake a new serviceability assessment “whenever there are material changes” to loan conditions. The examples it gives include switching from principal and interest to interest-only, extending an interest-only period, switching between fixed and floating rates, and extending the loan term. A new assessment is expected even where immediate repayments fall, if total lifetime repayments increase. That is the mechanism behind the assessment explanation above, and it is why a same-lender restructure is not automatically the soft option a client may assume it is.
APG 223 also defines the exception route. An override, in the guide’s words, “occurs when a residential mortgage loan is approved outside an ADI’s loan serviceability criteria”. Overrides are expected to be captured, subject to risk limits and a defined approval process, and reported regularly.
APRA set out its expectations on the scale of that route in a letter to all ADIs dated 9 June 2023, signed by Chair John Lonsdale. The letter states that banks can use exceptions to policy “if these are managed prudently and limited”, notes that serviceability exceptions have historically made up roughly 2 to 3 per cent of banks’ total housing lending, and says that “prudent banks would have acceptable reasons and clear justifications for loans written outside policy”. Banks reporting large volumes, it says, will be subject to heightened supervisory attention.
Read that carefully, and read its limits. APG 223 is a prudential practice guide directed at ADIs. It is not a broker obligation, and an exceptions process is not a consumer entitlement or something a broker can invoke. Whether any individual file fits a lender’s exception criteria is a matter for that lender’s credit team, on that lender’s policy, within that lender’s own limits.
Non-ADI lenders are not subject to APRA’s prudential framework in the same way and set their own serviceability settings, which is why buffers differ across a panel. None of this displaces a broker’s obligations under the National Consumer Credit Protection Act 2009, including the best interests duty, or ASIC’s guidance on it. Confirm how your own process meets those obligations with your licensee or aggregator compliance team rather than relying on a general description of them.
The practical point for a broker is narrower than it first appears, and more useful. A client who “cannot refinance” has usually been told that by one lender, on one policy, at one point in time. The buffer is a floor on the assessment, not a uniform outcome across a panel, and the assessment can turn on things that change — a completed probation period, a cleared liability, a corrected living expense figure, a different lender’s treatment of the same income.
Where the remaining capacity sits
The age breakdown in the September data is the clearest practical signal in the release. On the figures reported by Australian Broker and The Adviser, the cohorts reported for lender switching were these three: up 3.2% among 56 to 60 year olds, up 2.3% among the over-60s, and down 14.2% among 26 to 35 year olds. Figures for the remaining cohorts were not reported.
No one has published the reason, but the profile is suggestive. Borrowers in their late fifties and sixties are more likely to hold lower loan-to-value ratios, longer-held equity and smaller loan balances relative to income — the characteristics most likely to clear a full assessment with a 3 per cent buffer applied.
That is an opportunity, with a caveat attached. Older borrowers bring considerations that younger ones do not: loan terms extending towards or past retirement, exit strategy, and the lender’s own approach to assessing both. Those are matters lenders assess specifically and that a broker has to document. The one cohort the data shows growing is also the cohort that carries the most evidencing with it. It is a genuine segment, not a shortcut.
What this changes on your desk
A 28% fall in same-lender activity, whatever its cause, has one unambiguous implication: materially fewer clients are initiating the conversation than a year ago. Whether that is because they have been declined, because they assume they will be, because their lender quietly repriced them, or because they have simply stopped thinking about it, the practical effect on a brokerage is the same. The flow of inbound review requests that a book generates on its own has thinned.
That makes the scheduled annual review the mechanism that surfaces the difference, rather than a courtesy call. It is where a broker establishes which clients genuinely cannot move, which could move but have not asked, and which have already been repriced without being told what else was available.
It also matters that the recommendation to stay put is still a recommendation. A file that shows a client was reviewed, options were considered at their current borrowing capacity, and staying was the better outcome is a different file from one with a year of silence on it.
A four-step review of the retention book
What to review this week
- List the next 90 days, not the whole book. Clients rolling off a fixed rate, hitting an anniversary, or coming to the end of an interest-only period inside the next quarter. That is a workable list, and it is where a conversation has a reason to exist.
- Pre-screen capacity before you promise anything. Run the indicative assessment first, across more than one lender’s settings. In a market where switching fell 8.8% and the stated cause is serviceability, the capacity answer determines whether this is a switching conversation or a retention one — and it is better established before the client is told what might be possible.
- Separate “cannot move” from “has not asked”. These need different conversations. The first is about what would need to change, and by when, for the position to improve. The second is about what is available now. Treating them the same is how a viable file gets written off and an unviable one gets raised hopes.
- Record the outcome either way. What was compared, at what borrowing level, and why the recommendation was what it was — including where the recommendation was to do nothing. Confirm the form that record should take with your licensee or aggregator compliance team.
What to watch next
- The October reading. The September data largely predates the full effect of the cash rate increase to 4.60 per cent on 29 September 2026. Whether the same-lender channel keeps falling once that decision works through enquiry is the next useful datapoint.
- Whether the over-55 growth holds. Growth of 3.2% and 2.3% is a thin margin. If it persists it is a segment worth building around; if it reverses it was a timing artefact.
- The gap itself. If same-lender and external refinancing converge, the measurement explanation looks weaker. If the gap widens, proactive lender retention becomes the more likely driver — and that is a direct competitive issue for the broker channel.
- Any movement on the buffer. The 3 per cent minimum is expressed in APG 223 as applying unless APRA determines otherwise, which is the mechanism by which it would change.
The bottom line
The headline from Equifax’s September release is a 19.2% fall in mortgage demand, and that number will be quoted widely. The more useful number for a broker is the 28% fall in same-lender refinancing, because it is both the steepest in the release and the one that contradicts what you would expect in a market where borrowers are reportedly stuck.
Whatever is driving it, the operational consequence is settled: clients are not starting the conversation. In a shrinking market the brokerages that hold their volume will be the ones that already know which clients in their book can move, which cannot, and what would have to change for the second group to join the first — and that have the file to show for it.
Frequently asked
Does a 28% fall mean same-lender repricing has stopped?
Not necessarily. The index is built on application and enquiry activity. Where a lender reprices a loan proactively through a retention desk without a new application, that activity may not be captured. A fall in measured internal demand is not the same as a fall in internal repricing, and Equifax has not published a breakdown that would separate the two.
Is the 3 per cent buffer a legal requirement a client can be exempted from?
It is a prudential expectation set out in APRA’s practice guide APG 223 and directed at authorised deposit-taking institutions, which states that ADIs must apply a buffer of at least 3.0 per cent unless APRA determines otherwise. APG 223 also contemplates loans approved outside an ADI’s serviceability criteria, which it calls overrides, subject to risk limits and a defined approval process. That is a matter internal to each lender, not something a client or a broker can invoke. Non-ADI lenders are not subject to the framework in the same way. Confirm the position with your licensee.
Why would a same-lender restructure trigger a full assessment?
APG 223 states that APRA expects a new serviceability assessment whenever there are material changes to loan conditions. The examples given include switching from principal and interest to interest-only, extending an interest-only period, switching between fixed and floating rates, and extending the loan term — and a new assessment is expected even where immediate repayments fall, if total lifetime repayments increase. How any individual lender applies that is a matter for its own policy.
Should the over-55 switching growth change how I prospect?
It identifies where capacity still exists among the cohorts reported, which is useful for prioritising a review list. It is not a licence to generalise: those cohorts grew 3.2% and 2.3%, which is modest, and lending to borrowers approaching retirement carries its own assessment and documentation requirements around loan term and exit strategy. Treat it as a segment to look at first, not a segment to assume will convert.
Sources
- Equifax Consumer Market Pulse, September 2026 reference period, as reported by MPA, “Mortgage demand slump deepens”, 13 October 2026; Australian Broker, “Mortgage demand falls 19.2% as first-home buyers pull back”, 14 October 2026; Smart Property Investment, 14 October 2026; and The Adviser, “Mortgage demand collapses as refinancing retreat gathers pace”, 15 October 2026.
- August 2026 comparison figures (same-lender refinancing down 23%, external refinancing down 0.8%) as reported by Banking Day, 16 September 2026.
- Australian Prudential Regulation Authority, Prudential Practice Guide APG 223 Residential Mortgage Lending, current version dated 19 June 2025 (serviceability buffer, material changes to loan conditions, overrides).
- Australian Prudential Regulation Authority, “Housing lending standards: Reinforcing guidance on exceptions”, letter to all ADIs signed by Chair John Lonsdale, 9 June 2023.
- Reserve Bank of Australia, “Statement by the Monetary Policy Board: Monetary Policy Decision”, 29 September 2026 (cash rate target 4.60 per cent).
- Figures are as published by the sources cited and are not independently verified by The Broker Times.
Breaking news for modern brokers
Lender policy, regulation and market data, read for what it changes on your files.
Broker Tool
Retention Book Triage
Four questions about one client in your existing book. The output is a suggested review posture and what to evidence — not a credit assessment, and not a recommendation.
Suggested posture
This tool needs JavaScript. The same logic in short: prioritise clients with something changing in the next 90 days; establish capacity before offering options; treat a declined client and an unasked client as different conversations; and record the comparison and the reason whichever way the file goes.
“Refinancing has collapsed, so there is nothing in the back book.”Check
Both halves fell — but very unevenly.
Equifax’s September 2026 data has switching to a different lender down 8.8% and same-lender refinancing down 28%. Of the borrowers still refinancing, a larger share are leaving their lender than a year ago. The back book is quieter, not closed.
“Internal refinancing is the easy option, so it should be holding up.”Check
It is the channel that fell furthest.
At −28% it was the steepest fall of any segment in the release, and it was also the weaker channel a month earlier: Banking Day reported same-lender down 23% against external down 0.8% in the year to August. One contributing factor may be that APRA’s APG 223 expects a new serviceability assessment whenever there are material changes to loan conditions, which removes the “light touch” assumption from some same-lender restructures.
“If a client failed serviceability once, the buffer rules them out.”Check
A decline is one lender’s policy at one point in time.
APG 223 states ADIs must apply a buffer of at least 3.0 per cent over the loan’s rate unless APRA determines otherwise, but how that interacts with income treatment, liabilities and expenses varies across a panel, and non-ADI lenders are not subject to the framework in the same way. APG 223 also contemplates loans approved outside an ADI’s serviceability criteria, which it terms overrides, subject to risk limits and a defined approval process — a matter internal to each lender, not something a broker or client can invoke. Confirm the position with your licensee.
“Older borrowers are winding down, so they are not a refinance segment.”Check
Of the cohorts reported, the over-55s were the only ones growing.
Lender switching rose 3.2% among 56 to 60 year olds and 2.3% among the over-60s in September, while 26 to 35 year olds fell 14.2%. The margins are thin, and lending to borrowers approaching retirement carries its own assessment and documentation expectations around loan term and exit strategy — so it is a segment to review first, not a segment to assume.
“If the client stays put, there is nothing to put on the file.”Check
Staying put is still an outcome you recommended.
A file showing what was compared, at what borrowing level, and why no change was the better result reads very differently from a file with a year of silence on it. The form that record should take is a question for your licensee or aggregator compliance team, not for a general article.
Lender policy and market data, read for what it changes on your files.
General information for Australian mortgage brokers. This tool does not assess serviceability, does not produce a credit decision and is not a recommendation. Figures referenced are as published by Equifax’s Consumer Market Pulse for September 2026 (as reported by MPA, Australian Broker, Smart Property Investment and The Adviser), Banking Day’s report of the August 2026 figures, and APRA’s APG 223 and its 9 June 2023 letter on exceptions. Confirm your own obligations and process with your licensee or aggregator compliance team.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.