Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: Bank Branches Fell 3.0% and the Regional Decline Was the Smallest on Record. The Moratorium Holding It There Runs Out Mid-2027 for NAB and ANZ
The Broker Times · Data Brief
Australia’s Branch Network, Year to 30 June 2026
APRA’s annual Points of Presence release, published 14 October 2026, with the counts from Canstar’s analysis of the same data.
The headline numbers
Where the year’s closures landed
The moratorium clock
- NowAPRA says a government-agreed moratorium on regional branch closures with the major banks is part of why the regional fall is the smallest on record.
- Mid-2027NAB and ANZ commitments expire, on Canstar’s account of the arrangements.
- 2030Westpac’s commitment runs through 2030.
- December 2030CBA’s commitment, extended to this date.
What the moratorium does not reach
Non-major lenders
Canstar reports the commitments do not cover non-majors, and that Bank of Queensland, Bendigo and Adelaide Bank, Heritage and People’s Choice each reduced regional branches.
Metropolitan branches
Net 72 of the year’s 97 closures were in major cities. A regional commitment does not hold a suburban branch open.
ATMs and cash access
Bank-owned ATMs fell 184 to 4,959 on Canstar’s count, and Bank@Post outlets fell 61 to 3,304.
The takeaway for your files
Where a client’s preference for a particular lender rests on having a branch nearby, that preference now sits on a footprint that fell 3.0% in the latest year and, for two of the majors, on an arrangement that expires mid-2027. RG 273.75 asks you to be able to explain why a non-cost consideration realistically offers that client greater value — which is a harder sentence to write about a branch in 2026 than it was in 2021. General information only: confirm your obligations with your licensee or compliance adviser.
News · Lender Distribution
Bank Branches Fell 3.0% and the Regional Decline Was the Smallest on Record. The Moratorium Holding It There Runs Out Mid-2027 for NAB and ANZ
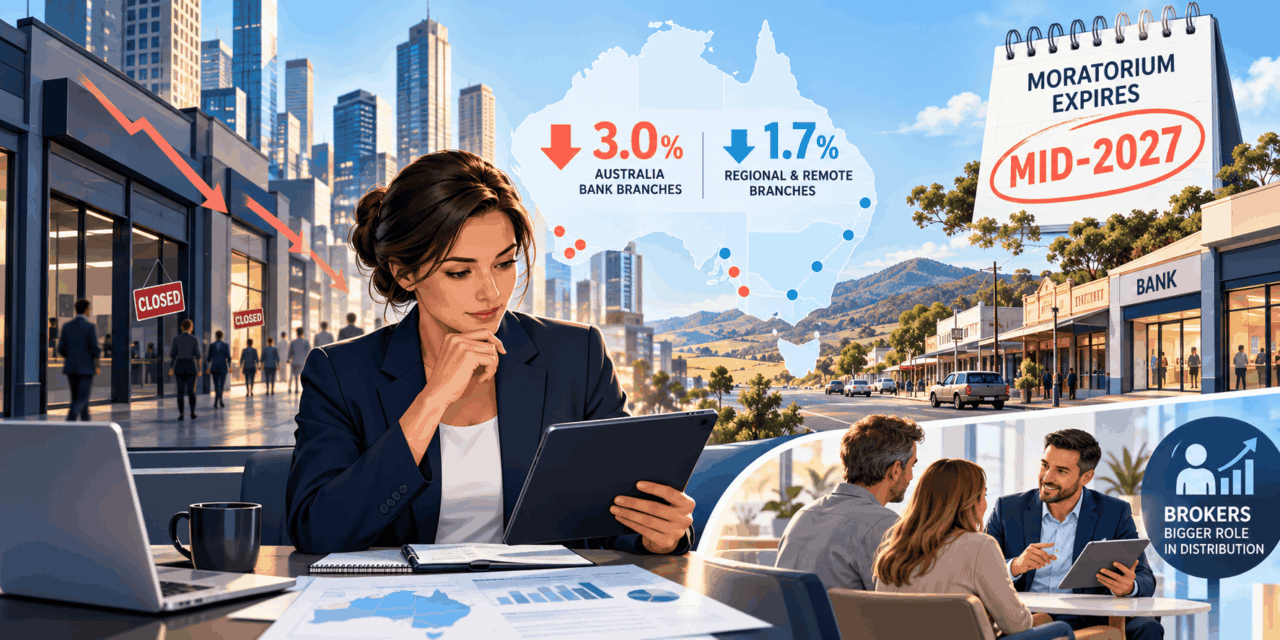
APRA published its annual Points of Presence statistics on 14 October 2026. The national branch number fell 3.0% in the year to 30 June 2026, and the regional and remote fall of 1.7% was the smallest since the series began. The regional figure reads like a floor. APRA’s own release says part of the reason is a government-agreed moratorium with the major banks — and on Canstar’s account of those arrangements, two of the four commitments expire in mid-2027.
Key takeaways
- APRA: branches nationwide fell 3.0% between June 2025 and June 2026. Regional and remote areas recorded their smallest fall since the data series began, at 1.7%, which APRA says is partly explained by a government agreement with the major banks on a moratorium on regional closures.
- Canstar’s analysis of the same APRA data, reported by Australian Broker, puts the network at 3,108 branches — a net fall of 97 for the year and 1,215 over five years.
- Net 72 of the year’s 97 closures were in major cities, on Canstar’s figures. The closures are now mostly metropolitan.
- Canstar reports the major-bank commitments expire mid-2027 for NAB and ANZ, run through 2030 for Westpac and to December 2030 for CBA, and do not cover non-major lenders.
- Where a client’s lender preference rests on branch presence, RG 273 recognises non-cost considerations of that kind — including a credit provider’s service levels and policies — and RG 273.75 asks you to be able to assess that the consideration realistically offers that individual client greater value. This is general information — confirm your obligations with your licensee or compliance adviser.
In this article
What APRA actually published
APRA’s Points of Presence collection is a once-a-year count of the physical banking channels Australian ADIs operate — branches, ATMs, EFTPOS facilities and other service points — categorised by remoteness under the Australian Statistical Geography Standard. The 14 October 2026 release covers the year to 30 June 2026, and the accompanying data file now runs from June 2017 to June 2026. The next edition is scheduled for October 2027.
Two sentences in the release do the work. The first: “The number of bank branches nationwide fell 3.0 per cent between June 2025 and June 2026.” The second: “Regional and remote areas experienced the smallest fall recorded since this data series began (1.7 per cent).” APRA adds that the decline is slower than in previous years, and that a government agreement with the major banks on a moratorium on regional branch closures partly explains the regional result.
That last clause is the one worth sitting with. APRA is not presenting the regional number as a market outcome. It is presenting it, in part, as a policy outcome — and policy arrangements have end dates in a way that market trends do not.
The counts behind the percentage
APRA’s release gives percentages rather than totals. The counts in circulation this week come from Canstar’s analysis of the same APRA file, as reported by Australian Broker on 15 October. Because these figures have appeared through one analyst’s read of the data rather than in APRA’s release text, they are worth attributing as such when you quote them to a client.
On Canstar’s numbers, the network lost a net 97 branches over the year to 30 June 2026, taking the national total to 3,108. That is a five-year net fall of 1,215 branches, or 28% since June 2021. Measured against the 5,694 branches recorded at the start of APRA’s series in June 2017, the network is roughly 45% smaller.
Bank-owned ATMs fell by 184 over the year to 4,959, which Canstar describes as a network more than a third smaller than five years ago. CBA made the deepest ATM cut at 45 machines; NAB was the only major to add ATMs, with 21, while still operating the fewest of the four.
The closures moved to the cities
The most useful thing in the data for a broker is not the headline fall. It is the geography of it, which has inverted from the story everybody learned to tell between 2020 and 2023.
Canstar’s split puts net 72 of the year’s 97 closures in major cities, and net 25 outside them. The non-metropolitan figure has collapsed from 122 in FY2022 to 29 in FY2025 to 25 in FY2026. Among the majors, Westpac recorded the largest reduction at 17 branches, down to 475, with only one of those in a regional area; CBA was down 14, NAB down 4, and ANZ was unchanged at 284, having shifted one branch from a major city to an outer regional area. Nearly all the major-bank reductions, on Canstar’s read, were metropolitan.
Why that matters commercially. If you have been assuming branch risk sits with your regional clients, the last twelve months point the other way. The suburban client who chose a lender partly because there was a shopfront fifteen minutes away is, on these numbers, the one more likely to have lost it.
The moratorium has a date on it
APRA names the moratorium as part of the explanation for the regional result but does not set out its terms. Canstar’s reporting of the arrangements gives the timeframes: CBA’s commitment extended to December 2030, Westpac’s running through 2030, and NAB’s and ANZ’s expiring in mid-2027.
Mid-2027 is not a distant horizon. It is inside the life of almost every pre-approval you will write between now and Christmas, and well inside the first fixed term on a loan settling this quarter. Tindall’s framing, as quoted by Australian Broker, is the right one to carry into a client conversation: “However, this problem has been paused, not solved.”
None of that is a prediction that NAB or ANZ will close regional branches in July 2027. It is simply the difference between a commitment with a stated end date and a commitment without one, and that difference belongs in your thinking when a client treats a nearby branch as a durable feature of the lender they are choosing.
Who the moratorium does not cover
The moratorium arrangements run to the major banks. Canstar reports they do not cover non-majors, and that Bank of Queensland, Bendigo and Adelaide Bank, Heritage and People’s Choice each reduced regional branch numbers over the year.
For brokers, that creates a genuinely awkward crossover. Several of those lenders are the ones a regional or outer-regional client is most likely to name warmly — the local mutual, the bank the family has used for three decades. On these figures, that is also the part of the panel with no closure commitment attached to it. The sentiment and the shelter point in opposite directions.
Access to cash is thinning through the other channel too. Canstar’s count has Bank@Post outlets down 61 over the year to 3,304, with ANZ having become the last major bank to join the service in December 2025.
Why this is a broker question
Two weeks of industry coverage will file this as a banking story. It is a distribution story, and brokers are now the distribution.
The MFAA reported on 3 September 2026 that brokers facilitated a record 81.6% of all new residential home loans in the June 2026 quarter, representing $139.08 billion in new home lending. Set that beside a proprietary network that has lost 1,215 branches in five years and the shape of the market is hard to miss.
It is worth being precise about what that juxtaposition does and does not show. These are two separate releases, measuring two different things, and neither establishes that branch closures caused the broker share — or the reverse. What the pairing does establish is where the obligation now sits. If the branch is no longer the place a borrower gets advice about a mortgage, then the broker is the only party in the transaction with a statutory duty to act in that borrower’s best interests. The channel that carries 81.6% of new lending is the channel carrying the duty.
Where branch access meets RG 273
ASIC’s Regulatory Guide 273, Mortgage brokers: Best interests duty, issued 24 June 2020, is explicit that price is not the whole of the assessment. RG 273.57 states: “Cost is not the only matter relevant to whether recommending a product is in the consumer’s best interests.”
The guide also names the kind of preference a branch represents. Among the matters RG 273.48 lists for consideration is “the consumer’s priorities and preferences for different products or credit providers”, including the credit provider’s level of service. RG 273.71 goes further, noting that “some consumers may also derive value from other loan features” and giving two kinds of example: substantive features such as an offset account or redraw facility, and matters that are harder to quantify, such as the service levels and policies of the credit provider. RG 273.82 adds that judgment matters particularly where a consumer holds strong preferences or strongly held beliefs about certain credit providers.
So a client’s preference for a lender with a branch nearby is a legitimate, recognised, non-cost consideration. It is not a loophole and it is not a problem. The point is what RG 273.75 then asks of you: where a product is recommended on the strength of one of those features, you should be able to make an overall assessment that the non-cost consideration realistically offers that individual consumer greater value.
The practical change. Nothing in RG 273 changed this week. What changed is the evidence base for one particular sentence. A note reading “client prefers a lender with local branch access” was easier to stand behind when the network was 4,300 branches and shrinking slowly in the cities. Against a national total of 3,108, down 3.0% in the latest year, with net 72 of the last year’s closures in major cities and two major-bank commitments expiring mid-2027, the same note now invites an obvious follow-up question — and it is better to have answered it on the file than to answer it in a review.
None of this is advice on your obligations, and it is not a statement of what any licensee requires. Record-keeping standards and the wording your file notes should carry are matters for your licensee or compliance adviser, and RG 273 should be read in full rather than through the paragraphs quoted here.
The cash conversation
Cash access is the version of this issue clients raise unprompted, usually on behalf of a parent or a cash-handling business. Australian Broker’s report cites a 2025 Reserve Bank survey finding that one-third of Australians would face hardship or major inconvenience if cash became hard to access — which is a useful figure to have when a client’s objection sounds like a minority concern and is not.
That is a servicing question rather than a credit question, and it is often better answered by mapping the client’s actual cash needs onto what the lender and Bank@Post still offer locally than by changing the lender on the application. Tindall noted Australian Banking Association work exploring options such as multi-bank hubs, while cautioning that any such model has to improve access without undermining competition.
What to review this week
A four-step review
- Pull the files where branch access is in the notes. Search your CRM for “branch”, “local”, “in person” and “walk in” in client objectives and preference fields. These are the files where the evidence base has moved, and they are the quickest thing on this list to fix.
- Sort your panel by closure exposure, not by rate. Mark which of your regularly used lenders are majors covered by a closure commitment, which commitments expire in mid-2027, and which lenders have no commitment at all. It is a one-page table and it will outlast this news cycle.
- Separate the two client needs. Branch access for cash and day-to-day banking is not the same need as branch access for a mortgage. A client can keep a transaction account where they like and borrow elsewhere. Teasing those apart in the first conversation avoids a lender choice made on the wrong ground.
- Draft your standard answer now. When a client says they want a bank with a branch nearby, you want a settled response: acknowledge it, record it as the preference it is, test it against what the client will actually use the branch for, and document the overall assessment. Writing it once beats improvising it twenty times.
What to watch next
Three things sit on the calendar. APRA’s next Points of Presence release is due in October 2027 and will be the first to measure a period running up against the NAB and ANZ expiry. Any extension, renegotiation or lapse of those commitments will be announced long before the data shows it — watch for it from mid-2027, or earlier if the arrangements are revisited. And the non-major reductions Canstar identified are the ones to track quarter by quarter, because they are the ones with no public commitment governing them.
The strategic read is simpler than the numbers. For twenty years, “which bank has a branch near you” was a question a mortgage conversation could reasonably lean on. On APRA’s own series, that question is becoming harder to answer durably, and for two of the four majors the most reliable part of the answer has a 2027 date attached. Brokers who have already moved the conversation from where the lender is to what the lender does will barely notice. For everyone else, this is a cheap week to update a sentence that has been sitting in client files for years.
Frequently asked
Does APRA’s release say branch closures are over?
No. APRA describes “the ongoing trend of a decline in physical points of presence”, noting only that the decline is slower than in previous years. The 3.0% national fall and the record-low 1.7% regional fall are both falls.
Is the moratorium a legal requirement on the banks?
APRA’s release describes it as a government agreement with the major banks on a moratorium on regional branch closures, not as a prudential standard or a statutory obligation. The expiry timeframes quoted in this article come from Canstar’s reporting of those arrangements rather than from APRA.
Can a client’s preference for a branch justify a more expensive loan?
RG 273.57 states that cost is not the only relevant matter, and RG 273.71 recognises value derived from harder-to-quantify features such as a credit provider’s service levels and policies. RG 273.75 then asks that where a recommendation rests on such a feature, you be able to make an overall assessment that it realistically offers that individual consumer greater value. How that applies to a specific file is a question for your licensee or compliance adviser, and RG 273 should be read in full.
Which lenders are outside the closure commitments?
Canstar reports that the moratorium arrangements do not cover non-major banks, and names Bank of Queensland, Bendigo and Adelaide Bank, Heritage and People’s Choice as having reduced regional branches over the year. That is not a complete list of uncovered lenders — it is the set named in that analysis.
Did branch closures cause the record 81.6% broker share?
Neither release establishes that. The MFAA’s 81.6% figure for the June 2026 quarter and APRA’s branch data are separate publications measuring different things. They describe the same market without demonstrating a causal link between them.
Sources
- APRA, APRA releases latest Points of Presence Statistics for authorised deposit-taking institutions, media release, 14 October 2026
- APRA, Authorised deposit-taking institutions’ points of presence statistics, statistical publication, 14 October 2026
- Australian Broker, Bank branch numbers fall by 97 as five-year losses top 1,200, 15 October 2026 (Canstar analysis)
- MFAA, Mortgage broker market share reaches record 81.6%, 3 September 2026
- ASIC, RG 273 Mortgage brokers: Best interests duty, issued 24 June 2020
Breaking news for modern brokers
Lender policy shifts, regulator moves and the numbers behind them — written for brokers, not for banks.
Interactive · Broker Tool
Branch Preference Triage
A client says they want a lender with a branch nearby. Work out what that preference is actually worth on this file, and what belongs in the note.
What will the client actually use the branch for?
Where is the client?
Which part of the panel is in play?
Your read
Choose an option in each of the three steps and the read will appear here.
General information only, built from the sources cited in the article above. It is not compliance advice and does not state what your licensee requires — confirm your obligations and file-note standards with your licensee or compliance adviser, and read RG 273 in full.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.