The Broker Times · Data Brief
The Economy in Your Client’s Last Tax Return Is Not the One They Are Trading In
NAB’s September 2026 Monthly Business Survey, taken 23–30 September across around 296 non-farm businesses, read weaker on confidence than at almost any point in the survey’s history — while the documents on a self-employed file still describe FY24 and FY25.
What the September survey recorded
All figures from NAB Monthly Business Survey, September 2026 (released 13 October 2026). Index points are net balances.
Business confidence, down 4pts and 18pts below its long-run average of 4
Where September’s confidence reading sits in the survey’s own history
Employment index, down 3pts to its lowest level in five years
Capacity utilisation — down 0.2ppts, still around 1ppt above its long-run average
Purchase cost growth, quarterly rate, against 0.8% final price growth
Forward orders, around 7pts below both February and the long-run average
The aggregate is not the file: trend conditions by industry
September 2026, trend net balance. Zero marked by the centre line. Source: NAB Monthly Business Survey, September 2026, Table 1.
And by state
Trend business conditions, September 2026. National trend conditions: +1. Source: NAB Monthly Business Survey, September 2026, Table 1.
Western Australia — the strongest state reading
Tasmania
South Australia
New South Wales
Queensland
Victoria — the weakest state reading
Where the gap shows up in the documents
Policy positions as stated in the documents named. Each is a guide only — confirm the current requirement with the lender or your BDM before relying on it.
Two lodged years, and a dated floor
Thinktank’s self-employed full doc pathway asks for the last two years of lodged company or business tax returns and financial statements, plus two years of lodged personal returns for all borrowers and guarantors. The guidelines state that after 1 April 2026, June 2024 and June 2025 returns are required. Servicing income is net profit before tax plus acceptable add backs.
AFG Align Thinktank Residential Credit Guidelines v20260817
The policy already names the bridge
Bank of Sydney’s guide lists, as additional supporting information for self-employed applicants, business activity statements covering the trading period since submission of the most recent taxation returns, and written advice from an accountant or tax adviser confirming actual or likely income levels.
Bank of Sydney Credit Policy, 1 September 2026 — described in the document as a guide only, not the full policy
A shorter look-back, on conditions
BCU’s policy allows one year of full business and personal tax returns plus notices of assessment, not annualised, where the LVR is 80% or less, the loan is non-LMI, and the applicant has been self-employed for at least 12 months. The LMI pathway reverts to the last two years.
BCU RP 1.14, 10 July 2026
Where a softening year collides with a variance rule
Self-cert vs verification: 30%
On Thinktank’s mid doc pathway, the variance between the income self-certification form and the additional verification method cannot be greater than 30%.
Quarter to quarter: 30%
On the BAS pathway, enhanced verification may be requested where the variance across two quarters is greater than 30%.
Turnover cap: 40%
Mid doc income for servicing is the lesser of the self-declared income or 40% of gross business turnover, with higher turnover scenarios requiring Head of Credit approval.
Statement currency: 6 weeks
Six months of trading bank statements must be in the name of the earning entity and within six weeks of the application date.
All four from AFG Align Thinktank Residential Credit Guidelines v20260817. Other lenders set their own tests; this is one panel document, not the market.
The takeaway
Nothing in the September survey changes a lender’s documentary requirements, and nothing in it says your client’s business is in trouble. What it does say is that the gap between a lodged return and current trading is more likely than usual to be material right now — and that the direction of that gap is not uniform across industries or states.
The practical consequence is narrow and specific: on a self-employed file, find out what the business is doing now before the assessor does, and record what you found.
Sources: NAB Monthly Business Survey, September 2026 (National Australia Bank, released 13 October 2026); AFG Align Thinktank Residential Credit Guidelines v20260817; Bank of Sydney Credit Policy, 1 September 2026; BCU RP 1.14, 10 July 2026. Lender policy positions are summaries of the documents named and are current only to those documents — confirm with the lender before relying on any of them.
The Broker Times · News
NAB’s Employment Index Fell to a Five-Year Low and Confidence Sits in the Bottom 5% of the Survey’s History. Your Self-Employed Client’s Last Lodged Return Describes a Different Year
The September survey does not change a single documentary requirement on your panel. It changes the odds that the two lodged years on a self-employed file no longer describe the business an assessor is being asked to lend against.
On 13 October, NAB released its Monthly Business Survey for September. Business confidence fell for a third consecutive month to −13 index points, a reading the survey itself places in the bottom 5% of observations in its own history. For brokers, the number that matters more sits one line below it: the employment index fell 3 points to its lowest level in five years.
In this article
- What the September survey actually recorded
- Why the national number is the least useful part
- The document gap on a self-employed file
- Where a softening year collides with a variance rule
- What this does, and does not, do to your best interests record
- Where the duty stops when you diversify
- What to review this week
- What to watch next
What the September survey actually recorded
NAB’s Monthly Business Survey for September 2026 was conducted from 23 to 30 September across around 296 businesses in the non-farm sector. Business confidence fell 4 points to −13 index points, against a long-run average of 4 — 18 points below that average, and 22 points lower than a year earlier. The survey notes that September’s level of confidence is now in the bottom 5% of observations in the history of the series.
Business conditions were flat at −1 index point, 7 points below their long-run average of 7. That stability is composite rather than real. Trading conditions rose 1 point to 4 and profitability rose 3 points to −5, and those small gains were offset by a 3-point fall in the employment index to −1 — its lowest reading in five years. All three subcomponents now sit well below their long-run averages.
The cost side has not moved in brokers’ favour. Purchase cost growth edged up 0.1 percentage points to 2.4% at a quarterly rate while final product price growth was flat at 0.8%, and labour cost growth eased 0.1 percentage points to 1.7%. The survey describes the gap between purchase cost growth and product price growth as continuing to widen, with businesses facing pressure on margins. Forward orders fell 1 point to −1 index point, around 7 points below both their February level and their long-run average. Cash flows recorded another negative reading.
Two readings cut the other way, and they matter for anyone tempted to treat this as a uniform downturn. Capacity utilisation eased 0.2 percentage points to 82.3% but remains around 1 percentage point above its long-run average, and rose in five of eight industries. The capital expenditure index has risen for three consecutive months and now sits above its long-run average. NAB’s own commentary calls the combination of weak confidence, cost pressures, above-average capacity utilisation and softer profitability “unusual”.
NAB Monthly Business Survey, September 2026
Why the national number is the least useful part
A national net balance tells you almost nothing about the panel beater, the physio practice or the civil contractor sitting in front of you. The industry and state splits do, and in September they were wide.
On trend business conditions, mining read +13 and finance, business and property +10, with transport and utilities at +7 and construction at +5. Wholesale sat at 0. Below the line, recreation and personal services read −2, manufacturing −9 and retail −13. Confidence fell in five of eight industries during the month, and in trend terms confidence remains negative in every industry except mining.
The state picture is just as uneven. Trend conditions in Western Australia read +16, Tasmania +8 and South Australia +3, against New South Wales at 0, Queensland at −1 and Victoria at −3 — the weakest state reading — with the national trend at +1. On trend confidence, New South Wales was weakest at −12 and Tasmania the only state in positive territory at +3.
For a broker, that dispersion is the operative fact. A WA-based earthmoving business and a Victorian retailer are not in the same economy this quarter, and a servicing assessment built on the assumption that last year’s profit carries forward is more fragile in one of those files than the other. The exposure is not evenly spread across your book, which means neither is the work.
The document gap on a self-employed file
Here is the structural problem the survey exposes. Full-doc self-employed assessment is, by design, backward-looking. The documents a lender asks for describe completed financial years. The business is trading now.
Thinktank’s residential credit guidelines distributed through AFG Align illustrate how firmly that look-back is fixed. The self-employed full doc pathway asks for the last two years of lodged company or business tax returns and financial statements, plus the last two years of lodged personal tax returns and income statements for all borrowers and guarantors. The guidelines state that after 1 April 2026, June 2024 and June 2025 returns are required. Income for servicing is calculated as net profit before tax plus acceptable add backs.
Read that against the September survey and the issue is plain. A FY25 return closed on 30 June 2025. The trading conditions NAB measured in late September 2026 are more than a year further on, and the survey points to further slowing from here. Nothing about that makes the return invalid — it remains exactly what the policy asks for — but it does mean the gap between the document and the business is more likely than usual to be material, and more likely than usual to be in one direction.
Some policies name a shorter look-back on conditions. BCU’s policy, at RP 1.14 dated 10 July 2026, allows one year of full business and personal tax returns plus notices of assessment, not annualised, where the LVR is 80% or less, the loan is non-LMI, and the applicant has been self-employed for at least 12 months. The LMI pathway reverts to the last two years. That is a narrower window on an older year, not a window on current trading.
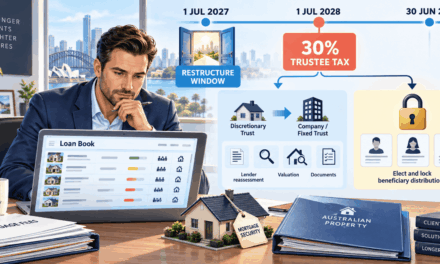
The more useful observation is that the bridge is already written into policy. Bank of Sydney’s credit policy guide, dated 1 September 2026, requires the standard two years of returns and notices of assessment for individuals, or two years of returns and accountant-prepared financial statements for corporate and trust borrowers, with tax status confirmed through the Tax Portals and Integrated Client Account Portal for each self-employed borrower and guarantor. It then lists, as additional supporting information, business activity statements covering the trading period since submission of the most recent taxation returns, and written advice from an accountant or tax adviser confirming actual or likely income levels.
The practical point. The documents that close the gap between a lodged return and current trading are the ones lenders already name as supporting information: BAS covering the period since the last return, and an accountant’s written view of actual or likely income. In a quarter where conditions are moving, the difference between a clean assessment and a stalled one is often whether those arrived with the application or three days after the assessor asked.
Bank of Sydney’s document describes itself as a guide only and not the full version of its home loan policy, and every position above is current only to the document named. Confirm the requirement with the lender or your BDM before you build a file around it.
Where a softening year collides with a variance rule
Mid-doc and alt-doc pathways are the obvious answer for a self-employed client whose paperwork is behind, and they are also where a deteriorating trading year does the most damage — because those pathways are built on consistency tests.
On Thinktank’s mid doc pathway, the income self-certification form must be supported by one of an accountant’s declaration form, the last two BAS, the last six months of trading bank statements, a one-year tax return plus notice of assessment, a one-year accountant-prepared financial statement, or a one-year return and notice of assessment plus a one-year financial statement. The guidelines state that the variance between the self-certification form and the additional verification method cannot be greater than 30%.
Consider what that means when turnover is falling. A client who self-certifies from a stable memory of last year, verified against six months of trading bank statements reflecting a softer current year, can breach a 30% variance test without anyone misleading anyone. On the BAS pathway, the same guidelines provide that enhanced verification may be requested where the variance across two quarters is greater than 30%, and that income for servicing is the lesser of actual self-declared income or 40% of gross business turnover, with higher turnover scenarios requiring Head of Credit approval. Six months of trading bank statements must be in the name of the earning entity and dated within six weeks of the application date.
None of those thresholds has changed. What has changed is how easy they are to trip. A broker who sets the self-certified figure from current trading rather than last year’s profit is not being conservative for its own sake — they are avoiding a variance referral that costs a week and, in the worst case, a decline that now has to be explained to the next lender.
Worth saying plainly: these four tests come from one panel document. Other lenders set their own thresholds, and the absence of a rule from this article is not evidence that a lender does not have one. Check the policy that applies to the file in front of you.
What this does, and does not, do to your best interests record
It is tempting to read a weak business survey as a compliance event. It is not. No obligation moved on 13 October, and a macro data release does not create a new duty.
What it does affect is the quality of the inquiry behind a recommendation. ASIC’s Regulatory Guide 273 sets out how the regulator assesses compliance with the best interests obligations in Part 3-5A of the National Credit Act, and the duty itself sits in sections 158LA and 158LE. RG 273.7 defines mortgage brokers, by reference to section 15B, as persons who carry on a business of providing credit assistance in relation to credit contracts secured by mortgages over residential property, who do not act as the credit provider in relation to most of those contracts, and who provide credit assistance in relation to credit contracts offered by more than one credit provider.
The connection to a self-employed file is a practical one rather than a new rule. If the income position you relied on was a year old and the business had visibly changed, the recommendation rests on a weaker foundation — and the file will show it. A short, dated note recording what the client said about current trading, what document was obtained to test it, and why the income figure used was adopted is ordinary good practice that happens to be worth more in a quarter like this one. How your licensee wants that recorded is a question for them, not for this article.
Where the duty stops when you diversify
A softening business economy pushes brokers toward commercial and asset finance, and it is worth being precise about where the best interests duty travels with you and where it does not.
RG 273.5 states that the best interests obligations apply only in relation to credit products regulated under the National Credit Act — that is, products provided to consumers for personal, domestic or household purposes, or for the purchase or improvement of residential investment property. RG 273.133 then makes clear that, as a mortgage broker, the duty applies to any credit assistance you provide, including credit assistance on products packaged with a mortgage and on standalone credit products. RG 273.134 states that the duty does not apply in relation to non-credit products such as insurance, and that you must not imply that it does.
Example 12 in RG 273 makes the consequence concrete: an intermediary who tells consumers the best interests duty applies to them when it does not is likely to have engaged in misleading or deceptive conduct, prohibited by the ASIC Act and the National Credit Act.
That is general information about what the guide says, not advice about your licence. Whether a particular transaction is regulated turns on its purpose and structure, and getting that wrong in either direction has consequences — so the call belongs with your licensee or compliance adviser, on the facts of the deal.
What to review this week
- Filter your pipeline for self-employed applications, not just self-employed clients. The exposure is in files where income has been assessed but the deal has not settled, and in pre-approvals that will be re-tested before they are used.
- Sort that list by industry before you sort it by size. On NAB’s September trend readings, retail at −13 and manufacturing at −9 are a different conversation from mining at +13 or finance, business and property at +10.
- Ask one direct question about current trading. Turnover and margin over the last two quarters against the same period last year. You are not auditing the business; you are finding out whether the document you hold still describes it.
- Where the answer is “softer”, get the bridging documents up front. BAS covering the trading period since the most recent return, and an accountant’s written view of actual or likely income, are already named as supporting information in policies on the panel.
- Check your self-certified figures against the variance tests that apply. Where a mid-doc pathway is in play, set the declared figure from current trading, not from last year’s profit.
- Diarise the statement currency rules. A six-week window on trading bank statements is short enough that a delayed file quietly goes stale.
- Record the inquiry and the reasoning, in a dated note. Not a template line — what you asked, what you were told, what you obtained, and what you used.
- Confirm the current requirement before you rely on it. Every policy position in this article is a summary of a dated document, not a live quote from a lender.
What to watch next
NAB’s next Monthly Business Survey is due on 10 November 2026. The three readings worth watching are the employment index, which fell to a five-year low in September; forward orders, which sit around 7 points below their long-run average; and capacity utilisation, which at 82.3% remains the main piece of evidence against reading all of this as a broad contraction. The survey’s own framing is that it is unusual for capacity utilisation and business conditions to diverge for sustained periods.
If the employment index keeps falling while capacity utilisation holds above average, the self-employed files most exposed are the ones in industries carrying cost pressure without pricing power — which, on September’s numbers, is a description of retail and manufacturing more than of mining or professional services.
Key takeaways
- NAB’s September survey put business confidence at −13, which the survey places in the bottom 5% of its own history, and the employment index at a five-year low. Conditions were flat at −1.
- The national reading hides a wide spread: trend conditions ran from mining at +13 and WA at +16 down to retail at −13 and Victoria at −3.
- Full-doc self-employed assessment is backward-looking by design. Thinktank’s guidelines, for example, require June 2024 and June 2025 returns after 1 April 2026 — documents that describe a period now well behind current trading.
- The documents that bridge that gap are already named in lender policies as supporting information: BAS covering the period since the last return, and an accountant’s written view of actual or likely income.
- Mid-doc variance tests are where a softening year does damage. On Thinktank’s pathway, self-certification cannot vary from the verification method by more than 30%.
- No obligation changed on 13 October. What changes is the quality of the inquiry behind the income figure you adopt, and whether the file records it.
- RG 273.5 states the best interests obligations apply only to credit products regulated under the National Credit Act. Whether a specific transaction is regulated is a question for your licensee.
Questions brokers are asking
No. Documentary requirements are set by lender policy and by the obligations in the National Credit Act, and neither moved because of a data release. What changes is the probability that the lodged years you hold no longer describe the business, which goes to the quality of your inquiry rather than to the rules themselves.
Lender policies commonly contemplate exactly this situation. Bank of Sydney’s guide lists BAS covering the trading period since the most recent return, and written advice from an accountant or tax adviser confirming actual or likely income levels, as additional supporting information for self-employed applicants. In practice an assessor who identifies the gap after lodgement will ask for the same documents. How your licensee expects a known change in circumstances to be handled and recorded is a question for them.
Because those pathways test consistency. Thinktank’s guidelines provide that the variance between the income self-certification form and the additional verification method cannot be greater than 30%, and that enhanced verification may be requested where variance across two quarters exceeds 30%. When turnover is falling, a figure drawn from last year’s experience and a verification document drawn from this year’s trading can diverge enough to trigger a referral.
RG 273.5 states that the best interests obligations apply only in relation to credit products regulated under the National Credit Act — products provided to consumers for personal, domestic or household purposes, or for the purchase or improvement of residential investment property. RG 273.133 adds that, as a mortgage broker, the duty applies to any credit assistance you provide, including standalone credit products. Whether a given transaction is regulated depends on its purpose and structure, so confirm the position with your licensee rather than assuming either way — and note RG 273.134, which says you must not imply the duty applies to non-credit products when it does not.
Self-employed files that are assessed but unsettled, and pre-approvals that will be re-tested before use, carry the most immediate exposure. Within that list, September’s trend readings point to retail at −13 and manufacturing at −9 as the industries where the gap between a lodged year and current trading is most likely to matter, against mining at +13 and finance, business and property at +10 at the other end.
Breaking news for modern brokers
Lender policy shifts, regulator findings and market data, read for what they change on your files.
Sources. NAB Monthly Business Survey, September 2026, National Australia Bank, released 13 October 2026 (survey conducted 23–30 September 2026, around 296 non-farm businesses; next release 10 November 2026). ASIC Regulatory Guide 273 Mortgage brokers: Best interests duty, published 24 June 2020, at RG 273.5, RG 273.7, RG 273.133, RG 273.134 and Example 12. Lender policy positions are summaries of the following documents and are current only to them: AFG Align Thinktank Residential Credit Guidelines v20260817; Bank of Sydney Credit Policy, 1 September 2026 (described in that document as a guide only and not the full version of its home loan policy); BCU RP 1.14, 10 July 2026. Confirm any policy position with the lender or your BDM before relying on it.
Interactive · Pipeline Tool
Self-Employed File Exposure Check
Pick the client’s industry and state to see what NAB’s September 2026 survey actually recorded for them, then work the document checklist. Nothing is sent anywhere — this runs in your browser.
What industry is the business in?
Where does it trade?
Your reading
Choose an industry and a state above. The figures shown are NAB’s own trend net balances for September 2026 — they describe the sector and the state, never an individual business.
What to establish before you lodge
The bridging-document checklist
Generic to any self-employed file where the lodged years may no longer describe current trading. Tick as you clear each one.
Before you rely on any of it
Lender requirements in this article are summaries of dated policy documents, not live quotes. Confirm the current position with the lender or your BDM, and take compliance questions to your licensee.
Industry and state figures: NAB Monthly Business Survey, September 2026, Table 1, trend net balances. National trend readings for September 2026 were −10 confidence and +1 conditions.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.