Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format, in about five minutes.
This audio version covers: Investors Now Ask “Personal, Company or Trust?” First. Buyer’s Agent Heath Bassett Says Structure Won’t Rescue a Bad Purchase
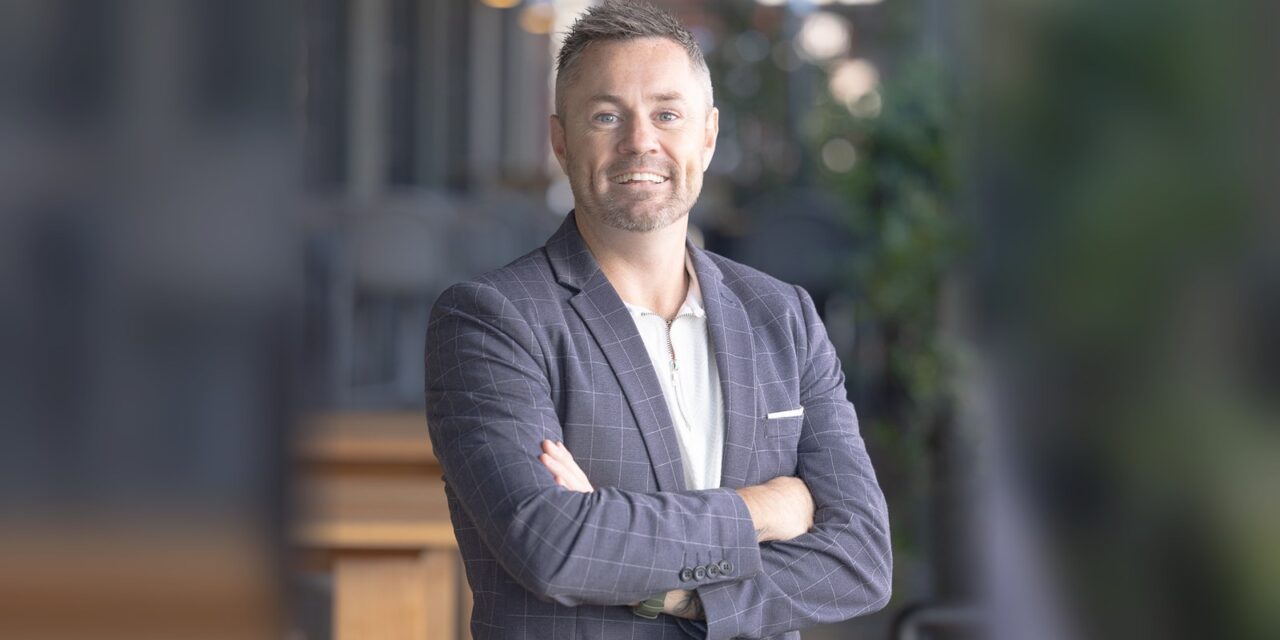
Above: Heath Bassett, co-founder of You&Me Personalised Property Services. Photo: Rolo Media.
Personal, Company or Trust? The Question Investors Now Ask First
Buyer’s agent Heath Bassett, co-founder of You&Me Personalised Property Services, says ownership structure has gone from a rare question to one of the first raised by almost every investor since the May 2026 federal Budget.
The numbers behind the shift
Established stock
Share of new investor loans in 2025 written for existing properties, not new housing (Budget 2026-27 overview).
CGT discount
Replaced from 1 July 2027 by cost base indexation and a 30% minimum tax on gains accruing from that date.
Company tax rates
Base rate entity or full rate (ATO, 2025-26). Rental income counts as passive income in that test.
Start date
When the negative gearing and CGT changes take effect.
Where investor loans went in 2025
The Budget timeline
- Before 12 May 2026
Grandfathered
Established properties already held keep their existing treatment.
- After 12 May 2026
Established purchases caught
Losses can offset other residential property income and carry forward, but not wages or other unrelated income.
- From 1 July 2027
Rules take effect
Negative gearing limited to new builds. 50% CGT discount replaced by indexation plus a 30% minimum tax on gains from that date.
- New builds
Choice retained
Eligible new builds keep negative gearing and can choose the 50% discount or the new CGT arrangements.
Structure snapshot, as framed in the release
| Structure | What Bassett is hearing | Broker file flag |
|---|---|---|
| Personal names | The traditional default, often chosen “without really questioning it”. | Marginal tax rate now meets quarantined losses on established stock. |
| Company | Growing interest. Still subject to the negative gearing changes, but taxed at 25% or 30%. | Different lending and admin implications. Check lender appetite and guarantees. |
| Trust | Now part of the conversation alongside companies. | Tax outcome is adviser territory. Confirm deed, trustee and lender policy. |
What brokers can do
- Ask the structure question before the application, not after pre-approval.
- Map how each option changes the lender panel, servicing and security.
- Refer tax structuring to an accountant or tax adviser, in writing.
What brokers should not do
- Recommend a structure for tax reasons. That is not credit assistance.
- Suggest a company “gets around” the gearing changes. Bassett says it does not.
- Let structure distract from whether the property stacks up.
The takeaway
“Structure is important, but it doesn’t turn a bad investment into a good one.” The ownership question now arrives early. Brokers who can explain the lending side of each option, and hand the tax side to an adviser, stay useful in that conversation.
Sources: You&Me Personalised Property Services / Heath Bassett media release (Hunter & Scribe); Budget 2026-27 overview; ATO company tax rates 2025-26.
Investors Now Ask “Personal, Company or Trust?” Before They Ask About Rates
Since the May Budget, buyer’s agent Heath Bassett says structure is one of the first things almost every investor wants to discuss. For brokers, the answer reshapes the loan before a lender is picked.
In this article
Property investors who rarely thought about ownership structures before this year’s federal Budget are now routinely asking whether their next property should be held personally, through a company or in a trust, according to buyer’s agent Heath Bassett.
That is a view from the buy side, and it lands squarely on the broker’s desk. The structure an investor chooses decides who the borrower is, which lenders will look at the deal, how servicing is assessed and what guarantees are signed. Brokers who hear the question first are better placed than those who hear it at settlement.
From rare question to first question
Mr Bassett says questions about ownership structures have gone from relatively uncommon to featuring in conversations with almost every investor he speaks to.
“Before the Budget, most investors weren’t coming to us asking about structures. Now it’s one of the first things they want to talk about. They want to know what their options are and what buying in one structure rather than another could mean for them.”
Heath Bassett, Co-founder, You&Me Personalised Property ServicesBuyer’s agents usually meet investors before a broker does, or at the same time. If structure is now the opening topic on their side of the table, the same question is heading for your fact find. It is worth being ready for it rather than finding out after pre-approval that the borrowing entity has changed.
What changed in the Budget
The shift follows significant changes to property taxation announced in the May federal Budget. As set out in the release:
- Negative gearing limited to new builds from 1 July 2027. Investors who bought established properties after 12 May 2026 can still deduct property losses against other residential property income and carry excess losses forward, but can no longer use those losses to reduce unrelated taxable income such as wages.
- Grandfathering. Properties held before 12 May 2026 are grandfathered.
- CGT discount replaced. From 1 July 2027, the 50% capital gains tax discount will be replaced with cost base indexation and a 30% minimum tax rate on capital gains accruing from that date.
- New builds keep a choice. Investors in eligible new builds can choose between the existing 50% CGT discount and the new arrangements, and new builds retain access to negative gearing.
Mr Bassett says investors who once saw the tax treatment of property as relatively straightforward are now confronting changes that could materially affect their after-tax returns. That is prompting many to take a closer look at how their investments are structured.
“A lot of investors have traditionally bought in their personal names without really questioning it. Now they’re asking about companies and trusts and wanting to understand what the differences could mean for them.”
Heath Bassett
Why 83% matters to your book
The new-build carve-out is significant because established homes have historically made up the overwhelming majority of investor purchases. According to the Budget overview, 83% of new investor loans in 2025 were for existing properties rather than new housing.
Put simply, the product most of your investor clients have been buying is the product most affected. Expect three things on live files:
- More questions about new builds, which bring their own lending considerations around construction, off-the-plan valuations and lender appetite.
- More interest in entity borrowing, which narrows the lender panel and changes documentation.
- A timing lens. Clients will want to know whether a purchase falls before or after key dates. The 12 May 2026 date has already passed, so any established purchase since then sits under the new rules.
Stay in your lane
Explaining what the Budget announced is fine. Telling a client which structure gives them a better after-tax outcome is tax advice. Refer that part to a registered tax agent or accountant, and note the referral on the file.
The company structure conversation
One option drawing growing interest is buying through a company. Companies are still subject to the new negative gearing restrictions, but they operate under different tax treatment and potentially a lower tax rate, depending on the investor and the company.
Companies are generally taxed at either 25% or 30%, depending on whether they qualify as a base rate entity (current for the 2025-26 tax year). Individual marginal rates can be higher for higher-income investors. Rental income is classed as passive income when working out whether a company qualifies for the lower rate.
“A company doesn’t get around the negative gearing changes. But that’s not the only consideration. For some investors, there can still be reasons to look at a company structure and understand whether the overall tax treatment, borrowing arrangements and asset protection benefits suit what they’re trying to achieve.”
Heath BassettNote the phrase “borrowing arrangements”. Mr Bassett cautions that company structures come with their own lending and administrative implications and will not necessarily leave an investor better off. For brokers, that is the practical core of the story. A company or trust purchase typically means:
- a smaller pool of lenders willing to lend to the entity, with policy that varies lender to lender
- directors or individual trustees usually being asked for personal guarantees
- extra documents, such as company extracts, trust deeds and entity financials
- servicing that may need to consider the entity and the guarantors together
- pricing and fees that can differ from a standard personal investment loan
None of those is a reason to avoid a structure. They are reasons to model the loan before the client commits to an entity based on tax alone.
No single right structure
“There’s no single structure that’s right for everybody. Different structures can have different implications for tax, borrowing, asset protection and what you want to do with the investment later.”
Heath BassettMr Bassett says investors should get independent tax advice before deciding how to structure a purchase. That is the right sequence for brokers too: tax and legal advice sets the structure, then the broker finds finance that suits it. Where the client is still deciding, you can help by showing how each option changes the lending picture, so the adviser and client are working with real numbers.
Where the broker fits
Best Interests Duty asks brokers to act in the consumer’s best interests and prioritise their interests when providing credit assistance. When a structure question is live, that looks like:
- Ask early. Add “who will own this property?” to the first meeting for every investor file.
- Show the lending trade-offs. Lender panel, guarantees, documentation and servicing for personal, company and trust options.
- Refer and record. Refer tax and structuring advice to an accountant, tax agent or lawyer, and note it on the file.
- Check the dates. Confirm when the client bought any existing properties, since grandfathering depends on the 12 May 2026 date.
- Keep the property in view. A good structure will not fix a weak purchase.
Fundamentals still decide the file
Mr Bassett’s closing point is one every broker can repeat. The Budget has changed some tax considerations around property investment, but the basics of a sound investment are the same regardless of how it is owned.
“Structure is important, but it doesn’t turn a bad investment into a good one. You still need to buy the right property, in the right location, at the right price and with the right long-term fundamentals.”
Heath Bassett“Tax should be part of the decision, but it shouldn’t be the reason you invest. Whether you buy personally, through a company or through a trust, ultimately the property itself still has to perform.”
Heath BassettBroker takeaways
- Expect the question. Buyer’s agents report structure is now an early topic for almost every investor.
- Know the dates. 12 May 2026 for grandfathering, 1 July 2027 for the new negative gearing and CGT rules.
- New builds are treated differently. They keep negative gearing and a CGT choice, while 83% of 2025 investor loans were for established homes.
- Companies do not escape the gearing changes, but may be taxed at 25% or 30% and bring different lending terms.
- Refer tax advice, model the lending. That keeps you useful and on the right side of your obligations.
Frequently asked questions
Does buying through a company avoid the new negative gearing rules?
No. According to the release, companies are still subject to the new negative gearing restrictions. The difference lies in tax rates and other features, which an investor should assess with a tax adviser.
Which properties are grandfathered?
Properties held before 12 May 2026. Established properties bought after that date fall under the new treatment from 1 July 2027.
What happens to losses on established properties bought after 12 May 2026?
They can still be deducted against other residential property income and excess losses carried forward, but they cannot reduce unrelated income such as wages.
Can a broker recommend an ownership structure?
Brokers can explain the lending implications of each option. Advice on which structure suits a client’s tax position should come from an accountant, registered tax agent or lawyer.
- You&Me Personalised Property Services / Heath Bassett media release, distributed by Hunter & Scribe
- Budget 2026-27 overview
- ATO company tax rates 2025-26
Stay ahead of the investor conversation
Budget changes, lender policy and market commentary, written for Australian brokers.
More at The Broker Times →Investor Structure Conversation Planner
Pick the property type and the ownership option your client is weighing. You’ll get the Budget rules that apply as announced, the lending checks to run and the questions to refer on. Nothing is stored or sent.
1. What is the client buying or holding?
2. Which ownership option is on the table?
Established purchase in personal names
Budget rules as announced
- Loading…
Lending checks
- Loading…
Refer on: loading…
General information based on the Budget measures as described in the Heath Bassett / You&Me release. Measures take effect from 1 July 2027 and may change before legislation. Not tax, legal or credit advice. Confirm lender policy on every file.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, tax, compliance or financial advice, and it is not a recommendation to buy any property or use any ownership structure. Commentary is attributed to Heath Bassett / You&Me Personalised Property Services, and Budget measures are described as announced and may change before legislation. Investors should seek independent tax advice. Brokers should consult their aggregator's compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC's responsible lending guidelines.