The Broker Times · Lender Policy Snapshot
Rental Income on a Macquarie File: The Numbers That Matter
Figures below are quoted from the Macquarie broker credit guidelines, Version 15.0, last updated 22 October 2026, and from Macquarie’s published serviceability calculator guidance pages.
1. What the credit guidelines count
of gross residential rent, apportioned to the borrower’s ownership share
vacancy shading — which is what the 95% figure represents, not a second cut
floor of gross rental income applied to investment property expenses
of gross for short-term stays, room rentals and non-residential property (20% shading)
2. The gap between the headline and the file
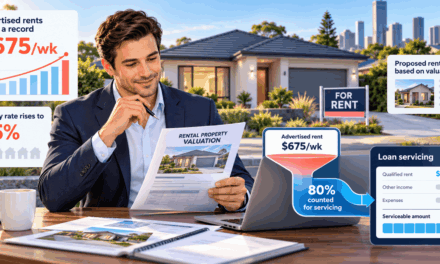
Worked example — a sole-owner residential investment property at $800 per week gross rent ($41,600 a year), on the credit guidelines basis, assuming actual expenses do not exceed the floor:
| Gross annual rent | $41,600 |
| Counted at 95% | $39,520 |
| Less expense floor, 15% of gross | −$6,240 |
| Net rent reaching servicing | $33,280 |
That is 80% of gross, not 95%. The expense floor is the cut most often left out of a mental calculation.
3. Two Macquarie documents, two sets of figures
Broker credit guidelines
Version 15.0, last updated 22 October 2026
- Residential rent counted at 95% of gross
- Expenses at a floor of 15% of gross rent
- Short-term, room and non-residential at 80%
Serviceability calculator guidance
Macquarie broker help pages — no published date shown
- Residential rent considered at 75%, shading applied automatically in the calculator
- Expenses at a minimum of 20% of verified rental income
- Short-term, room and non-residential considered at 65%
The practical point: both documents are Macquarie’s own, and they express the rental treatment differently. Run the lender’s current calculator rather than a remembered percentage, and confirm the treatment with your BDM before you put a capacity figure in front of a client.
4. Also landing on your files
Overtime income
100% for occupations on the guidelines’ essential services list; 80% otherwise. Both require the overtime to be confirmed as regular, ongoing and evidenced.
Liabilities in ApplyOnline
Broker Daily reports that from 26 October, each liability must be marked partially cleared, fully cleared or unchanged, with the payout source stated and all liabilities included.
Policy settings change without notice and are deal-dependent. Confirm every figure against the lender’s current policy document or your BDM before relying on it.
Loan Tips · Lender Policy
The Rent That Reaches Servicing Is Not the Rent on the Lease
Macquarie’s broker credit guidelines were updated on 22 October. The rental income section counts 95% of gross rent — and then applies an expense floor underneath it that most brokers leave out of a quick mental calculation.
Key takeaways
- Macquarie’s broker credit guidelines, Version 15.0, last updated 22 October 2026, count 95% of gross residential rental income, apportioned to the borrower’s ownership share. The guidelines describe that as representing a 5% shading for vacancy — so the 95% and the 5% are the same cut, not two.
- Separately, the guidelines apply a floor of 15% of gross rental income to investment property expenses. On that basis, where actual expenses do not exceed the floor, the rent reaching servicing is closer to 80% of gross than 95%.
- Macquarie’s published serviceability calculator guidance pages state the treatment differently again — 75% of verified rental income considered, with a minimum 20% expense allowance — and carry no published date. Confirm which applies before quoting a client a number.
- Broker Daily reports that from 26 October the ApplyOnline liabilities section requires each liability to be marked partially cleared, fully cleared or unchanged, with the payout source stated.
There is a version of the investment lending conversation that happens hundreds of times a week in Australian broking, and it goes roughly like this. The client has a property returning $800 a week. They want to know what that does to their borrowing capacity. The broker does the arithmetic in their head, applies the shading figure they remember for that lender, and gives a number.
That number is almost always too high, and the reason is rarely the shading. It is the expense floor sitting underneath it.
Macquarie Bank’s broker credit guidelines were updated to Version 15.0 on 22 October 2026, and the rental income section is a clean illustration of why the quick answer so often misses. It also arrives in the same week as a change to how liabilities have to be recorded in ApplyOnline, which is the kind of unglamorous process amendment that quietly generates re-work across a whole book of applications.
What the guidelines actually say
Section 3D of the guidelines sets out the rental income treatment. For standard residential investment property, rental income is counted at 95% of gross rental income, in line with each borrower’s percentage ownership of the property. The guidelines describe that 95% as representing a 5% shading for vacancy.
That wording matters, because it closes off a common misreading. Brokers who see “95% of gross rent” and “a 5% vacancy shading” listed as separate line items in a policy summary sometimes apply both, and shade twice. They are the same cut expressed two ways.
The second cut is genuinely separate. The guidelines state that a floor of 15% of gross rental income will be applied to investment property expenses. It is a floor, not a fixed figure — where the actual, verified expenses on a property exceed 15% of gross rent, the higher number is the one in play. But 15% is the minimum the lender will assume, whatever the client says their outgoings are.
Stack the two and the arithmetic on a sole-owner property returning $800 a week looks like this. Gross annual rent of $41,600. Counted at 95%, that is $39,520. Deduct the expense floor at 15% of gross, or $6,240, and $33,280 reaches servicing. That is 80% of gross rent — a long way from the 95% headline, and $6,240 a year of assessed income different from the answer a broker gives if the expense floor slips their mind.
On a single property that gap is a rounding error in a conversation. Across a client with three investment properties, it is the difference between a pre-approval that holds and one that comes back short.
Not all rent is treated the same, either. The guidelines count short-term stays, room rentals and non-residential property — commercial, industrial and office — at 80% of gross, building in a 20% vacancy shading, with the same 15% expense floor applying. The guidelines also note that where an applicant relies heavily on non-residential rent, lease agreements should be obtained so the risk can be assessed. If your client has moved a property onto a short-stay platform since you last looked at the file, the income assumption underneath your servicing changes.
Two Macquarie documents, two sets of numbers
Here is where it gets more interesting, and where the practical instruction for the week sits.
Macquarie also publishes broker help pages explaining how to input income and liabilities into its serviceability calculator. Those pages set out a different set of figures. They say 75% of verified residential rental income is considered, with shading applied automatically in the calculator. They put investment property expenses at a minimum of 20% of verified rental income, always input at 20% for a new investment property, and at the actual figure for an existing property where actual expenses exceed 20%. Short-term stays, room rentals and non-residential property are described as considered at 65%, with a worked instruction to enter gross rental income multiplied by 0.65 and divided by 0.75.
Both documents are Macquarie’s own. The credit guidelines carry a version number and a last-updated date of 22 October 2026. The calculator guidance pages carry no published date at all, which makes it impossible to tell from the outside how they sit relative to the current pack.
The takeaway is not which document is right. It is that a remembered percentage is the weakest possible basis for a number you are about to say out loud to a client. Run the lender’s current calculator, and where the treatment is material to the deal, confirm it with your BDM before the figure leaves your desk.
That is a dull conclusion, and it is also the correct one. Capacity numbers given from memory are one of the quieter sources of client disappointment in broking — not because the broker was careless, but because lender policy moves faster than anyone’s recall of it, and because the same lender can describe the same treatment in two places in two different ways.
Overtime at 100%, but only for a defined list
The same guidelines pack sets out the overtime treatment, and it is worth knowing precisely because the generous figure is narrowly gated.
Overtime for occupations the guidelines classify as essential services is counted at 100%. Everything else is counted at 80%. Both require the overtime to be confirmed as regular, ongoing and evidenced.
The essential services definition is a closed list, not a judgement call. The guidelines limit it to occupations in named service categories, covering public transport, firefighting, health services, waste and sewerage services, corrections, police, and energy-sector technicians, with electricians excluded. Frontline aged care, frontline disability care and frontline aviation roles qualify. The guidelines carve out general support, cooking, cleaning, administration and baggage handling roles, which means two people employed by the same hospital or the same airport can sit on opposite sides of the line.
For a broker, the discipline is to read the occupation against the list rather than against the employer. A kitchen hand at a hospital is not a health services worker for this purpose, on the guidelines’ own wording. Getting that wrong in either direction — shading income that did not need shading, or assuming the full figure where the list excludes it — changes the capacity you present.
The liabilities change is the one that will cost you time
Broker Daily, in its lender policy round-up for 15 to 22 October published on 23 October, reports a further Macquarie change taking effect from 26 October: the liabilities section in ApplyOnline will require brokers to record, for each liability, whether it is partially cleared, fully cleared or unchanged. For partially cleared liabilities, the new limit and balance must be given. Where a liability is being cleared, the submission must state how — from loan funds, from sale proceeds, or from the customer’s own funds. All liabilities must be included.
This is a single-outlet report at the time of writing, so treat the detail as Broker Daily’s and confirm the specifics with Macquarie or your aggregator before you rebuild a process around it. But the shape of it is familiar, and the cost is predictable. Changes to mandatory fields in a lodgement platform do not reduce approvals; they generate requests for further information on files that were otherwise complete, because the information now has to be captured in a structured field rather than inferred from a supporting document or a note.
The brokerages that handle this well will not be the ones that read the notice. They will be the ones who update their own data collection before the lodgement, so the payout source for every liability being cleared is on file from the client conversation rather than chased afterwards.
It is worth noting the wider context too. The same round-up reports NAB introducing serviceability calculator Version 66 on 23 October, updating its household expenditure measure values, and describes the new calculator as mandatory for new home loan applications submitted after midnight AEDT that day. Two majors adjusting servicing inputs in the same week is a reasonable prompt to re-run any live pre-approval you are relying on.
Why capacity has become the competitive question
None of this would matter much if clients still chose a lender purely on rate. Increasingly they do not.
The Adviser reported in late September on Macquarie Equity Research’s 2026 Mortgage Broker Survey, which found that borrowing power was nominated by 84% of brokers as a factor customers seek from a lender — up 17% year on year and 26% since 2021. Best rates remained the top consideration at 93%, unchanged on the prior year, with time to improve cited by 81% and bank reputation by 43%. The same report noted APRA’s requirement that most residential mortgage borrowers be assessed with a serviceability buffer of three percentage points above the loan rate, which constrains maximum loan sizes and complicates refinancing.
Read those two things together and the commercial logic is plain. When the buffer is doing most of the work in limiting what a client can borrow, the lender-by-lender differences in how income is counted stop being technical trivia and become the thing that determines whether a deal is placeable at all. Rental income treatment is one of the largest of those differences on an investor file.
That is also why precision here is worth more than speed. A broker who can explain to an investor client why $800 a week of rent contributes roughly $33,280 rather than $41,600 to an assessment, and what that does to the number they can borrow, is demonstrating exactly the expertise that is driving brokers to a record share of new residential lending. A broker who gives a confident number from memory and revises it down a fortnight later is undermining it.
A note on file records
Australian mortgage brokers operate under a best interests duty under the National Consumer Credit Protection Act 2009, with ASIC’s guidance on that duty set out in Regulatory Guide 273. The detail of what your obligations require in any given situation is a matter for your licensee and, where needed, your own legal adviser — nothing here should be read as a statement of what the law requires on your files.
What can be said as a matter of practical craft is narrower. Where lender policy on a material input is genuinely ambiguous, and you resolve it by confirming with a BDM or by running the lender’s own calculator, the confirmation is worth recording on the file at the time you get it. Not because a rule here says so, but because a file that shows what you relied on and when is a far easier file to explain six months later than one that shows only the outcome.
What to review this week
- Pull any live investor pre-approval or conditional approval with Macquarie and re-run the servicing on the lender’s current calculator rather than the figure in your notes.
- Check whether you have been applying an expense assumption at all. If your mental model for rental income is a single shading percentage, the expense floor is the thing you are missing.
- Flag any file where rent comes from a short-stay platform, a room rental or a non-residential property. On the guidelines, those sit at 80% of gross rather than 95%, with the expense floor still applying.
- Read your overtime clients’ actual occupations against the essential services list, not against their employer’s industry.
- Update your client data collection for liabilities so that, for every liability being cleared, you capture whether it is partial or full and where the money is coming from — before lodgement, not after an information request.
- Where a treatment is material and the published guidance is unclear, confirm it with your BDM and note the confirmation on the file.
The strategic point
Lender policy packs get read for the headline. A new alt-doc product, a rate move, a change to a maximum LVR — those are the items that travel. The settings that actually determine whether a file services are buried in sections like 3D, expressed as floors and shadings and apportionments, and they change without a press release.
The brokers who build an advantage out of this are not the ones who memorise more percentages. They are the ones who stop quoting from memory on anything material, who know which inputs on their panel are most likely to differ between a policy pack and a calculator, and who treat a confirmation from a BDM as part of the file rather than a conversation that happened.
On a Macquarie investor file this week, the practical version of that is simple enough. The lease says $800. The guidelines say 95%. The floor says 15%. The number you give your client should come from the calculator.
Frequently asked questions
Is the 95% figure and the 5% vacancy shading two separate reductions?
No. The Macquarie broker credit guidelines describe counting 95% of gross rental income as representing a 5% shading for vacancy. They are the same cut. The separate reduction is the expense floor, set at a minimum of 15% of gross rental income.
Why do the credit guidelines and the calculator guidance show different percentages?
That is not something we can resolve from the published documents. The credit guidelines are Version 15.0, last updated 22 October 2026, and set out 95% with a 15% expense floor. The broker help pages for the serviceability calculator describe 75% being considered with shading applied automatically and a minimum 20% expense allowance, and carry no published date. Both are Macquarie documents. The safe course is to run the current calculator and confirm the treatment with your BDM.
Does the 15% expense floor replace my client’s actual expenses?
It is a floor, so it sets the minimum assumption. The guidelines state that a floor of 15% of gross rental income will be applied to investment property expenses. Where verified actual expenses on the property are higher than that, the higher figure is the relevant one.
How is rent split where a property is jointly owned?
The guidelines count rental income in line with each borrower’s percentage ownership of the property. The calculator guidance similarly directs that rental income be apportioned to each applicant by ownership percentage.
What changes in the ApplyOnline liabilities section?
Broker Daily reports that from 26 October brokers must record for each liability whether it is partially cleared, fully cleared or unchanged, give the new limit and balance for partially cleared liabilities, state how cleared liabilities will be paid out — loan funds, sale proceeds or the customer’s own funds — and include all liabilities. As a single-outlet report, confirm the detail with Macquarie or your aggregator.
Lender policy moves faster than anyone’s memory of it
The Broker Times tracks the policy settings that decide whether a file services — not just the ones that make headlines.
Interactive · For broker use
Rental Income Reality Check
See how much of a client’s gross rent reaches servicing once the shading and the expense floor are both applied.
This is an illustration, not a lender assessment. It applies the published settings from the Macquarie broker credit guidelines (Version 15.0, last updated 22 October 2026) to a figure you enter. It is not a serviceability calculation, it does not produce a borrowing capacity, and it must not be used in place of the lender’s own calculator or quoted to a client as a lender outcome.
The guidelines apply a floor of 15%. Entering less than 15% will be lifted to the floor.
Liabilities readiness check
Broker Daily reports that from 26 October the ApplyOnline liabilities section requires this information for every liability. Tick what you already capture before lodgement.
Lender policy changes without notice and is deal-dependent. Confirm every figure against the lender’s current policy document, its own calculator, or your BDM before relying on it. Nothing here is a lender approval, a credit decision, or advice.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator's compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC's responsible lending guidelines. Lender policy settings change without notice and are deal-dependent — confirm every figure against the lender's current policy document or your BDM before relying on it.