Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: Advertised Rents Hit a Record $675 While Vacancy Rose to 1.5%. On AFG Align’s Guidelines, 80% of That Rent Reaches Servicing — and Proposed Rental Comes From the Valuation
The Broker Times · At a glance
A Record Rent, and the Part of It That Reaches a Servicing Calculator
September 2026 rental data, and the documented servicing mechanics that sit underneath it.
The market numbers
Rental figures: realestate.com.au Rental Report, September 2026 data, as reported by Elite Agent and Australian Broker on 9 October 2026. Cash rate: RBA media release, 29 September 2026.
Where a $675 rent lands on the file
$35,100
$28,080
$7,020
The 80% treatment is the figure in the AFG Align residential credit guidelines issued by Thinktank, version dated 17 August 2026. Shading differs by lender — check the current policy document.
Which rent number counts, and who sets it
Rental statement under 6 weeks old, tenancy agreement, or a private lease plus 3 months of bank statements or a Cotality Estimated Rental Report.
Taken from the valuation. Short or long form: the rental assessment inside the valuation.
On an AVM or electronic valuer review, an agent appraisal above the top of the estimated rental range is referred to Head of Credit for acceptance at the top of the range.
Steps 1 to 3 describe the AFG Align residential credit guidelines issued by Thinktank, version dated 17 August 2026. Other lenders set their own evidence rules and ceilings.
The capitals, by median rent and vacancy
| Capital | Median rent | Annual growth | Vacancy |
|---|---|---|---|
| Sydney | $800 | 6.7% | 1.7% |
| Perth | $750 | 8.7% | 0.9% |
| Darwin | $740 | 13.8% | — |
| Brisbane | $700 | 7.7% | 1.1% |
| Canberra | $635 | — | — |
| Adelaide | $630 | 5% | 1% |
| Melbourne | $600 | 5.3% | 1.9% |
| Hobart | $600 | — | 0.9% |
realestate.com.au Rental Report, September 2026 data, as reported by Elite Agent and Australian Broker on 9 October 2026. Em dashes mark figures not stated in those reports.
The takeaway
A record advertised rent is a market number. The number on an investor file is a shaded figure drawn from a valuation or an estimated rental range — so the gap worth managing is between what the selling agent quotes and what the valuer will support.
Advertised Rents Hit a Record $675 While Vacancy Rose to 1.5%
On AFG Align’s guidelines, 80% of that rent reaches servicing — and proposed rental comes from the valuation, not the letting agent.
The short version: Two rental-market numbers landed in the same week and they pull in opposite directions — a record advertised rent and the loosest vacancy rate since early 2022. Neither is the number that decides an investor file. That number is set further down the chain, by a shading percentage and a valuer’s rental assessment.
1. What the September rental data actually said
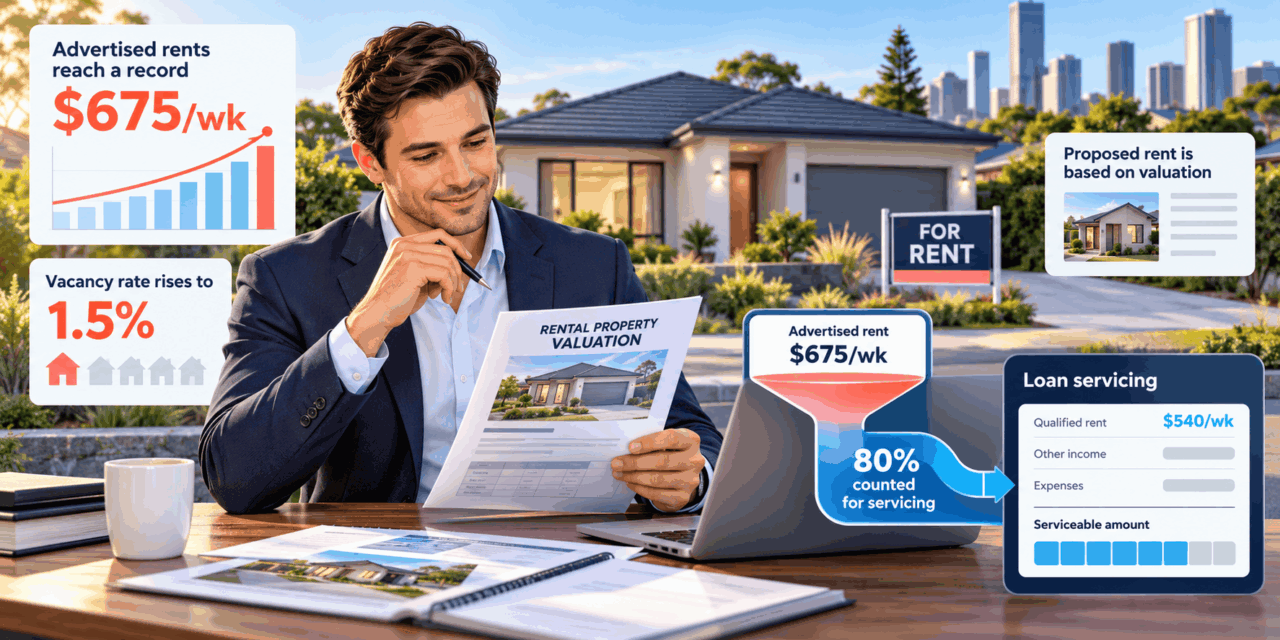
The national median advertised rent reached $675 a week in September — a record — according to the realestate.com.au Rental Report for September 2026, reported by Australian Broker and Elite Agent on 9 October. That is up 1.5% over the September quarter and 5.5% over the year, which Elite Agent put at roughly $1,820 a year more than September 2025.
The headline hides a split. Capital-city medians sat at $700 a week, up 1.4% for the quarter and 7.7% for the year. Regional medians held flat at $600, up 3.4% annually. Megan Lieu, senior economic analyst at realestate.com.au, summarised it this way: “Annual growth in regional rents is softening, while the reverse is happening in capital cities.”
By capital, Elite Agent reported Sydney at $800 a week (flat for the quarter, up 6.7% annually), Perth at $750 and up 8.7%, Darwin at $740 with the strongest annual growth at 13.8%, Brisbane and the capital-city median together at $700, Canberra at $635 and down 0.8% for the quarter, Adelaide at $630, and Melbourne and Hobart at $600.
The second number matters more for how those rents behave from here. The national vacancy rate rose to 1.5% — its highest since February 2022, per Elite Agent; Australian Broker reported the same move as a lift from 1.3% and the highest level in more than four years. Across the two reports, the capital-level readings were Perth and Hobart at 0.9%, Adelaide at 1%, Brisbane at 1.1%, Sydney at 1.7% and Melbourne at 1.9% — Elite Agent described Hobart’s as at or below 1%. Australian Broker also reported quarterly rent growth had slowed from 2.3% in the June quarter to 1.5% in September.
Those figures land on top of a cash rate the Reserve Bank lifted by 25 basis points to 4.60% on 29 September, in a decision its own media release records as unanimous. The Board said “inflation remains elevated and some of the upside risks flagged in August are materialising,” and listed a downturn in housing prices among the risks it is watching. Separately, Australian Broker reported Cotality had dwelling values down 1.1% nationally in September and 5.2% below their March peak.
The broker-relevant read: rents are at a record but decelerating, vacancy is loosening from a very tight base, values are falling and the assessment rate has gone up. An investor client hears “record rents.” The file hears something quieter.
2. Why a record rent is not a record borrowing capacity
Rental income does not go into a servicing calculator at face value. It goes in shaded, and the shading is set in the credit guidelines, not by the market.
Take one documented example. The AFG Align residential credit guidelines issued by Thinktank, version dated 17 August 2026, list rental income from an existing residential rental at 80% used in servicing. NDIS rental income is listed at 70%, with NDIS property not accepted as security. Rental income from commercial property is also listed at 80%, and only for third-party arm’s-length tenants. The same document notes that the scaling “allows for direct property expenses,” so there is no need to separately declare rental expenses — which is the logic behind the haircut.
Run the arithmetic on the national median. A property let at $675 a week is $35,100 a year gross. At 80%, $28,080 is what the assessment sees, and $7,020 a year is withheld before anything else in the calculator has been touched. That is the part of the record that never reaches the file.
The other half of the squeeze is the rate the debt is assessed at. The same guidelines set the new-loan assessment rate at the higher of the floor assessment rate, listed as currently 5.50%, or the actual loan rate plus a 2% buffer. Existing residential and commercial mortgages are assessed the same way. Credit cards are loaded at 3.8% of the limit each month. Living expenses are taken as the higher of what the borrower declares or the Household Expenditure Measure. The net servicing ratio has to come in above 1.00 times.
There is one documented relief valve worth knowing, and it is narrow. The guidelines allow a 1% buffer instead of 2% on the new loan where the borrower has clean credit history, the loan payment is like-for-like with no principal-and-interest to interest-only switching, there is no debt consolidation, cash out is capped at $20,000, and the new loan payment is lower than the existing one. Standard buffers still apply to every other existing loan. That is a retention-and-repricing tool, not a capacity tool.
A note on the 80%
That figure belongs to the AFG Align guidelines issued by Thinktank and to no other lender. Shading percentages, evidence rules and floor rates differ across a panel, and they change. Do not carry one lender’s number onto another lender’s file — check the current policy document or your BDM before you rely on any of it.
3. Proposed rental: the valuer decides, not the agent
This is the part that quietly kills investor pre-approvals, and it is the part a record median rent makes worse rather than better.
On a purchase, there is no rental statement yet. The AFG Align guidelines direct that proposed rental be taken from the valuation rental figure. Where a short-form or long-form valuation is obtained, that means the rental assessment inside the valuation. Where the security is valued by AVM or electronic valuer review, a real estate agent appraisal is accepted only when it sits within the range provided by the Cotality Estimated Rental Report. And if the agent’s appraisal comes in above the top of that range, the guidelines say to refer to Head of Credit for acceptance at the top of the range.
Read that again with the market in mind. Advertised rents are at a record and still rising in the capitals. Estimated rental ranges are built off observed data. In a market where asking rents have been running ahead, an enthusiastic agent appraisal is more likely, not less, to sit above the top of an estimated range — and the documented outcome is a credit referral and, at best, the top of the range rather than the appraisal.
The cost is small per week and real per file. Suppose an agent appraises a purchase at $700 a week and the estimated rental range tops out at $660. The appraisal figure, shaded at 80%, is $29,120 of assessed income. The top of the range, shaded the same way, is $27,456. The $40-a-week gap is $1,664 a year of assessed income. As a rough order of magnitude — at the 5.50% floor rate over a 30-year principal-and-interest term, income considered in isolation — that is in the region of $24,000 of debt. The full 20% shading step on the same $700 a week is about $106,000 on the same crude basis.
Treat those loan figures as indicative only. A real assessment nets tax, applies the Household Expenditure Measure, loads existing debts at buffered rates and tests the whole position against a net servicing ratio, so it will not move in a straight line with one income input. The income arithmetic, though, is exact: 52 weeks at the assessed weekly figure, shaded.
The practical consequence is a sequencing decision. If the valuation type is going to determine whose rental number counts, that is worth knowing before a pre-approval is issued on an agent’s appraisal and before a client bids. The guidelines also list the panel valuers available in Valex — Opteon, WBP Group, Knight Frank, Acumentis and HTW — and note that any request to go outside the panel is at the lender’s discretion.
4. The evidence trail on an existing rental
For a property already let, the AFG Align guidelines accept a rental statement less than six weeks old, a tenancy agreement, or a private lease agreement supported by three months of bank statements or a Cotality Estimated Rental Report. Short-stay income has its own path: AirBnB income requires six months of bank statements confirming rental deposits. Where 100% of the debt is to be allocated, the guidelines permit 100% of the income where ownership is 50% or more. Where a lease evidences the tenant paying certain outgoings, verified outgoings can be added to rental income in servicing.
Different lenders document different lists. Bank of Sydney’s broker credit policy guide, in a version dated 1 September 2026, asks for at least one of: a current lease agreement for an existing property; proof of rental receipts from bank records or statements; a rental valuation or a letter from a real estate agent confirming expected rental; rental statements from a managing agent; a rental valuation from a valuer where the rental property is being taken as security; or a tax return no more than six months old confirming declared rental income. That document carries its own caution on its face — the bank describes it as a guide only, not a full version of its home loan policy, and says it is not to be relied upon as the bank’s current policy.
That caveat is the right posture for all of it. These are the documented positions in two guidelines read this week. They are the starting point for a conversation with a credit team, not a substitute for one.
5. The number brokers should be watching is 1.5%
The record rent is a backward-looking number. The vacancy rate is the forward-looking one, and at 1.5% nationally it is the loosest reading since February 2022 on Elite Agent’s account of the report.
That is still a tight rental market by any historical standard, and the capital-level spread matters more than the national figure: at around 0.9% in Perth and Hobart and 1% in Adelaide, a landlord is not short of applicants. At 1.7% in Sydney and 1.9% in Melbourne, re-letting risk is a different conversation. Lieu also noted that “despite vacancies being slightly lower in regional areas, the improvement in available rentals has been larger.”
For a broker, the relevance is not forecasting. It is that the shading percentage is a fixed allowance applied to a variable reality. An 80% treatment is a standing assumption about vacancy, letting fees, management fees and maintenance. When vacancy was 1.3% nationally and asking rents were climbing 2.3% a quarter, that allowance was comfortable. At 1.5% and 1.5%, it is less comfortable — not unsafe, but less comfortable — and the direction of travel is the thing to put in front of a client who is treating gross rent as income.
6. What this changes in the client conversation
Investor clients are reading the same headlines. The useful move is not to argue with the number but to show where it goes.
Three framings are doing the work at the moment. First, gross rent is not assessed income — a documented 80% treatment means a fifth of the rent is already set aside for the costs of owning the thing. Second, on a purchase the rent that counts is the one in the valuation or inside an estimated rental range, not the one the selling agent quotes in the campaign. Third, a rising assessment rate works on the whole debt position, while a rising rent works on one line of income, so the two do not offset each other evenly.
The compliance dimension is the ordinary one, and worth stating plainly. The Best Interest Duty and the responsible lending obligations under the National Consumer Credit Protection Act 2009 sit over any recommendation, and ASIC’s guidance is the reference point for how those obligations are met in practice. The AFG Align guidelines put the principle in their own words: the serviceability calculator outputs “serve as a guide only,” and responsible lending obligations require that a broker not provide credit assistance where a loan is unsuitable, with the broker’s own assessment of the applicant’s financial position based on the enquiries made. A pre-approval built on a rental figure that a valuation later contradicts is a file worth documenting carefully. This article is general information; your licensee or compliance adviser is the right source on what your own obligations require.
7. What to review on your investor files this week
- Pull your live investor pre-approvals and identify which ones were assessed on an agent’s rental appraisal rather than a rental figure in a valuation.
- For each of those, find out the valuation type that will be used at full application. An AVM or electronic valuer review is the scenario where an estimated rental range becomes the ceiling.
- Confirm the shading percentage your target lender applies to residential, commercial and short-stay rental income, from its current policy document rather than from memory or from another lender’s file.
- Check the age of your rental evidence. A rental statement with a six-week currency rule will go stale in the middle of a slow approval.
- Re-test any pre-approval issued before 29 September against the current assessment rate, given the cash rate moved to 4.60% that day.
- Flag short-stay files early. A six-month bank-statement requirement is not something to discover in the week before finance is due.
- Write the rental assumption into your file notes — the figure used, where it came from, and what you told the client about it.
Key takeaways
- The realestate.com.au Rental Report for September put the national median advertised rent at a record $675 a week, up 1.5% for the quarter and 5.5% for the year, with the national vacancy rate at 1.5%.
- The AFG Align residential credit guidelines issued by Thinktank (version 17 August 2026) list existing residential rental income at 80% used in servicing, and NDIS rental income at 70%. Those figures are that document’s, and shading differs by lender.
- On the same guidelines, proposed rental comes from the valuation; with an AVM or electronic valuer review, an agent appraisal above the top of the Cotality Estimated Rental Report range is referred to Head of Credit for acceptance at the top of the range.
- Those guidelines set the new-loan assessment rate at the higher of a 5.50% floor or the actual rate plus 2%, with a narrow 1% buffer available on tightly conditioned like-for-like refinances.
- The RBA lifted the cash rate to 4.60% on 29 September, so pre-approvals issued before that date are worth re-testing.
Frequently asked
Breaking news for modern brokers
Lender policy moves, regulator activity and the market data that actually lands on your files.
Broker tool
Rental Income Shading Explorer
Enter a weekly rent and see what the documented shading leaves behind, plus the evidence that policy asks for.
The ceiling field is for a proposed rental: enter the top of the valuer’s assessment or estimated rental range. If your figure sits above it, the tool shows what the policy ceiling does to the assessed income.
Used in servicing Withheld by shading
Evidence the policy asks for
Shading percentages and evidence rules in this tool are taken from the AFG Align residential credit guidelines issued by Thinktank, version dated 17 August 2026, and apply to that policy only. Other lenders differ. The “rough debt it supports” figure is a crude illustration — the assessed income treated in isolation, at a 5.50% floor assessment rate over a 30-year principal-and-interest term. It is not a servicing calculator: a real assessment nets tax, applies the Household Expenditure Measure, loads existing debts at buffered rates and tests a net servicing ratio. Confirm every figure against the lender’s current policy before relying on it.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Lender policy figures quoted here are drawn from the specific policy documents and versions named in the text and may have changed since publication — confirm them against the lender’s current policy or your BDM before relying on them. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.