Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: The Average Family Contribution to a Deposit Rose to $71,000. On Macquarie Bank’s Policy, a Gift Only Counts as Genuine Savings After Three Months
The Broker Times · Deposit Evidence
Family Money Is Now Structural. Lender Policy Still Sorts It Into Hard Categories.
What brokers reported to Macquarie’s 2026 survey, and where the genuine savings test actually bites.
What brokers are reporting
Does it count as genuine savings?
A gift, held 3+ months
Gifts and inheritance are listed as unacceptable genuine savings unless the amount has been held for three months or more. Season it and it counts. Written confirmation from the donor is required, including that the funds are not repayable.
A family loan
“Any form of loan (even if held within applicants’ bank account for 3 or more months)” is not genuine savings. Time does not cure it — and the repayment terms feed into servicing as a commitment.
Own savings, 3+ months
Funds held or accumulated in a personal savings account or term deposit for three or more months, verified against source documents such as bank statements.
FHOG, projected savings, rent-to-deposit plans
The First Home Owners’ Grant, “projected savings, savings plans and/or rental purchase plans of any type”, and business account funds absent evidence of personal saving, are all excluded.
Threshold: on the policy cited, where LVR exceeds 85%, “5% of purchase price is required to be evidenced as genuine savings.” Below that threshold the test may not apply at all. This is one lender’s current policy — every panel lender differs.
The sequence that saves the file
- Ask at the first appointmentNot “is family helping?” but “how much, when, and is it a gift or a loan?”
- Start the seasoning clockIf a gift is coming and the lender wants three months, name a transfer date now.
- Pull the guarantor’s credit file firstOn the policy cited, four or more guarantor-related enquiries require the analyst to decline.
- Book the independent adviceGuarantors need independent legal and financial advice. Treat it as lead time, not a signature.
- Note the policy version and dateRecord which lender, which version, what form the money took, and what you told the client.
The takeaway
None of this is hard to manage. All of it is expensive to discover late. The gift-or-loan question asked at appointment one, with a transfer date attached, is worth more to the client than a sharper rate — it is what gets the deal through the finance clause.
Sources: Survey figures as reported by The Adviser, 30 September 2026, from Macquarie Equity Research’s 2026 Mortgage Broker Survey. Policy wording from Macquarie Bank Residential Home Loans Credit Guidelines v14.1, updated 10 September 2026. Cash rate from the RBA Monetary Policy Board statement, 29 September 2026. General information only — confirm current policy with the lender and your licensee.
Loan Tips · Deposit Structuring
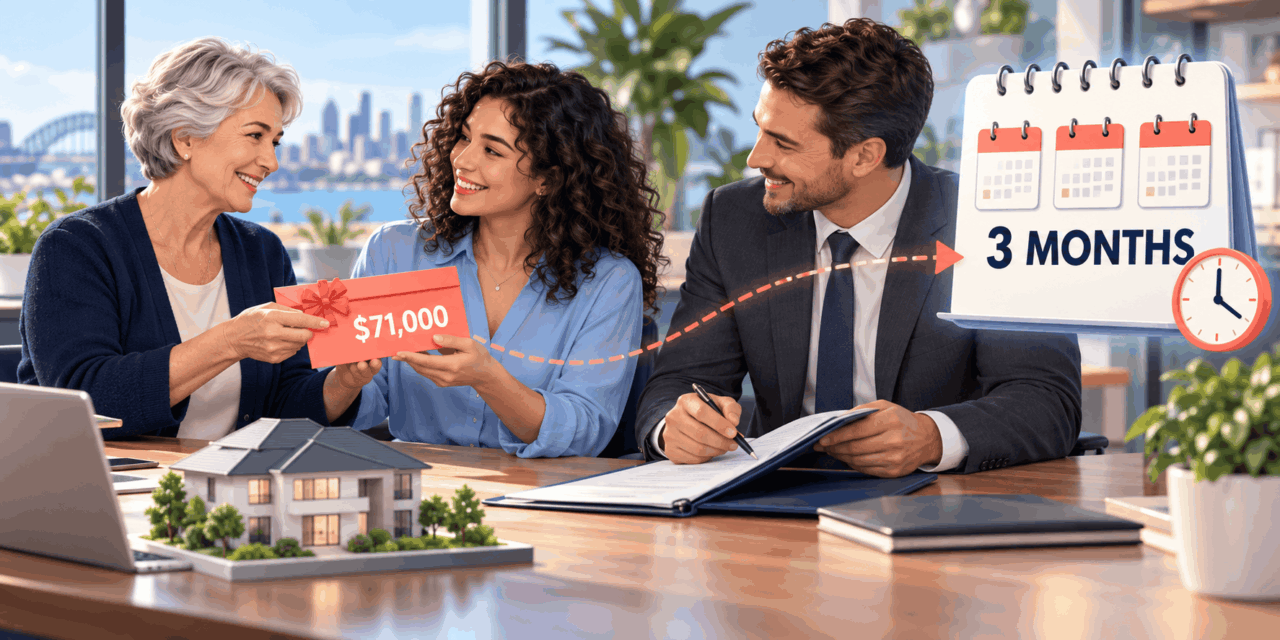
The Average Family Contribution to a Deposit Rose to $71,000. On Macquarie’s Policy, a Gift Only Counts as Genuine Savings After Three Months
Family money has become a structural part of the first-home deposit. Lender policy still sorts it into categories with hard edges — and the difference between a gift and a loan decides the file.
The deposit has quietly become the hardest part of a first-home file, and increasingly it is not the client’s money.
Brokers responding to Macquarie’s 2026 Mortgage Broker Survey reported that the average cash contribution from family to a client’s purchase rose to about $71,000, up from roughly $64,000 a year earlier, according to The Adviser‘s report of the research on 30 September. In New South Wales the average sat near $92,000 — around 50 per cent above the other states — and in Western Australia it climbed from about $33,000 to $58,000. On the survey’s numbers, 15 per cent of borrowers received a cash gift or a loan from family, slightly up on 2025, and 11 per cent had a family guarantor.
Those figures landed the day after the Reserve Bank lifted the cash rate target to 4.60 per cent on 29 September, its fourth increase of 2026, in a decision the Monetary Policy Board recorded as unanimous. Capacity is tightening at the same time that the deposit is getting larger in dollar terms. Family money is what is closing the gap.
Which moves the problem onto your file. Not the arithmetic — the evidence. The same $71,000 can be a complete deposit or a declined application depending on what form it arrived in and how long it has been sitting in the account.
Two datasets, measuring two different things
It is worth separating the numbers before building anything on them, because two sets have been reported within a month of each other and they are not interchangeable.
The Macquarie figures above come from Macquarie Equity Research’s annual survey of brokers, reported by The Adviser. They describe what brokers are seeing in current purchases — a flow measure, from the broker’s side of the desk.
Separately, Finder’s 2026 Home Loan Report, published on 8 September, found that 30 per cent of Australians — about 1.8 million people — had received financial help from family to buy a home. Within that, 11 per cent had received a deposit contribution, 6 per cent had a family member act as guarantor, 5 per cent had their entire deposit covered, 5 per cent received help with ongoing repayments, and 8 per cent had the home paid for outright. Finder’s categories overlap and do not sum to 30 per cent.
That is a stock measure across the whole adult population and across many years of purchases. It is a much larger number than Macquarie’s because it is counting something much broader. Adding the two together, or quoting the 30 per cent as if it described this year’s buyers, would overstate the position considerably. Both are useful; they answer different questions.
On sourcing: the Macquarie survey figures sit behind a paywall in a single trade outlet, and the underlying research is equity analysis rather than a public release. Treat them as that outlet’s reporting of a broker survey, which is how they are presented here.
Where the file actually breaks: gift versus loan
Here is the part worth getting precise about, because it is where files die late.
Macquarie Bank’s Residential Home Loans Credit Guidelines — version 14.1, last updated 10 September 2026, and public — set out the lender’s position plainly. Where the LVR exceeds 85 per cent, “5% of purchase price is required to be evidenced as genuine savings.” Acceptable sources include “funds held or accumulated in a personal savings account or term deposit for 3 or more months,” and savings “must be verified against source documents such as bank statements.”
The guidelines then list what does not count. Among the unacceptable forms: the First Home Owners’ Grant; “projected savings, savings plans and/or rental purchase plans of any type”; funds held in a business account unless evidence shows they were personally saved over the required period; and, critically for this discussion, two separate entries that brokers routinely collapse into one.
The first is “gifts and inheritance,” which the guidelines treat as unacceptable genuine savings unless the amount has been held for three months or more. Season it, and it counts.
The second is “any form of loan (even if held within applicants’ bank account for 3 or more months).” A family loan never becomes genuine savings. Time does not cure it.
That distinction is the single highest-value thing to establish at the first appointment. A $71,000 transfer from a parent is either a gift or a loan, and the answer changes the product set, the timeline and the servicing calculation. The documentation differs too. For a gift, the guidelines require that “written confirmation must be received from the donor of the funds,” confirming the amount and that the funds are not repayable. For a family loan, written confirmation is required covering the amount, any conditions, and the repayment terms — and those repayment terms then have to be fed into servicing as a commitment.
One caveat that matters: this is one lender’s policy, cited because it is public, versioned and current. Every lender on your panel will treat seasoning periods, gift letters and non-genuine savings differently, and some will not require genuine savings at all below certain LVRs. Do not generalise Macquarie’s settings across your panel. Pull the current policy for the lender you are actually recommending.
The timing arithmetic nobody budgets for
Consider a straightforward file. A first-home buyer purchasing at $780,000 with a 10 per cent deposit, so an LVR of 90 per cent — above the 85 per cent threshold at which the genuine savings test bites. Five per cent of the purchase price is $39,000, and that is the portion that has to be evidenced as genuine savings.
The same file, two transfer dates
The client has $26,000 of her own, accumulated over two years. Her parents are contributing $55,000 as a gift. Total deposit is comfortably there. On the arithmetic, the file is strong.
But if the parents transfer the money in the week the contract is signed, the gifted portion has not been held for three months. Her own $26,000 is genuine savings; the $55,000 is not yet. She is $13,000 short on the genuine savings test, with a 30-day finance clause running. The options at that point are all worse than the option she had eight weeks earlier: a different lender with different settings, a higher-LVR product priced accordingly, a longer finance clause she has to negotiate after the fact, or a deal that falls over.
Move the same gift three months earlier and none of that happens. The intervention costs nothing except asking the question early and telling the client’s parents a date.
This is the conversation that is now worth having at the pre-approval stage rather than the application stage: not “will your family help?” but “when, how much, and is it a gift or a loan?” If the answer is a gift, the seasoning clock is a thing you can start immediately. If it is a loan, you are placing a different deal entirely.
One further timing trap sits in the government schemes. ASIC’s guidance notes at RG 273.68 that obtaining a scheme’s full benefit “may require steps to be taken before the broker starts providing credit assistance,” and Example 2 following that paragraph describes a first-home buyer who made voluntary superannuation contributions under the First Home Super Saver Scheme to build a deposit. Where a client is using a scheme, the sequencing can matter before you begin giving credit assistance at all — another reason the deposit conversation belongs at the front of the engagement.
The guarantor route has its own hidden decline
Eleven per cent of borrowers in the Macquarie survey had a family guarantor, and when seasoning is the obstacle, a security guarantee is often the structure brokers reach for instead. It carries its own policy edges.
Macquarie’s guidelines require that borrowers and guarantors be natural persons, and that any mortgagor be documented as either a borrower or a guarantor. Independent legal and financial advice is required for guarantors, with a narrow exception: directors of company borrowers do not need independent financial advice, but they still need independent legal advice. Credit reports are obtained for all guarantors.
Then there is a provision that catches experienced brokers off guard. Guarantor-related credit enquiries and any linked servicing guarantees must be investigated, and on Macquarie’s policy, four or more of those enquiries require the credit analyst to decline the application.
The parents writing $92,000 cheques in Sydney are frequently the same parents who have already guaranteed an older child. A guarantor with a history of guarantees is not a neutral input.
Check the guarantor’s file before you build the structure around them, not after. The independent advice requirement is also a timeline item, not a formality. A guarantor who needs to see their own solicitor and their own financial adviser is a guarantor who needs calendar time, and in a family spread across three cities that is not a same-week exercise.
What the best interests duty does and does not settle here
Brokers reasonably ask where this sits against their obligations, and the honest answer is that the duty addresses less of it than you might expect.
The best interests obligation sits in Part 3-5A of the National Consumer Credit Protection Act 2009, at sections 158LA and 158LE, and ASIC’s Regulatory Guide 273 frames it at RG 273.16 as a requirement that brokers “must act in the best interests of each individual consumer to whom credit assistance is provided.” The duty attaches to the consumer you are providing credit assistance to.
RG 273 mentions guarantors only in passing. At RG 273.60 it observes that lender policies on acceptance of a guarantee can influence whether certain products are available to a consumer — that is, the guarantee is treated as a product-availability input rather than as a separate relationship with its own duty. The guide does not address family gifts as a category at all, and genuine savings does not appear in it.
So the seasoning rules, the gift letters and the guarantor advice requirements are lender and mortgage-insurer policy, not a statutory test you can read off the Act. That does not make them less binding on your file; it means the governance around them is set by your licensee’s process rather than by ASIC’s guidance. If your file notes do not record which lender’s policy you checked, on what date, and what the client’s family contribution actually was, there is nothing to show later.
This is general information, not compliance advice. How your licensee expects family contributions, guarantor structures and seasoning evidence to be documented is a question for your aggregator’s compliance team, and for independent legal advice where a guarantee is involved.
One adjacent point, briefly. Where a broker forms the view that an older family member is being pressed into a contribution or a guarantee they do not want, that is a different conversation with a different process behind it — the MFAA released a recognise, respond and refer framework for exactly that situation, which The Broker Times covered separately. It is not what most of these files are. But the volume of money now moving between generations means the question comes up more often than it used to, and it should be referred, not resolved at the desk.
Key takeaways
- Brokers reported the average family cash contribution to a purchase at about $71,000, up from roughly $64,000 — near $92,000 in NSW — as reported by The Adviser from Macquarie’s 2026 broker survey.
- On the Macquarie Bank policy cited, a gift can count as genuine savings once held three months or more. A family loan never counts, whatever the holding period.
- That policy applies the genuine savings test above 85 per cent LVR, requiring 5 per cent of the purchase price to be evidenced. Panel lenders differ — check the one you are recommending.
- Guarantor structures have their own edges: independent legal and financial advice is required, and on that policy four or more guarantor-related credit enquiries require a decline.
- Genuine savings and gift seasoning are lender and insurer policy. RG 273 does not address family gifts, and genuine savings does not appear in it — so the process governance is your licensee’s, not ASIC’s.
What to review this week
A short pass over your live pipeline will tell you where the exposure is:
- Every pre-approval above 85 per cent LVR. Identify which ones are relying on a family contribution that has not yet landed, and get the expected date in writing.
- Ask the gift-or-loan question explicitly. Not “are your parents helping” — “is this a gift you will never repay, or a loan with terms?” Record the answer. The two place differently.
- Start the seasoning clock early. Where a gift is coming and the lender requires three months, the cheapest intervention available to you is telling the family a date three months before the contract.
- Pull the guarantor’s credit file first. Before you design a guarantee structure, check for prior guarantees and the enquiry trail. On some policies a handful of guarantor enquiries is an automatic decline.
- Book the independent advice. Treat legal and financial advice for guarantors as a scheduling dependency with real lead time, not a signature to chase at settlement.
- Check the actual policy document, by version and date. Seasoning periods, acceptable gift evidence and genuine savings thresholds differ by lender and change without much fanfare.
- Write the file note. Which lender’s policy, which version, what the contribution was, what form it took, and what you told the client about timing.
What to watch next
Two things are worth monitoring. The first is whether lenders move on seasoning. If family contributions keep growing as a share of deposits while prices soften, a three-month rule applied to a gift starts looking less like prudent policy and more like friction on a cohort lenders want. Any lender that shortens its seasoning period, or accepts a gift letter in place of seasoning, buys itself a placement advantage immediately.
The second is the data itself. If next year’s broker survey shows the average family contribution rising again from $71,000 while the share of borrowers receiving one stays near 15 per cent, that tells you the help is concentrating rather than spreading — fewer families able to help, writing larger cheques. That is a different market to segment for than one where family support is becoming broadly available, and it would change which clients are worth a long-dated nurture sequence.
The practical takeaway
The deposit is no longer just a savings problem for your clients, and it stopped being purely an arithmetic problem for you. On the reported numbers, family money is now a structural component of the first-home deposit, averaging around $71,000 and considerably more in Sydney. Lender policy, meanwhile, still sorts that money into categories with hard edges: a gift that counts after three months, a loan that never counts and hits servicing, a guarantor whose own enquiry history can decline the file.
None of that is difficult to manage. All of it is expensive to discover late. The broker who asks the gift-or-loan question at the first appointment, and names a date for the transfer, is doing something worth more to the client than a sharper rate — making sure the deal survives the finance clause.
Frequently asked
It is not a test set out in ASIC’s best interests duty guidance — genuine savings does not appear in RG 273, and the guide does not address family gifts as a category. It is a lender and mortgage-insurer policy construct. It still governs whether your file is approved, but the process around it is set by your licensee rather than by ASIC’s guidance. Confirm your own obligations with your compliance team.
Not on the Macquarie Bank policy cited here, which excludes “any form of loan (even if held within applicants’ bank account for 3 or more months).” Holding it longer does not change its character. A gift is different — gifts and inheritance are acceptable on that policy once held three months or more. Other lenders set this differently, so check the policy for the lender you are recommending.
On the policy cited, written confirmation must be received from the donor, stating the amount and confirming the funds are not repayable. If the money is instead a loan from family, written confirmation is required covering the amount, any conditions and the repayment terms — and those terms then need to be treated as a commitment in servicing.
RG 273.16 frames the duty as owed to each individual consumer to whom credit assistance is provided, and RG 273 mentions guarantors only at RG 273.60, where lender acceptance of a guarantee is treated as something that can influence product availability. The guide does not set out a separate duty to a guarantor. How your licensee wants guarantor dealings documented is a question for them, and guarantors need independent legal advice in their own right.
Because they measure different populations. Finder’s 2026 Home Loan Report counts the share of all Australians who have ever received family help to buy a home, across many years of purchases. The Macquarie survey figures describe what brokers are seeing in current purchases. The two are not additive, and the 30 per cent should not be read as describing this year’s buyers.
Breaking news for modern brokers
Lender policy shifts, regulator moves and the numbers that land on your files — twice daily.
More at The Broker Times →Sources: Survey figures as reported by The Adviser, “Over 80% of brokers report investor inquiry plunge,” 30 September 2026, drawing on Macquarie Equity Research’s 2026 Mortgage Broker Survey. Policy wording from Macquarie Bank, Residential Home Loans Credit Guidelines v14.1, updated 10 September 2026. Family-help data from Finder’s 2026 Home Loan Report, reported 8 September 2026. Cash rate from the Reserve Bank of Australia, Statement by the Monetary Policy Board, 29 September 2026. Best interests duty references from ASIC Regulatory Guide 273 and Part 3-5A of the National Consumer Credit Protection Act 2009.
Broker Tool · Interactive
Deposit Evidence Checker: Will This Money Count as Genuine Savings?
Based on the Macquarie Bank Residential Home Loans Credit Guidelines v14.1 (10 September 2026). One lender’s policy — always confirm the one you are recommending.
Choose a funding source, a holding period and an LVR band
This tool reproduces the genuine savings treatment set out in one lender’s published credit guidelines. It is a prompt for checking the policy that applies to your file — not a credit decision, and not a substitute for the lender’s current policy document.
Lender policy changes without much fanfare. The Broker Times tracks the ones that land on your files.
Read more at The Broker Times →General information only. Seasoning periods, acceptable gift evidence and genuine savings thresholds differ between lenders and change over time. Confirm the current policy with the lender you are recommending, and your documentation obligations with your licensee or compliance adviser.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.