The two gaps police have described
The accountant’s letter
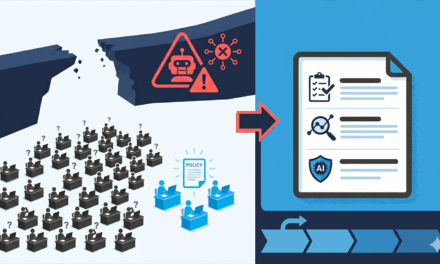
Police allege false documents were produced inside an accounting practice. A check that only confirms the firm exists would not catch that.
RG 209 Table 1 lists an accountant’s statement as one of several income sources for self-employed consumers.
The contract the bank couldn’t see
Police allege vendors paid money back to buyers under a “deed of rebate” that was “not visible to the bank”, which inflated the headline price.
Police, as reported by the ABC
What RG 209 says

Police Charged Three at an Accounting Firm Over False Loan Documents. The Accountant’s Letter on Your Self-Employed File Needs a Second Source
On 9 September 2026, NSW Police arrested the director of a Bankstown accounting firm and two others who worked there. Each is charged with 17 counts of making false documents to obtain a financial advantage, plus four counts relating to accounting documents. Police say the three are linked to $16.2 million, $15.6 million and $14.5 million in allegedly fraudulent loans respectively. The arrests bring the number of people charged under Strike Force Myddleton to 33. None of the charges has been tested in court, and everyone charged is presumed innocent.
For brokers, the useful part of this story isn’t the size of the alleged fraud. It’s where police say the paperwork came from. When a self-employed client can’t show a clean PAYG income trail, the file usually rests on documents from the client’s accountant. And according to police, in at least one case banks were also unable to see part of the purchase contract. This article looks at both gaps, what ASIC’s responsible lending guidance says about relying on other people’s documents, and what you can check on your own files this week.
What police have alleged so far
A joint release published by the Australian Taxation Office on 10 September says NSW Police’s Financial Crimes Squad charged five more people between 2 and 9 September. The strike force was set up in January 2024 to investigate “ghost car” vehicle finance fraud. According to the release, the investigation later found alleged “large-scale personal, business and home loan fraud against multiple financial institutions”. The NSW Crime Commission has restrained about $95 million in assets.
The three people from the accounting firm are a 46-year-old director, a 34-year-old accountant and a 28-year-old woman. The director and the accountant were refused bail. The ATO release says the 28-year-old was granted conditional bail to appear at Bankstown Local Court on 8 October 2026. (Accountants Daily reported that she was refused bail. We have used the primary release.) Two other women, arrested on 2 September and described in trade coverage as money mules, are linked to a further $5.3 million and $13 million in allegedly fraudulent loans.
Detective Superintendent Gordon Arbinja, Commander of the Financial Crimes Squad, said in the release: “The alleged conduct uncovered during this phase of the investigation shows a deliberate and coordinated effort to exploit loan systems, misuse personal information and conceal the proceeds of crime through professional channels.”
Two regulators outside lending also commented. Pennie Snowden, ATO Acting Deputy Commissioner, said: “Professional facilitators who assist others to commit financial crime undermine confidence in Australia’s tax and superannuation systems and create an unfair advantage over the vast majority of taxpayers and advisers who do the right thing.” Tax Practitioners Board Chair Peter de Cure AM said: “Any agent found to be involved in the facilitation of fraud or other criminal activity can expect the TPB to take strong regulatory action.”
The ABC reported police as saying the syndicate took banks for up to $600 million in fraudulent loans. It also quoted Detective Superintendent Arbinja’s estimate that about $500 million of that was written by the four major banks. These are police estimates, not court findings. The broker channel has already featured in the case: in May, The Adviser reported that a 35-year-old finance broker had been charged under the same strike force.
Blind spot one: the accountant’s letter
Self-employed files are built on documents from other people. Tax returns, notices of assessment, BAS, business financial statements and, for many lenders, a letter from the client’s accountant confirming income or business position. That accountant’s letter works partly as an endorsement. A registered professional has put their name to the numbers.
ASIC’s own guidance accepts this document. Table 1 of Regulatory Guide 209 lists “a statement from the consumer’s accountant setting out details of the consumer’s actual or likely income levels” as an information source for self-employed consumers. It sits alongside recent tax returns, BAS, financial statements for related entities, business account statements and bank statements showing incoming payments. Example 8 in RG 209 describes a lender considering “written advice from Sam’s accountant that confirms the profit and loss position of her business” together with business bank accounts, tax assessments and BAS.
Look at how that example is put together. The accountant’s advice is one input among several. It doesn’t replace the others. The Myddleton allegations show why that matters. If police are right that people inside an accounting practice produced false documents, then a letter on that firm’s letterhead would pass every check that only confirms the firm exists.
What a register check does and doesn’t tell you
The Tax Practitioners Board’s public register shows a practitioner’s registration number, status (registered, unregistered, suspended or terminated), any conditions on registration, and any sanctions or termination decisions. It’s a worthwhile check, and cheap to add to your file notes. But a register search confirms that a practitioner is registered and whether the TPB has acted against them. It can’t tell you whether the figures in a particular letter are true. A practitioner under investigation, with no sanction recorded yet, will still show as registered. So the register check is a starting point. It doesn’t verify the income.
Blind spot two: the contract the lender couldn’t see
The second allegation affects purchase files. According to the ABC’s report, police allege the syndicate bought properties, mostly in Sydney’s eastern suburbs, “at highly inflated prices, then have the vendor return a portion of the funds to the buyer through a legal contract called a deed of rebate”. Police told the ABC that “in all cases, the deed was not visible to the bank”. Detective Superintendent Arbinja told the ABC that some properties sold at prices 40 to 50 per cent above similar properties.
These details come from the ABC’s reporting of police statements, not from the joint release. They are allegations. The point for brokers is the structure. A side agreement that sends money back to the buyer means the headline price overstates what the buyer really paid. That inflates the security value the loan is sized against and can hide where the deposit came from. A valuation that relies on comparable sales won’t necessarily catch it, especially in a thin, high-value market.
Most brokers will never see a deed of rebate. But the same issue turns up in ordinary files: cash-back incentives, rebates on off-the-plan purchases, and “furniture packages” or rental guarantees that change what the buyer is really paying. How each lender treats these depends on its credit policy. Check your panel’s requirements rather than assuming.
What RG 209 says about relying on other people’s documents
Under the National Credit Act, you must make reasonable inquiries about the consumer’s requirements and objectives and their financial situation, and take reasonable steps to verify that financial situation. RG 209.43 sets out these obligations and cites s117 for credit assistance providers. Several passages in RG 209 apply directly to Myddleton-type risk.
- RG 209.48 says the verification requirement exists because application information may not be reliable. One listed reason is “deliberate fraud by the consumer or a person who is assisting the consumer to make an application”.
- RG 209.50 says it is “not sufficient merely to rely on other persons providing true information about their financial situation”, and that if other information raises doubt, “it is reasonable to take steps to verify the true situation”.
- RG 209.129 says a broker’s obligations are separate from the lender’s. The broker must make inquiries, verification steps and assessments “to meet its own obligations to reduce the chance it will suggest or assist with an unsuitable credit product; not merely to support the lender’s ability to make a final assessment”.
RG 209.130 to 209.134 are written for lenders (“As the lender, you need to form your own view…”). They give examples of circumstances that should raise doubt about information from third parties, including suspected misconduct by the third party and false information in earlier applications. Where doubt exists, RG 209.133 suggests confirming the information from a separate source. It gives the example of a transaction statement to test whether a payslip is genuine. That passage isn’t addressed to brokers, but the approach carries over well to broker file practice. It is also the approach your lenders apply when they review what you send them.
Your Best Interest Duty under s158LA of the Act also matters. A loan sized on inflated income or an overstated purchase price is unlikely to be in the client’s interests, even when the client is the one pushing for it. Talk to your licensee or aggregator’s compliance team about how these obligations apply to your own processes. This article is general information, not a statement of what your licence conditions require.
Practical steps: tighten the file, not the relationship
Most accountants are exactly who they say they are, and most self-employed clients are honest. The aim is to make sure no single document carries the whole file. Here is a working checklist for self-employed and purchase files.
For income that depends on an accountant
- Reconcile against the tax office’s own records. Where available, compare the accountant’s figures with the ATO notice of assessment and lodged BAS. If a letter shows income the assessment doesn’t support, you need an explanation before lodgement.
- Test the story against the bank statements. Business account turnover should roughly match declared revenue. Owner drawings should roughly match stated personal income.
- Find the accountant’s contact details yourself. Don’t rely on the letterhead phone number or email. Look the practice up independently before you make any verification call.
- Record a TPB register check for the practitioner who signed, and note the date.
- Notice when one practice keeps appearing. If the same accountant appears on several unrelated clients’ files, especially with similar letter templates or round numbers, raise it with your compliance team.
For purchase files
- Read the whole contract bundle, including special conditions and annexures, and ask the client in writing whether any other agreement with the vendor, agent or developer exists.
- Sense-check the price. If the price sits well above recent comparable sales, find out why before the valuation comes back, not after.
- Trace the deposit. Genuine savings should show up over time in statements. A sudden lump sum should have a documented source.
- Disclose incentives according to each lender’s policy, and keep a record that you did.
If something doesn’t add up
Don’t lodge on a document you have reason to doubt, and don’t accuse the client or their accountant. Record what you found, escalate to your licensee under its procedures, and follow its guidance on next steps. A referral or a suspicion is not a finding of wrongdoing. Your file notes should record facts, not conclusions.
What to watch next
The 28-year-old is due before Bankstown Local Court on 8 October, and the two women charged on 2 September are due at Liverpool and Fairfield Local Courts on 14 October. The NSW Crime Commission has said it will start work to identify and seize assets. Expect lenders to look harder at self-employed income evidence and purchase-price anomalies in the months ahead, whether or not they say so publicly. Brokers whose files already show the cross-checks described above will feel that scrutiny least.
Across Strike Force Myddleton, the allegations have involved bank insiders, a broker and now an accounting practice. For brokers, the takeaway is that a document from a registered professional still needs checking against at least one other source before a file relies on it.
- Police allege that three people from one Bankstown accounting firm made false documents linked to allegedly fraudulent loans. The charges are untested, and everyone charged is presumed innocent.
- Police also allege that vendor rebates under a “deed of rebate” were not visible to banks and inflated purchase prices (as reported by the ABC).
- RG 209 lists an accountant’s statement as one of several self-employed income sources and says relying solely on others to provide true information is not sufficient.
- A TPB register check confirms a practitioner’s registration status and any recorded sanctions. It doesn’t verify the figures in a letter.
- Check the accountant’s figures against ATO records and bank statements, and ask in writing about side agreements on purchases. Escalate doubts to your licensee.
FAQ
Were any brokers charged in the September arrests?
The 10 September release describes three people from an accounting firm and two women arrested on 2 September. None is described as a broker. The Adviser reported in May 2026 that a 35-year-old finance broker had been charged under the same strike force.
Can I still accept an accountant’s letter?
RG 209 Table 1 lists an accountant’s statement as one possible source for self-employed income. What matters is whether your verification steps are reasonable in the circumstances, which usually means checking the letter against other sources. Confirm your approach with your licensee.
Does a TPB register search verify the accountant?
It confirms registration status, conditions and any recorded sanctions or terminations. It cannot confirm that the figures in a particular document are true.
What should I do if I suspect a document is false?
Don’t lodge on it, and don’t accuse anyone. Record the facts and escalate to your licensee under its procedures.
Broker-first news and analysis, every day.
More at TheBrokerTimes →Sources: ATO joint media release, “Accountants and money mules charged for alleged involvement in multi-million dollar fraud scheme” (10 Sep 2026); ABC News (10 Sep 2026); The Adviser (10 Sep 2026; 28 May 2026); Accountants Daily (10 Sep 2026); ASIC Regulatory Guide 209; Tax Practitioners Board, “Help with using the TPB Register”.
Add the checks you ticked to your file-note template, and confirm the approach with your licensee or aggregator’s compliance team.
More compliance coverage →Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator's compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC's responsible lending guidelines.