Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: ASIC Had No Concerns With the Recorded Reasons on 74.1% of Files Where the Extra Cost Was Under $1,000. Above $20,000 It Was 34.1%
The rationale gets weaker as the cost gap gets wider
How ASIC graded the recorded reasons on 551 broker files where the recommended loan was not the cheapest on the shortlist, sorted by projected five-year cost to the client.
The scope
What ASIC reviewed
Review period 1 April 2023 to 31 March 2025.
The gradient
ASIC’s grade on the recorded reasons, by five-year cost gap
Each bar is 100% of the files in that cost band. Percentages shown are ASIC’s.
The criteria
What each grade means — in ASIC’s words
These grades assess the record, not whether the loan was suitable.
The documented rationale supporting the recommended loan was clear and reasonable.
The rationale was specific to the consumer’s circumstances, but could have better demonstrated how or why the recommended loan was in their best interests.
There was no documented rationale, or the rationale was generic, inconsistent or poor quality.
The mechanics
Four findings that explain the pattern
No measure of size
ASIC found “a general absence of metrics” estimating the cost difference between the compared and recommended loans. Exception reports flagged whether the cheapest was chosen, not by how much.
Two groups had no cost view
Two of the eight aggregator groups could not readily extract total-cost data from their comparison software, leaving no risk-based monitoring on loan costs except manual review.
Discounts entered by hand
A negotiated discount must be keyed into the comparison tool manually — but is not needed there for the client to receive it. The file’s cost comparison can stop matching the deal.
Features instead of reasons
Among the risk patterns ASIC listed: reasons “limited to the features of each product”, generic or non-specific reasons, and a lack of detailed cost comparison notes.
And the new line
Where AI sits in the duty
ASIC, REP 840: “Outputs from any decision tools or AI agents should be explainable and documented (including the relevant data used to create them).” And: “Brokers and licensees are still responsible for the quality of the credit assistance they provide, regardless of the technology they use.” Nothing in the report restricts using these tools — it sets the governance expectation around them.
Read it carefully
This is not a pass rate for the broker channel. Both of ASIC’s 800-file samples were chosen precisely because they were the files most likely to need justification — loans that were not the cheapest shortlisted, or where only one option was presented. ASIC also looked only at product data and the reasons recorded in aggregator systems, not other documents held on file.
The takeaway
Sort your own non-cheapest files by the size of the cost gap, not by whether a flag fired. The biggest gaps are where ASIC found the thinnest reasoning.
The file notes get thinner exactly where the money gets bigger
ASIC graded the recorded reasoning on 551 broker files where the recommended loan was not the cheapest on the shortlist. The grade fell as the cost gap rose — and the regulator has now put AI-assisted tools inside the same documentation expectation.
In this article
- The number most of the coverage missed
- What ASIC actually looked at
- What “concerns” meant in ASIC’s own words
- Why the gradient probably exists
- The comparison-tool blind spot
- Where AI now sits in the duty
- What RG 273 actually asks you to keep
- The rationale test: what to review this week
- What to watch next
The short version. ASIC’s first full review of the best interests duty found that where the recommended loan was projected to cost a client under $1,000 more than the cheapest option compared, the regulator had no concerns with the recorded reasoning on 74.1% of files. Where it was projected to cost more than $20,000 more, that fell to 34.1%. The grade deteriorated as the stakes rose.
The number most of the coverage missed
ASIC Report 840 landed on 13 October, and the figure that travelled fastest was this one: seven of the eight aggregator groups reviewed reported that their brokers did not recommend the lowest-cost loan in more than 20% of cases over the two-year period.
It is a striking number, and it is also close to meaningless on its own. ASIC says so itself. The report notes that licensees were calculating loan costs in different ways — some over the full 25 to 30-year term, some over five years to reflect how long borrowers actually stay — and that in some cases the loan with the higher total cost was probably the cheaper loan over the short term, because of introductory rates that later reverted. Some aggregators reported on their credit representatives only; others included brokers operating under their own licence. It is not a like-for-like figure, and recommending something other than the cheapest loan is not a breach of anything.
The number that should change your Monday sits in Appendix 2.
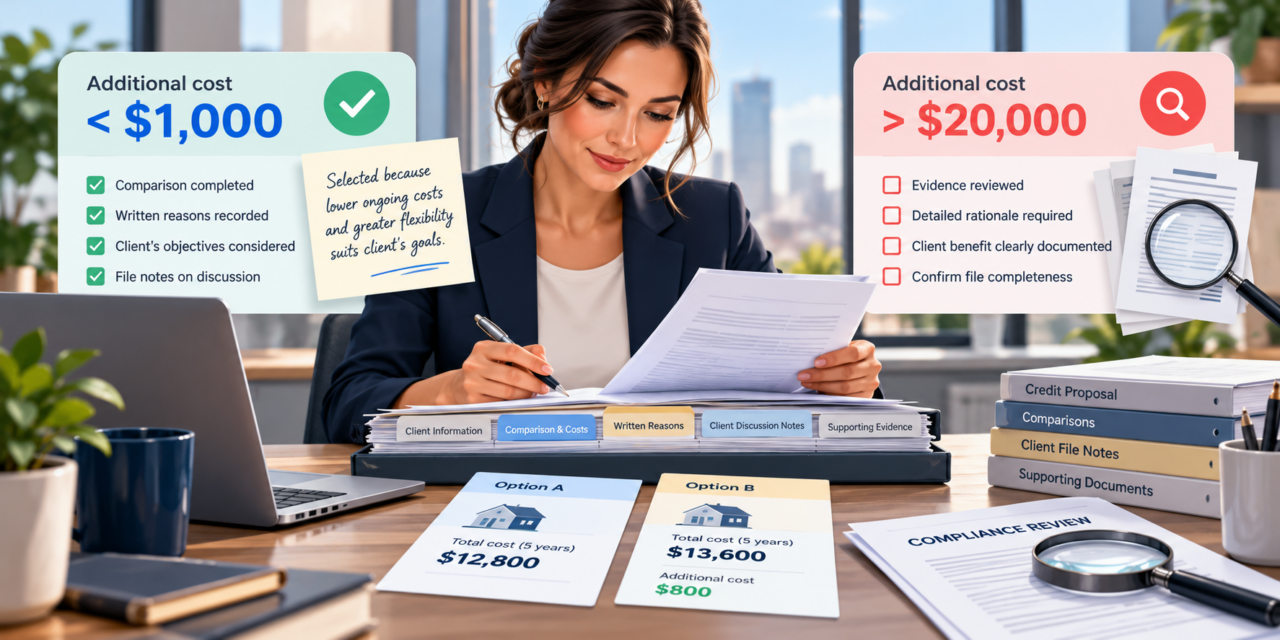
ASIC took the files where the broker recommended a loan that was not the cheapest on their own shortlist, calculated how much extra that recommendation was projected to cost the client over five years, and then graded the rationale the broker had recorded. Sorted by the size of the cost gap, the results form a clean gradient in the wrong direction.
| Five-year cost gap | No concerns | Some concerns | Most concerns | Files |
|---|---|---|---|---|
| Under $1,000 | 74.1% | 18.4% | 7.5% | 147 |
| $1,000 – $5,000 | 66.8% | 21.3% | 11.9% | 244 |
| $5,000 – $20,000 | 45.4% | 29.4% | 25.2% | 119 |
| More than $20,000 | 34.1% | 22.0% | 43.9% | 41 |
Read the first and last columns together. As the projected cost to the client rose from under $1,000 to over $20,000, the share of files ASIC was comfortable with fell from 74.1% to 34.1% — and the share in the most serious grade rose from 7.5% to 43.9%, close to six times higher.
Put plainly: the files that needed the most justification carried the least.
What ASIC actually looked at
Scope matters here, both for how much weight to give the finding and for how not to overstate it.
ASIC reviewed 13 credit licensees making up eight large aggregator groups — together responsible for roughly two-thirds of all broker representatives in Australia. The groups named in the report are AFG, Connective, Finsure and Beagle, Lendi Group (Aussie), Loan Market Group, Mortgage Choice and Smartline, Outsource Financial, and Vow Financial and Yellow Brick Road. The data covered 1 April 2023 to 31 March 2025. ASIC also reviewed more than 7,000 documents, including policies, training material, file review methodologies and assurance reports.
The file-level work covered 1,600 loan recommendations, split into two deliberately targeted samples of 800: files where the recommended loan was not the cheapest of the shortlisted options, and files where the broker presented only one option at the end of the shortlisting process. ASIC is explicit that these were recommendations which, under RG 273 and the licensees’ own policies, brokers should be supporting with evidence.
Do not read this as a pass rate for the broker channel. Both samples were chosen precisely because they were the files most likely to need justification. ASIC also notes it looked only at the product data and the reasons recorded in the aggregators’ systems, and did not consider other information or documents that may have been held on file. Several licensees made exactly that point in response — that the real reasons may have been recorded elsewhere in their records.
That caveat cuts both ways. If the reasoning lives somewhere the licensee’s system cannot surface, it also cannot be monitored, reported or produced quickly when someone asks for it.
What “concerns” meant in ASIC’s own words
The grades are not a judgement about whether the loan was wrong. They are a judgement about the record. ASIC set out its criteria in Appendix 1, and the distinction is worth knowing before anyone quotes the 65.9% figure at you:
- No concerns — the documented rationale supporting the recommended loan was clear and reasonable.
- Some concerns — the rationale was specific to the consumer’s circumstances, but could have better demonstrated how or why the recommended loan was in their best interests, even though it was not the cheapest.
- Most concerns — there was no documented rationale at all, or the rationale was generic, inconsistent or poor quality.
So the middle band is a quality gap, not a failure: the broker wrote something real about that client and stopped a sentence or two short. The top band is the one with teeth. On 43.9% of the files where the recommendation was projected to cost the client more than $20,000, ASIC found no recorded rationale, or one that was generic, inconsistent or poor quality.
Elsewhere in the report, ASIC lists the specific patterns that put brokers at risk of being unable to demonstrate compliance: failing to record reasons at all; generic or non-specific reasons; a lack of detailed cost comparison notes; documented reasons limited to the features of each product; a claim that the recommended loan was the lowest cost option when the compared data suggested otherwise; and reasoning that was inconsistent with the client’s stated preferences.
That fourth one catches a lot of otherwise careful files. “Client required an offset account” is a product feature. It is not a reason why this client, with this balance and this behaviour, is better off paying more for it.
Why the gradient probably exists
ASIC does not offer an explanation for the pattern, and neither should anyone else with certainty. But two mechanics in the report point at it.
The first is that nothing in the workflow was escalating by stakes. ASIC found licensees used exception reports that flagged when the lowest-cost option was not selected — a binary trigger. What was largely missing was the size of the gap. In the report’s words, there was “a general absence of metrics that estimated the difference in cost of the compared loans and the recommended loan.” Two of the eight groups could not readily extract total-cost data from their comparison software at all, leaving them no portfolio view of cost differences and no way to do risk-based monitoring on loan costs except by manual review.
If the system treats a $400 gap and a $40,000 gap identically, the broker gets no signal that this file is the one to slow down on. The note that satisfies a minimum character count passes either way.
The second is that large cost gaps tend to arise in the hardest files. A client with non-standard income, a tight servicing position, or a settlement deadline gets placed with the lender that can actually do the deal, and the cheapest lender on the panel often cannot. The reasoning in the broker’s head is usually sound. It is also the most complex to write down, and it gets written down at the end of the longest, messiest files.
Which is the uncomfortable reading of this table: the gradient is probably not evidence of brokers behaving worse on big-ticket files. It is evidence of the documentation burden rising faster than the documentation habit, with no system prompt to close the gap.
The comparison-tool blind spot
One finding in the report deserves singling out, because it can make your file say something untrue without anyone intending it.
ASIC found that some licensees could provide interest rate data for the products compared, but were not always sure whether that rate was the one the client was actually expected to receive. The reason is mechanical: a broker has to manually enter any discount agreed with a lender for it to show up in the comparison tool — but the tool’s data does not need to be updated for the client to receive the discount.
So the client gets the sharper rate, and the tool keeps ranking on the undiscounted one. Your file then records a cost comparison that no longer matches the deal. ASIC’s action item for licensees is to ensure their systems capture accurate information relevant to loan recommendations, “including lender discounts, promotional offers, cashbacks and lender timeframes for processing loan applications.”
Until the systems do that, the manual entry is the control. If you negotiate a discount and do not feed it back into the tool, the record of your own reasoning is wrong in a way that is very hard to explain two years later.
Where AI now sits in the duty
The second thread in REP 840 is the one with the longer tail. ASIC used this report to state, for the first time in a broking-specific document, how it expects AI-assisted tools to sit inside the best interests duty.
The tone is not hostile. ASIC says it is “encouraged to see the credit industry and service providers exploring the development and rollout of tools that aim to identify better products and savings opportunities for consumers,” and that if adopted more widely such tools “may help licensees demonstrate how consumers are being provided with suitable products, including lower-cost options where appropriate, consistent with RG 273.55.” On policy-matching specifically, the report notes the potential for AI to compare lender policies to determine eligibility, observing that understanding and interpreting lender policy is “a core part of the service that mortgage brokers offer,” and that ASIC is interested in how such tools might help the industry “not only work smarter and faster, but also to more confidently and accurately identify loans that meet consumers’ needs.”
Then it draws the line. Pointing back to its earlier Report 798 on AI governance, ASIC writes:
Outputs from any decision tools or AI agents should be explainable and documented (including the relevant data used to create them).
ASIC, Report 840, ‘Governance and accountability’
And immediately after:
Brokers and licensees are still responsible for the quality of the credit assistance they provide, regardless of the technology they use.
ASIC, Report 840, ‘Governance and accountability’
Read those two sentences against the table at the top of this article and the practical consequence is clear enough. If a tool shortlists, ranks or filters the products you then recommend from, the tool’s output has become part of your reasoning — and ASIC expects that output, and the data behind it, to be explainable and on the file. A rationale that amounts to “the system ranked it first” is a generic reason wearing better clothes, and generic reasons are what put 43.9% of the big-gap files in the bottom grade.
The flip side is the opportunity. The same documentation burden that is being handled badly on complex files is exactly the burden a well-governed tool can carry — provided it records the inputs, the point-in-time data and the logic, rather than producing a tidy paragraph with nothing underneath it.
What RG 273 actually asks you to keep
None of the obligations changed on 13 October. The best interests duty sits in the National Credit Act — section 158LA for licensees, with section 158LE(1) placing the duty on representatives directly and section 158LE(2) requiring licensees to take reasonable steps to ensure their representatives comply. RG 273, published in June 2020, is still the guidance ASIC assesses you against, and its record-keeping section is more specific than most brokers remember.
RG 273.165 says ASIC generally expects records to include “the options and ultimate recommendation you gave and the reasons why (including a detailed description of your decision-making process).” RG 273.167 lists the forms those records can take, and explicitly includes “outputs of product and feature comparison tools, including graphical presentations and calculators” — which is where your software’s shortlist lives.
Two further paragraphs are worth re-reading in light of this report. RG 273.169 says taking notes contemporaneously “may help you to accurately capture your thinking and reasoning at each relevant point in time,” and that “just drafting notes and creating records at the end of the process may not be as effective.” RG 273.170 suggests a concise narrative summary connecting the various records — one that is “evidence based and supported by contemporaneous records.”
And on cost, RG 273.54 is the sentence the whole table turns on: “Any situation where a higher cost loan is recommended will need to be supported by evidence demonstrating why that recommendation is in the consumer’s best interests.” RG 273.56 is the balance — the product with the lowest interest rate is not necessarily the lowest cost option, and features such as an offset or redraw may save certain clients a considerable amount. The guidance has always allowed you to recommend the dearer loan. It has always asked you to show the working.
The rationale test: what to review this week
This is a report about records, so the useful response is a records exercise. It does not need a project.
1. Sort your own files by cost gap, not by exception flag
Pull the files from the last six months where you did not recommend the cheapest option on your shortlist, and rank them by the projected cost difference rather than treating them as one pile. ASIC’s own action item for licensees is to be able to “readily identify loan recommendations with limited or no recorded rationale and that are not for the cheapest loan compared.” Doing it at your own desk first is cheaper than being asked.
2. Apply ASIC’s three grades to your top five
Take the five largest gaps and grade them honestly against the criteria above. Is the rationale clear and reasonable? Is it specific to that client, or specific to the product? Would a reader who had never met the client understand why the extra cost bought them something worth having?
3. Convert every feature statement into a client statement
“Offset account required” becomes “client holds approximately $X in savings and is paid monthly, so the offset is expected to reduce interest by roughly $Y a year, which exceeds the $Z annual package fee.” Same decision, documented. That is the difference between the middle grade and the top one.
4. Check your discount hygiene
Where you negotiated pricing, confirm the discounted rate was entered back into the comparison tool. If it was not, the cost comparison sitting on your file does not describe the loan your client took.
5. Write down what your tools did
If an AI assistant, policy-matching engine or servicing calculator shaped the shortlist, record which tool, what you asked it, the date, and the client-specific data you gave it. Keep the output. ASIC’s expectation is that the output and the data behind it are explainable and documented — which is a filing habit, not a technology project.
6. Ask your aggregator one question
Can their system show you the projected total cost difference between the loan you recommended and the cheapest loan you compared? Two of the eight groups ASIC reviewed could not extract that data readily. If yours cannot, your own notes are carrying the entire evidentiary load, and you should know that before someone tells you.
What to watch next
ASIC says it expects mortgage broker licensees to consider the findings and close the gaps in their own practices, and that all licensees — not just the thirteen reviewed — should use the report to assess whether they need to change. In practice that means the controls will arrive through your aggregator: more mandatory fields, cost-gap thresholds that trigger a second look, and quality-assurance sampling weighted toward the expensive files rather than spread evenly.
Brokers who tighten the rationale on their own big-gap files now will find those controls a formality. Brokers who do not will meet them as friction at exactly the moment a complex deal is trying to settle.
Key takeaways
- In ASIC’s sample, the share of files with no concerns about the recorded rationale fell from 74.1% where the projected five-year cost gap was under $1,000 to 34.1% where it exceeded $20,000.
- In that top band, 43.9% of files had no documented rationale, or one ASIC assessed as generic, inconsistent or poor quality.
- Both samples were selected because they were the files most likely to need justification, so these proportions are not a pass rate for the broker channel.
- ASIC found a general absence of metrics measuring the size of the cost difference, and two of eight aggregator groups could not readily extract total-cost data from their comparison software.
- Discounts negotiated with a lender must be entered into the comparison tool manually, but are not needed there for the client to receive them — so a file’s cost comparison can quietly stop matching the deal.
- ASIC now expects outputs from decision tools and AI agents to be “explainable and documented,” and says brokers and licensees remain responsible for the quality of credit assistance regardless of the technology used.
Does recommending a loan that is not the cheapest breach the best interests duty?
No. RG 273.56 states that the product with the lowest interest rate is not necessarily the lowest cost option, and RG 273.57 notes cost is not the only relevant matter. What RG 273.54 requires is that a higher-cost recommendation be supported by evidence demonstrating why it is in the client’s best interests. The issue ASIC identified was the quality of that evidence, not the choice of loan. This is general information — check your own obligations with your licensee or compliance adviser.
Does the 65.9% figure mean two-thirds of those brokers did something wrong?
No. That combines ASIC’s “some concerns” and “most concerns” grades in the above-$20,000 band. “Some concerns” means the rationale was specific to the client but could have better demonstrated how or why the loan was in their best interests. Only the “most concerns” grade — 43.9% in that band — covers files with no rationale or a generic, inconsistent or poor-quality one. The grades assess the record, not whether the loan was suitable.
Can I use AI tools in my process after this report?
Nothing in REP 840 restricts their use, and ASIC describes itself as encouraged by tools that help identify better products and savings opportunities for consumers. The expectation it sets is governance: outputs from decision tools or AI agents should be explainable and documented, including the relevant data used to create them, and responsibility for the quality of the credit assistance stays with the broker and licensee regardless of the technology. Your licensee may have its own policy on approved tools — check before adopting one.
Is a minimum character count on the rationale field enough?
It is a control several licensees used, and ASIC records it as one of the preventative controls built into broker workflow software. But length is not the test. ASIC’s bottom grade explicitly captures rationales that are “generic, inconsistent or poor quality” — all of which can clear a character minimum comfortably.
Stay ahead of the next policy shift
The Broker Times covers lender policy, regulation and market data for Australian brokers — twice daily, no fluff.
Sources
- ASIC, Report 840: Mortgage brokers — Review of best interests duty and complaints handling practices, published 13 October 2026 (Tables 3 and 4, Appendices 1 and 2, and the sections on cost differences, preventative and reactive controls, and emerging uses of AI and automation).
- ASIC media release 26-240MR: ASIC review finds room for improvement in mortgage brokers’ best interests duty practices, 13 October 2026.
- ASIC, Regulatory Guide 273: Mortgage brokers — Best interests duty, June 2020 (RG 273.54–273.57 and RG 273.162–273.172).
- National Consumer Credit Protection Act 2009 (Cth), sections 158LA and 158LE, as described in REP 840, ‘Key regulatory obligations’.
Grade your own file note the way ASIC graded 551 of them
Pick one file where you recommended a loan that was not the cheapest option on your shortlist. Answer as the file actually reads today — not as you remember the conversation.
This tool applies ASIC’s own published evaluation criteria from REP 840 Appendix 1. It is an educational prompt for reviewing your own records — not a compliance assessment, and not a substitute for your licensee’s file review process.
Indicative grade
What to fix on this file
Nothing flagged. On ASIC’s criteria this file reads as clear and reasonable — keep the same standard on the next complex one.
Grades and wording drawn from ASIC Report 840, Appendix 1 (‘Evaluation criteria for sample loan recommendations’), published 13 October 2026. General information only — confirm your obligations with your licensee or compliance adviser.
Run this on your five largest cost gaps, not your five most recent files. That is where ASIC found the thinnest reasoning.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.