Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
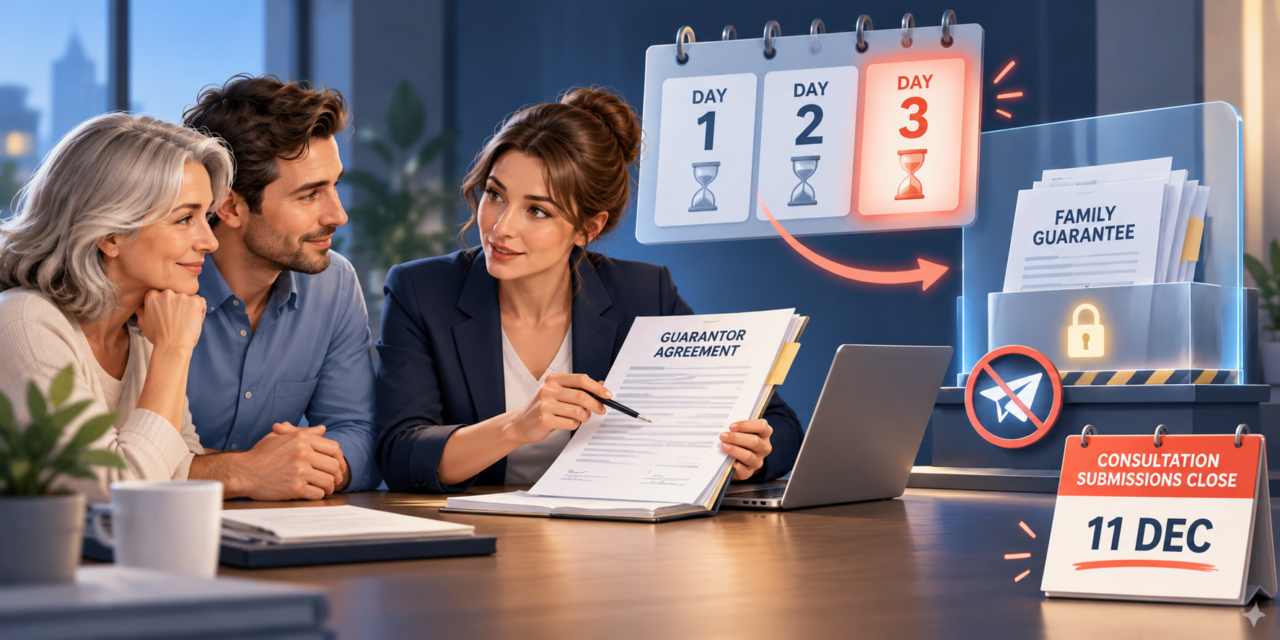
This audio version covers: A Subscribing Bank Can’t Accept Your Client’s Family Guarantee Until the Third Day, and Can’t Send the Documents Through the Borrower. Submissions on Whether to Change That Close 11 December
The Broker Times · Compliance Briefing
The Guarantee File, Under the 2025 Banking Code
What a subscribing bank must do before it can accept your client’s family guarantee — and the review now asking whether it is enough.
The numbers on the file
The sequence a subscribing bank follows
- The information pack goes to the guarantorProposed loan contract, list of related security contracts, any related credit report, any credit-related insurance the bank holds, borrower financials given in the previous two years for the guaranteed loan, and any statement of account for a period in which a demand was made in the last two years.Code paragraphs 103–105
- Not via the borrowerThe bank gives the guarantee documents directly to the guarantor or their representative. It will not give them to the borrower, or to someone acting for the borrower, to arrange for the guarantor to sign.Code paragraph 107
- A meeting, borrower absentReasonable steps to hold a meeting with the guarantor — in person, video, phone or other means — and reasonable steps to ensure the borrower is not, to the bank’s knowledge, present. On video, the bank also checks the borrower is not visible on screen.Code paragraphs 109–110
- The clock runsThe bank will not accept the guarantee until the third day after that information was given.Code paragraph 112
- Signing, borrower absentIf the bank attends the signing, it ensures the guarantor signs without the borrower present or visible on screen.Code paragraph 114
Where the steps switch off
Meeting not required
- The guarantor or their lawyer confirms independent legal advice on the guarantee
- Director, Sole Director, Trustee, Partnership, Commercial Asset Financing or Vehicle Asset Financing Guarantor
- The guarantor is accepting an extension of the guarantee
Third-day wait not required
- The guarantor or their lawyer confirms independent legal advice on the guarantee
- An extension of the guarantee
- Sole Director, Trustee, Partnership, Commercial Asset Financing or Vehicle Asset Financing Guarantor
- A Director Guarantor who chooses to sign and deliver earlier — the bank will not influence that choice
Who is a small business under the Code
Limb 1 — Turnover
- Annual turnover of less than $10 million in the previous financial year, for the business or its business group
Limb 2 — Headcount
- Fewer than 100 full-time equivalent employees
Limb 3 — Total debt
- Less than $5 million total debt to all credit providers — lifted from $3 million for the 2025 Code
The takeaway
Where your lender subscribes to the Banking Code and the borrower is an individual or a Code-defined small business, the guarantee has a procedural floor with a timing consequence: a third-day wait, a borrower-absent meeting, and documents that cannot travel through your borrower. Independent legal advice is the lever that removes the wait. The review of these provisions is accepting submissions until 11 December 2026.
Sources: 2025 Banking Code of Practice (ASIC-approved 27 June 2024, effective 28 February 2025), Part B6 and the Code’s definition of Small Business; 2026 Banking Code Review Consultation Paper, 16 October 2026. Paragraph numbers are the Code’s own. General information only — not compliance advice.
Compliance · Banking Code Review
A Subscribing Bank Can’t Accept Your Client’s Family Guarantee Until the Third Day, and Can’t Send the Documents Through the Borrower. Submissions on Whether to Change That Close 11 December
Part B6 of the Banking Code has been live since 28 February 2025. It binds the lender, not you — but it sets a floor under the timeline of every guarantee-supported deal you write with an ABA member, and the independent review is taking submissions on it until 11 December.
In this article
- What the review is, and the dates that matter
- Part B6: the sequence that sits under your settlement date
- The exceptions are where the planning actually happens
- The statutory floor that applies whoever the lender is
- Check whether your lender is a subscriber at all
- The small business test decides more than you think
- What this has to do with best interests duty
- The broker checklist, and how to make a submission
On 16 October 2026 the independent review of the Banking Code of Practice released its consultation paper. Question 22 runs to a single line: “Are any changes required to the Code to improve banks’ approaches when accepting and/or enforcing guarantees for loans?”
It reads like an industry-body problem. It isn’t. The provisions behind that question have been operating since 28 February 2025, and they are the reason a parental guarantee cannot be turned around in a day.
If you have ever had a family pledge land on your desk forty-eight hours before an unconditional date and discovered the lender would not take the signed guarantee yet, you have already met paragraph 112 of the Banking Code — you just may not have known it had a number.
The Code is easy for brokers to file under “bank problem”. Its obligations are written in the bank’s voice, they bind subscribing banks rather than credit representatives, and nothing in it tells a broker what to do. But its guarantor provisions have direct consequences for whoever structured the deal: they add a minimum elapsed time between the documents going out and the guarantee being accepted, they dictate who may carry those documents, and they require a conversation held without your borrower in the room. Those are timeline facts, and they belong to you long before they belong to the bank. Submissions close on 11 December 2026.
1. What the review is, and the dates that matter
The Australian Banking Association must arrange a review of the Code at intervals of no more than five years. The last was the 2021 review by Mike Callaghan; the ABA’s response produced the version now in force, which ASIC approved on 27 June 2024 and which took effect on 28 February 2025. This review is led by Peter Kell, a former Deputy Chair of both ASIC and the ACCC. It commenced on 4 September 2026 with the release of the terms of reference, and the consultation paper followed on 16 October. The reviewer is also running a separate, concurrent review of the Banking Code Compliance Committee.
| Stage | Date |
|---|---|
| Review commenced; terms of reference released | 4 September 2026 |
| Consultation paper released | 16 October 2026 |
| Submissions on the consultation paper close | 11 December 2026 |
| Interim report released for further consultation | March 2027 |
| Submissions on the interim report close | 7 May 2027 |
| Final report provided to the ABA | by 30 June 2027 |
The Code’s stated objective is to give customers safeguards and protections not set out in law, complementing the law and in some areas setting higher standards than it. Enforcement has three parts: the Banking Code Compliance Committee monitors compliance, reports publicly on breaches and can impose sanctions; customers and small businesses can take Code-breach complaints to AFCA; and — the part brokers should register — the provisions are legally enforceable through their inclusion in customer contracts.
Why that last mechanism matters: the guarantor steps below are not a goodwill brochure. Where a bank subscribes, they are terms the customer and guarantor can enforce, and a departure is something AFCA can consider — the difference between an internal service standard and a floor you can plan a settlement around.
2. Part B6: the sequence that sits under your settlement date
Part B6 applies where an individual guarantees a loan the bank gives to another individual or to a small business, and the Code applies to that loan. Its purpose is framed plainly: the bank gives the guarantor information and follows set processes designed to help them understand the financial risks and decide whether to accept them, while the guarantor makes their own assessment and is pointed to independent legal and financial advice.
The information pack (paragraphs 103–105)
Before the guarantee can be accepted, the bank must put a defined bundle in front of the guarantor. The terms and conditions carry a prominent notice that the guarantor should seek independent legal and financial advice, can refuse to sign, faces financial risks, can limit liability, can request information about the transaction, and — where applicable — that the guarantee may cover future credit facilities and variations of the existing loan.
The bank must also disclose any notice of demand it has made on the borrower — for the guaranteed loan or any loan the borrower has or has had with it — within the previous two years, and whether an existing loan will be cancelled if the guarantee is not provided. It must hand over the proposed loan contract, a list of related security contracts, any related credit report, any credit-related insurance contract it holds, any financial accounts or statement of financial position the borrower gave it in the previous two years for the purposes of the guaranteed loan, and the latest statement of account for any period in which a demand was made in the last two years. The guarantor can reasonably request other information about the loan, though not the bank’s internal opinions. Where the loan is approved and regulated under the National Consumer Credit Protection Act, the bank must tell the guarantor they can request a copy of the not-unsuitable assessment free of charge.
The documents do not travel through your borrower (paragraph 107)
The bank gives the guarantee documents directly to the guarantor or their representative. It will not give them to the borrower, or to someone acting for the borrower, to arrange for the guarantor to sign. That closes off the oldest shortcut in a family pledge — the adult child taking the forms home to the parents over the weekend.
A meeting, with the borrower absent (paragraphs 109–110)
Before accepting the guarantee, the bank takes reasonable steps to ensure a meeting is held with the guarantor to discuss being a guarantor — in person, by video, by phone or by some other means — and reasonable steps to ensure the borrower is not, to its knowledge, present. Where the meeting is not in person, that is done by having the guarantor confirm the borrower is not present; by video, the bank also checks the borrower is not visible on screen.
The third-day rule (paragraph 112)
The bank will not accept a guarantee until the third day after the guarantor has been given the paragraph 103 to 105 information. This is the provision with the hardest edge on your file: not a cooling-off period the guarantor can waive by being keen, but a constraint on when the bank will take the document — and it runs from when the information went out, not from when the guarantor read it.
Signing and the life of the guarantee (paragraphs 114–115)
If the bank attends the signing, the guarantor signs in the borrower’s absence, with the same on-screen check by video. Then the obligations continue: within 14 days of the relevant event the bank sends the guarantor a copy of any formal demand or default notice issued to the borrower, written notice if the borrower has advised financial difficulty that has resulted in a change to their loan, and written notice if the borrower remains in default more than two months after that default notice.
The client conversation this creates: a parent guaranteeing their child’s purchase will, in the ordinary course, be told by the bank if that child later asks for hardship assistance and the loan is varied as a result. Set that expectation at the start, or own the surprise years later.
3. The exceptions are where the planning actually happens
The meeting steps and the third-day wait both have carve-outs, and they are not identical. Knowing which lever applies to which deal is the practical skill.
Paragraphs 109 and 110 — the meeting and the borrower-absent requirement — do not apply where the guarantor or their lawyer confirms the guarantor has received independent legal advice about the guarantee; where the guarantor is a Director, Commercial Asset Financing, Sole Director, Trustee, Partnership or Vehicle Asset Financing Guarantor; or where they are accepting an extension of an existing guarantee.
The third-day wait falls away on a similar but distinct list: confirmed independent legal advice; an extension; where the guarantor is a Commercial Asset Financing, Sole Director, Trustee, Partnership or Vehicle Asset Financing Guarantor; or where a Director Guarantor chooses to sign and deliver earlier — and on that last one the Code says the bank will not influence the choice.
Read those two lists side by side and the commercial consequence is clear. Independent legal advice is the single lever that switches off both the meeting requirement and the third-day wait. On a tight resi family pledge, a guarantor who sees a solicitor is not just better protected — the file also stops waiting. And on a company-and-trust commercial deal, most of these consumer-style steps were never switched on, because directors, trustees and partners sit in the carve-out.
None of that is a reason to steer a guarantor toward or away from advice to manage a timeline. It is a reason to raise the question early, while the answer can still be anyone’s choice but the calendar’s.
4. The statutory floor that applies whoever the lender is
The Code is a layer on top of the law, not a substitute for it. For guarantees over credit regulated by the National Credit Code, a separate requirement operates regardless of whether the lender subscribes to anything. Regulation 81 of the National Consumer Credit Protection Regulations 2010 provides that, for section 55 of the Code, a guarantee must contain the warning set out in Form 8 — boxed in the layout Form 8 shows, and set out immediately above and on the same page as the place where the guarantor signs, on each page where guarantors sign separately. The Banking Code points at this too: paragraph 103 requires a warning notice directly above the signing place, substantially in the form required by section 55 and detailed in Form 8.
5. Check whether your lender is a subscriber at all
This is the step most often skipped. The Banking Code binds subscribing banks — ABA members that have signed up, a list the ABA publishes, covering the majors and a long tail of others. It does not reach the non-bank sector, and customer-owned institutions operate under their own instrument, the Customer Owned Banking Code of Practice.
So the same family pledge can carry different procedural protections depending on where it is placed. At an ABA subscriber it picks up the third-day rule, the borrower-absent meeting and the document-routing restriction. At a non-bank it does not: National Credit Code requirements and the lender’s own policy still apply, and many non-banks run comparable processes, but as policy rather than a Code term enforceable through the customer contract. If a timeline turns on it, check the policy instead of assuming.
The mutual sector is on a parallel track: the Customer Owned Banking Code of Practice had its own independent review in 2025–26, conducted by Eva Scheerlinck, with an interim report on 13 May 2026 and the final report due to COBA on 30 June 2026. The MFAA made a submission to it; the interim report records its view that clearer guidance would help in situations involving joint accounts or guarantees.
6. The small business test decides more than you think
Part B5 sets out commitments on lending to small business: the factors banks consider when assessing a small business loan, notice requirements and steps before enforcing for non-payment or a non-monetary default, notice when the bank decides not to extend a loan, and requirements around appointing valuers, investigating accountants and insolvency practitioners.
Whether your client gets any of it turns on a three-limb definition. A business is a small business for the Code’s purposes if it, or its business group, had annual turnover under $10 million in the previous financial year, has fewer than 100 full-time equivalent employees, and has less than $5 million total debt to all credit providers. That debt limb excludes National Credit Code–regulated debt and does not double count debt between group members — but it does include undrawn amounts under existing loans, and any loan being applied for.
Read that last clause again. The facility you are currently writing counts toward the $5 million. A client sitting at $4.6 million of existing and undrawn limits who asks you for another $600,000 is, on the Code’s own test, outside the definition by the time the application is made — and with it goes Part B5, and the Part B6 guarantor steps that depend on the borrower being an individual or a Code-defined small business.
For the 2025 Code the debt limb was lifted from $3 million to $5 million and the definition expanded to business groups, following the 2020 Pottinger review. The ABA has said the expanded definition brings in roughly 10,000 more small businesses. The reviewer now wants to know what that change did: question 11 asks whether the Part B5 commitments are supporting banks to deal appropriately with small business customers, and question 12 asks what the impact of the revised definition has been. Commercial and asset finance brokers are among the few positioned to answer that from the file level.
Farming clients have their own part. Under Part B7 a bank will not charge default interest on a loan to a farmer whose land is in drought or subject to natural disaster — the consultation paper notes that because the Australian Government no longer makes formal drought declarations, the ABA says assistance is handled case by case. And where a farmer and a bank do not reach agreement at farm debt mediation, the bank will consent to AFCA considering a complaint that would otherwise be excluded. Question 13 asks whether those provisions are working as intended.
7. What this has to do with best interests duty
The two instruments do different jobs, and the line is worth drawing precisely. The Banking Code governs how a subscribing bank behaves toward the customer and the guarantor. The best interests duty governs your recommendation. Nothing in the Code imposes an obligation on a broker.
Where they meet is the structure you recommend and what follows from it. The procedural reality of a guarantee-supported structure — a third-day floor, a conversation the guarantor has without the borrower present, documents that cannot be routed through the borrower, ongoing notices if the borrower later strikes trouble — is part of what the client and the guarantor will live through. Recommending the structure and leaving the mechanics as a surprise is a service problem that can become a complaint. Setting them out at the point of recommendation, and recording that you did, is better file-making. How your licensee wants that evidenced is a question for your licensee: nothing here states what the best interests duty requires in a given case, and the Code’s own framing is worth borrowing — the guarantor makes their own assessment, and should consider independent legal and financial advice.
8. The broker checklist, and how to make a submission
What to review this week
- Find your live guarantee files. For each one, identify the date the guarantor was given the loan contract and the accompanying information, and confirm the earliest date the lender will accept the signed guarantee. Work the settlement date back from there, not forward from today.
- Check the lender’s status. Is it on the ABA’s signatory list, a customer-owned institution under the COBA code, or a non-bank outside both? If the timeline depends on the answer, confirm it against the lender’s own guarantor policy rather than assuming.
- Stop routing guarantee documents through the borrower. Where the bank subscribes, it will not give those documents to the borrower or to someone acting for the borrower to arrange signing. Build your process so the guarantor or their representative is the recipient.
- Raise independent legal advice early. It is the one lever that switches off both the meeting requirement and the third-day wait — and it is also the thing most likely to leave a guarantor genuinely informed. Raise it as a choice, in writing, at the point the structure is recommended.
- Diarise the guarantor conversation. The borrower cannot be present, including on screen. On a family pledge that means a separate appointment, not a corner of the one you already booked.
- Brief the guarantor on the 14-day notices. Explain that during the guarantee the bank will tell them about a demand, a prolonged default, or a hardship variation to the borrower’s loan. Better now than by letter.
- Run the small business test on commercial files. Turnover under $10 million, fewer than 100 FTE, and total debt — including undrawn limits and the facility being applied for, across the business group — under $5 million. Know which side of the line the client lands on before you tell them what protections apply.
- Document it. If you walk a client through any of the above, note it on the file. Your licensee’s process governs the form.
On the submission itself: the reviewer is accepting submissions from any interested organisation or person until 11 December 2026, via the online submission page at 2026bankingcodereview.com.au or by email to submissions@2026bankingcodereview.com.au. Short submissions are explicitly welcomed, including ones addressing only some questions. Submissions are public and published on the review website unless the submitter clearly requests confidentiality.
That last point is worth weighing before you write. The questions most open to a broker are question 22 on accepting and enforcing guarantees, and questions 11 and 12 on the small business commitments and the revised definition. A short submission describing what the third-day rule does to a real settlement timeline, or what the $5 million debt limb does to a real commercial client, is file-level evidence a reviewer cannot get from a position paper. Your aggregator or association may be preparing one too — worth asking, so your experience lands somewhere.
Key takeaways
- On an ordinary family pledge with a subscribing bank, it will not accept the guarantee until the third day after the guarantor was given the loan contract and accompanying information. That is a floor under your settlement timeline, not a courtesy.
- In the ordinary case a subscribing bank gives the guarantee documents to the guarantor or their representative, not to the borrower or anyone acting for the borrower.
- Before accepting the guarantee it takes reasonable steps to hold a meeting with the guarantor and reasonable steps to ensure the borrower is not present — including not visible on screen where the meeting is by video.
- Each of those steps has carve-outs. Confirmed independent legal advice switches off both the meeting requirement and the third-day wait, and directors, sole directors, trustees, partners and certain asset finance guarantors sit largely outside them — so check the guarantor’s category on every file.
- These are commitments on subscribing banks, not obligations on brokers. Non-banks are outside the Code and mutuals operate under the separate Customer Owned Banking Code.
- The Code’s small business debt limb counts undrawn limits and the loan being applied for. The facility you are writing can put the client outside the definition.
- Submissions to the review close 11 December 2026; the interim report follows in March 2027 and the final report goes to the ABA by 30 June 2027.
Frequently asked
Does the Banking Code impose any obligation on me as a broker?
No. The Code sets standards for how subscribing banks deal with individual customers, small business customers and guarantors. It is written as the bank’s commitments and is enforceable against the bank through its inclusion in customer contracts. Its relevance to you is practical rather than legal: it determines the lender’s process and therefore your timeline and your client’s experience.
Can the guarantor waive the three-day wait because the settlement is tight?
Not by enthusiasm alone. Paragraph 112 is a constraint on when the bank will accept the guarantee, and paragraph 113 sets out the specific circumstances in which it can be accepted earlier — confirmed independent legal advice, an extension of an existing guarantee, certain commercial and asset finance guarantor categories, and a Director Guarantor who chooses to sign and deliver earlier. Confirm the position with the lender for the particular file.
Does the borrower-absent meeting apply to a company director guaranteeing their own company’s loan?
Paragraph 111 carves out Director Guarantors, Sole Director Guarantors, Trustee Guarantors, Partnership Guarantors, Commercial Asset Financing Guarantors and Vehicle Asset Financing Guarantors from the meeting and borrower-absent steps. The Code also has specific provisions for what a Director Guarantor must be told about their right to receive the information documents. The definitions do the work here, so check the Code’s own defined terms against the actual structure.
My client is borrowing through a non-bank. What changes?
The Banking Code commitments do not reach a lender that does not subscribe to it. Statutory requirements that apply to the credit itself still do — for guarantees over National Credit Code–regulated credit, the Form 8 warning requirement in regulation 81 of the National Consumer Credit Protection Regulations 2010 operates regardless of the lender’s code status. Beyond that, the lender’s own guarantor policy governs, so check it rather than assuming the Code’s steps apply.
Is it worth a solo broker making a submission?
The reviewer has said short submissions are welcome, including ones addressing only some questions, and that they can come from any interested organisation or person. Submissions are published unless confidentiality is requested, which is worth considering if you would be describing identifiable client circumstances. Questions 11, 12 and 22 are the ones a broker is best placed to answer.
Is the review looking at AI?
Question 25 asks whether the use of artificial intelligence raises any issues that should be considered in the review. The reviewer notes the Code is broadly technology neutral and says it would be undesirable to embed technology-specific rules that may be superseded quickly, and asks whether AI issues are better dealt with through other regulatory processes, laws or industry standards. No position has been taken.
Breaking news for modern brokers
Policy shifts, lender changes and regulator moves — read in the time between appointments.
Sources consulted for this article: 2026 Banking Code Review, Consultation Paper, 16 October 2026, and accompanying media release, 16 October 2026 (2026bankingcodereview.com.au); 2025 Banking Code of Practice (ASIC-approved 27 June 2024, effective 28 February 2025), Part A, Part B5, Part B6, Part B7 and the Code’s definition of Small Business; National Consumer Credit Protection Regulations 2010 (Cth), regulation 81 and the note to it; Australian Banking Association, Banking Code of Practice page (signatory information and the stated effect of the expanded small business definition); Independent Review 2025–26 of the Customer Owned Banking Code of Practice, interim report, 13 May 2026. Paragraph numbers given are the Banking Code’s own numbering. Figures and dates are as published by those sources at the time of writing.
Broker Tool
Guarantee File Sequence Checker
Answer five questions about the file and see which Banking Code guarantor steps a subscribing bank will follow — and where the timing floor sits.
Tell the reviewer what this sequence does to a real file. Submissions close 11 December 2026.
General information only, based on the 2025 Banking Code of Practice (effective 28 February 2025) and the 2026 Banking Code Review Consultation Paper of 16 October 2026. It is not legal or compliance advice, does not account for every defined term or exception in the Code, and does not replace the lender’s own guarantor policy. Confirm the position for each file with the lender and your licensee.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.