The Broker Times · Data Snapshot
AFG Mortgage Index — September 2026 Quarter
Broker lodgements eased, but the composition of the book moved further than the volume did.
Borrower mix: where the shift actually happened
Shares are of AFG residential lodgements and do not sum to 100% — AFG reports purpose categories separately. Refinancing comparison figures as reported by Broker Daily.
Read this one carefully: majors at 70%
The Adviser reported the majors and their affiliated brands at 70% of AFG lodgement volume, against 58%, with non-majors at 30%. But AFG has newly classified Macquarie Bank as a major lender and, on the reporting available, the historical series has not been restated.
So the two numbers are not like-for-like. AFG itself cautioned against reading the jump as a straight competitive gain.
Of lodgements — the lowest in the index’s history, per Broker Daily, from 3.8% last quarter. Fixed was 38.2% in Q1 FY21–22.
Down from 25% last quarter and 24% a year earlier, per Broker Daily — consistent with the investor share easing.
$3.8bn lodged. First annual decline after 11 straight quarters of year-on-year growth.
Lodgement value by state
| State / territory | Lodged | Avg loan |
|---|---|---|
| NSW | $8.6bn | $819,286 |
| VIC | $7.8bn | $694,009 |
| QLD | $4.9bn | $703,907 |
| WA | $3.8bn | $689,675 |
| SA | $1.75bn | $684,020 |
| NT | $35.8m | $587,217 |
NSW, Victoria and Queensland each recorded annual declines of 13–14%. The Northern Territory was the only state or territory to lift its lodgement value, from $31.8m. Average loan size by state as reported by Broker Daily.
The broker takeaway
Volume fell; the mix moved more. An upgrader-weighted book means bigger loans, more equity, tighter settlement sequencing and fewer easy refinances — so the work shifts from pricing conversations to timing and capacity ones.
News · Market Data · AFG Mortgage Index Q1 FY2027
Upgraders Hit a Record 46% of AFG’s Lodgements While the Average Loan Reached $730,145
The majors’ jump to 70% isn’t like-for-like — Macquarie moved into that bucket, and the history wasn’t restated.
Australian Finance Group’s September quarter index landed this week with the headline most people will repeat — lodgements down 12.4% year on year — and a second number that is far more useful: the broker channel’s client mix has tilted harder toward upgraders than at any point in AFG’s data. One of those numbers tells you about the market. The other tells you what is going to be on your desk for the next two quarters.
What the September quarter actually shows
AFG brokers lodged 36,720 mortgages worth $26.8 billion in the first quarter of FY2027 — down 4.5% by value on the June quarter and 12.4% year on year. The Adviser put the year-earlier comparison at 43,799 applications worth $30.5 billion, so the fall is in volume as much as value.
None of that is a surprise. The cash rate sits at 4.60% after the Reserve Bank’s 25 basis point rise on 29 September, the fourth of this tightening cycle. The May federal budget changed investor tax settings. National home prices, on realestate.com.au’s Home Price Report, fell for a sixth consecutive month in September and sit 3.3% below their March 2026 peak. AFG chief executive David Bailey was quoted by The Adviser saying “some moderation in activity was expected,” and pointed to improving activity toward the end of the quarter.
Where it gets interesting is underneath the total.
The 70% figure is a definitional change, not a verdict on competition
The Adviser reported the major banks and their affiliated brands at 70% of AFG lodgement volume, against 58%, with non-majors down to 30% from 42%. Taken at face value, that is a twelve-point collapse in non-bank and mutual share in a single step — the kind of number that gets quoted in a PD session, a lender BDM pitch and a client conversation within a week.
It should not be. AFG has newly classified Macquarie Bank as a major lender, and on the reporting available the historical series has not been restated. Both The Adviser and Kalkine Media noted the reclassification, and The Adviser reported that AFG itself flagged it as a reason not to read the increase as a straight competitive gain.
How much difference does a definition make? Look at AFG’s own earlier release. In its Q2 FY26 index — the December 2025 quarter — AFG put majors at 59% and non-majors at 41%, and defined “major” explicitly as the big four and their associated brands: CBA including Bankwest, Westpac including St George, BankSA and Bank of Melbourne, NAB including ubank, and ANZ including Suncorp, as at August 2024. Macquarie was not in that bucket. It is now.
The practical point: a series break is not a market movement. Before you repeat “the majors are back at 70%” to a client or a referral partner, ask your aggregator for a like-for-like number on the old definition. We cannot tell you from the published reporting how much of the jump is Macquarie and how much is genuine flow, and neither can anyone else quoting the headline.
Worth noting too: in the June quarter, Mortgage Professional Australia reported AFG’s non-majors gaining share against the prior year. A twelve-point reversal one quarter later is exactly the sort of discontinuity that should prompt a question about methodology rather than a thesis about competition.
The number that changed your pipeline
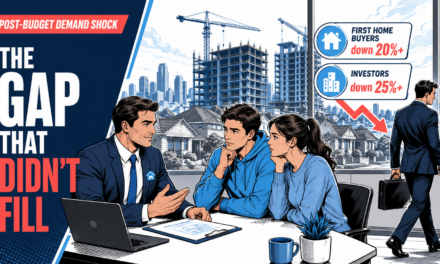
Upgraders made up 46% of AFG’s residential lodgements — a record on AFG’s data, up from 42% a year earlier — and the share approached 49% in September alone. At the same time:
- Investors fell to 32%, from 34% in the June quarter and 36% a year earlier.
- First home buyers held at 12%, unchanged on the quarter and up from 11% in Q1 FY26.
- Refinancing slipped to 15%, from 16% last quarter, 17% in Q1 FY26 and 26% in Q1 FY25 — below the 16% AFG had described as the lowest on record in its own Q2 FY26 release.
Read those together and the shape of the channel is clear. Nearly half of what AFG brokers are writing is somebody selling a property and buying a bigger one. That is a different transaction from a refinance and a very different transaction from a first home purchase, and it loads a different set of risks onto your file.
Bigger loans, more equity, less interest-only
The upgrader tilt shows up in the loan characteristics. The average loan size hit a record $730,145, up 4.5% year on year, from $727,345 in the June quarter and $698,438 a year earlier. Yet the national average LVR fell to 63.1%, from 63.4% last quarter and 65% a year ago. Broker Daily reported interest-only loans at 22% of lodgements, down from 25% last quarter and 24% a year earlier.
Bigger loans with more equity behind them and less interest-only structuring is precisely what you would expect when the marginal client is an upgrader rather than an investor or a first home buyer. These are people bringing six-figure sale proceeds to the table.
State-level averages, per Broker Daily: NSW highest at $819,286 (from $806,189), then Queensland at $703,907, Victoria at $694,009, WA at $689,675 (down from $699,412), SA at $684,020 and NT at $587,217 — the biggest quarterly jump, from $512,529, off the smallest base. On LVR, Broker Daily reported Victoria highest and unchanged at 68%, NSW and SA at 64%, NT at 63%, WA at 60% and Queensland lowest at 59%.
What an upgrader-weighted book changes on your files
This is the part that is worth more than the market commentary. An upgrader file is a sequencing problem before it is a pricing problem, and brokers whose process was built in the 2023–24 refinance boom are not necessarily set up for it.
Timing risk sits where price risk used to. Two contracts, two settlement dates and a falling price environment is a combination that rewards lenders who can actually hit a date. Turnaround and the lender’s willingness to accommodate a simultaneous settlement or a short bridge may matter more to the client’s outcome than 10 basis points. If your recommendation rationale only discusses rate and fees, it is not describing the thing that will determine whether this client’s transaction works.
Bridging and deposit mechanics come back into play. Where does the deposit on the purchase come from if the sale has not settled? Some clients will need a bridging facility, some a deposit bond, some an equity release against the outgoing property. Each has a different policy footprint across your panel, and policy on peak-debt treatment and end-debt servicing varies considerably between lenders.
Selling costs are real and often missing. Agent commission, marketing, conveyancing and, in some states, duty on the purchase will take a bite out of the equity the client thinks they have. Model net proceeds, not gross.
The retained-property scenario needs a separate conversation. A reasonable share of upgraders will consider keeping the existing home as an investment. That changes the servicing assessment, the rental-income treatment, the tax position and — after the May budget — the client’s assumptions about the economics. You are not giving tax advice; you are making sure they get it before they commit.
A falling-price market puts the valuation on the critical path. With prices six months into a decline, the valuation on the outgoing property and on the incoming one both carry risk. If the equity assumption moves, the whole structure moves.
ASIC’s guidance on the mortgage broking best interests duty sits in Regulatory Guide 273, and the duty itself comes from the credit reforms made under the National Consumer Credit Protection Act. We are not going to tell you what any particular paragraph requires of your file — that is a conversation for your licensee or compliance adviser. The general point is simply that if the features that decide an upgrader’s outcome are settlement timing and bridging capability, a file that documents only price is documenting the wrong things.
Refinancing at 15% and the pipeline you can’t bank on yet
Fifteen per cent is a striking number four rate rises into a cycle. Bailey described the level as “unusually low given the stage of the interest rate cycle,” per Broker Daily, and told The Adviser: “That lift in refinancing has yet to materialise, but history suggests it is not far away.” He pointed to serviceability constraints, rate uncertainty and lender retention efforts as the barriers.
Each of those is a known quantity in the broker channel right now. Clients who borrowed near capacity cannot pass a new lender’s assessment at a higher floor. Incumbent lenders are repricing to retain rather than losing the loan. And a client who expects rates to peak soon has a reason to wait.
For planning purposes, treat the refinance recovery as a probable future event, not a current one. If a quarter of your revenue assumption for the next six months rests on switching volume returning, that assumption is carrying risk. The work available now is in the upgrader and retention segments. The database review that identifies which of your existing clients are able to move — not just which would benefit — is the one worth doing before the market turns, because that list is what you act on the week it does.
Fixed at 1.5% and the file-note problem
Broker Daily reported fixed-rate loans at 1.5% of AFG lodgements — the lowest in the index’s history — down from 3.8% in the June quarter and 3% a year earlier. Variable products took 97.6%, split between standard variable at 89.1% (up from 87.5%) and basic variable at 8.5%. For scale, Broker Daily noted fixed made up 38.2% of AFG lodgements in Q1 FY21–22.
Fixed is, for practical purposes, not being written. That is a rational response to a market pricing further tightening into fixed rates while borrowers expect a peak. But it creates a quiet exposure: when 98.5% of your lodgements go one way, the file needs to show that the alternative was considered for this client and ruled out for stated reasons — not that fixed stopped being a product. A one-line note on why a split or a fixed portion did not suit the client’s circumstances costs very little at the time and is the difference between a defensible file and a pattern.
Western Australia’s turn
WA brokers lodged $3.8 billion, down 10.5% on the quarter and 6.2% year on year — the state’s first annual decline after 11 consecutive quarters of year-on-year growth. For three years WA has been the engine of the national lodgement figure. That has stopped.
Elsewhere, NSW lodged $8.6 billion, Victoria $7.8 billion and Queensland $4.9 billion, with each of the three recording annual declines of 13–14%. SA lodged $1.75 billion. The Northern Territory, at $35.8 million from $31.8 million, was the only state or territory to lift its lodgement value.
On the aggregator’s own book, The Adviser and Kalkine Media reported AFG Home Loans at 7.1% of residential lodgements, down from 7.9% in the June quarter. Kalkine Media reported AFG Securities lodgements down 24.5% on the quarter and 17.7% year on year, with the loan book closing at $7.3 billion, up 28% year on year.
What to review this week
- Count your own mix. Pull your last 20 settled files and split them by purpose. If upgraders are a third or more, your process needs a sell-and-buy workflow, not a refinance one.
- Write down which lenders on your panel do bridging well. Peak-debt treatment, end-debt servicing, maximum bridging term, whether interest is capitalised. Have the answer before a client asks, not after.
- Add net sale proceeds to your fact-find. Gross equity minus agent fees, marketing, conveyancing and duty. Clients consistently overestimate this.
- Check that your recommendation rationale can carry a timing reason. If your template only has fields for rate, fees and features, it cannot record why you chose a lender for settlement certainty.
- Build the “able to refinance” list now. Segment your database by whether the client would pass a new assessment, not just whether they would save. That is the list you work when switching comes back.
- Ask your aggregator for a like-for-like lender share series. If you use channel share to argue for or against a lender, you need a number that is not broken by a reclassification.
- Spot-check five recent files for a fixed-rate note. One sentence per file on why variable suited that client.
Key takeaways
- AFG lodged $26.8bn across 36,720 mortgages in the September quarter — down 4.5% on the quarter and 12.4% year on year.
- Upgraders reached a record 46% of residential lodgements, near 49% in September. Investors eased to 32%, first home buyers held at 12%, refinancing slipped to 15%.
- The average loan size set a record at $730,145 while the national LVR fell to 63.1% — bigger loans with more equity behind them.
- The majors’ reported 70% share is not comparable with the prior 58%: Macquarie has been newly classified as a major and the history was not restated. AFG cautioned against reading it as a competitive gain.
- An upgrader-weighted book shifts the broker’s value from price to sequencing — settlement timing, bridging, net sale proceeds and valuation risk.
The bottom line
A 12.4% fall in lodgements is the kind of figure that invites a defensive read of the quarter. The composition data invites a more useful one. The channel has not simply shrunk — it has changed job. Fewer switchers, fewer investors, and nearly half the book now made up of clients moving house in a market where prices are falling, settlement dates are binding and the equity in the sale is the whole structure.
Bailey’s framing, per The Adviser, was that “the role of the broker remains critical” in an uncertain housing market. That is the sort of thing a chief executive says. What the numbers suggest is more specific: the part of the role that is critical right now is the part that gets two settlements to land in the right order. Brokers who build that capability into their process — and document it on the file — are positioned for the book they actually have, rather than the one the last cycle gave them.
Breaking news for modern brokers
Lender policy shifts, regulator activity and market data — read in broker terms, twice a day.
Sources
AFG Mortgage Index Q1 FY2027, as reported by Broker Daily (LVRs, loan size, fixed and interest-only shares, state detail), Broker Daily (borrower mix), The Adviser (lender share, state values, Bailey quotes) and Kalkine Media (Macquarie reclassification, AFG Securities). Prior-period definitions and figures from AFG’s own Q2 FY26 index market release. June quarter context from Mortgage Professional Australia. Cash rate, inflation and home price context from Australian Broker. Best interests duty guidance: ASIC RG 273. AFG’s primary market release for this quarter was not publicly available at the time of writing; figures are attributed to the outlets that reported them.
Interactive · Broker Tool
Segment Explorer & Upgrader-File Readiness Check
See what moved in each borrower segment, then score how ready your process is for an upgrader-weighted book.
1. What moved in the September quarter
Up from 42% a year earlier. Approached 49% in September alone.
What it means for your week: nearly half your lodgements are sell-and-buy transactions. Two contracts, two settlement dates, and the equity in the sale holding up the whole structure. Lender choice starts turning on settlement certainty and bridging policy, not price.
Down from 34% in the June quarter and 36% a year earlier.
What it means for your week: the May budget’s changes to investor tax settings are showing up in the mix. Interest-only fell to 22% of lodgements over the same period, per Broker Daily — consistent with fewer investor files. Expect more questions about whether the numbers still work, and make sure clients get that answered by their accountant.
Unchanged on the quarter; up from 11% in Q1 FY26.
What it means for your week: the segment held its share while the total fell, so first home buyer files are not disappearing — they are simply not growing as a proportion. The Adviser reported majors taking 76% of AFG’s first home buyer lodgements, from 72% in the prior quarter.
From 16% last quarter, 17% in Q1 FY26 and 26% in Q1 FY25.
What it means for your week: AFG’s David Bailey called the level “unusually low given the stage of the interest rate cycle,” citing serviceability, rate uncertainty and lender retention. Don’t build a revenue forecast on the recovery — build the list of clients who could actually pass a new assessment, so you can act the week it returns.
2. Upgrader-file readiness check
Tick what your process already does. Seven items — be honest rather than generous.
Start ticking to see where you sit
Nearly half of AFG’s lodgements this quarter were upgraders. The question is whether your process was built for that book or for the refinance book of two years ago.
Next step: take the items you left unticked to your next team meeting, and ask your aggregator for a like-for-like lender share series before you use channel share in any lender conversation.
This tool is a prompt for your own process review. It is general information, not advice, and it is not a compliance assessment — your licensee sets the standard your files must meet.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator's compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC's responsible lending guidelines.