The Broker Times · Pipeline Data
The Leading Number and the Lagging Number Have Stopped Agreeing
August 2026 lodgement and pre-approval movements, and what sits behind them.
Four Numbers From August
Investor pre-approvals vs August 2025
Loan Market, reported by The Adviser
Owner-occupied pre-approvals, same period
Loan Market, reported by The Adviser
Investor lodgements, year to date vs 2025
Loan Market, reported by The Adviser
FHB lodgements, August vs July
Loan Market, reported by The Adviser
Same Segment, Two Directions
Leading — Investor Pre-Approvals
−55%
Measured against August 2025. Pre-approvals describe intent that has not yet become an application.
Lagging — Investor Lodgements YTD
+6.5%
Still ahead of the corresponding period in 2025, even as the monthly comparison fell 15.75% year on year.
August Movements at a Glance
The Takeaway
A settlements or lodgement report describes decisions borrowers already made. Pre-approval volume describes decisions they are making now. In August those two measures pointed in opposite directions for investors — which means a book that still looks healthy on year-to-date lodgements may already have lost the enquiry that would have refilled it.
Sources: Loan Market August lodgement figures as reported by The Adviser, 17 September 2026; Equifax August mortgage demand figures as reported by The Adviser, 16 September 2026. Figures describe market-level movements, not the performance of any individual brokerage.
Growth · Pipeline Strategy
Investor Pre-Approvals Fell 55% While Year-to-Date Lodgements Held at +6.5%. The Gap Is Your Forward Book, Not a Contradiction
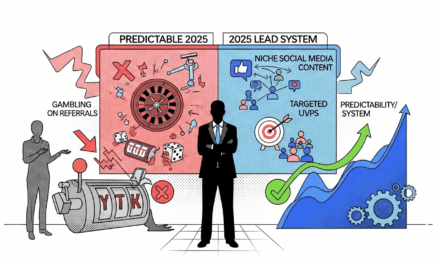
Two numbers from the same August dataset point in opposite directions for the same borrower segment. Brokers who resolve that contradiction by trusting the bigger, more familiar number will be planning the December quarter from a report that describes February.
In This Article
The two numbers that disagree
Loan Market’s August lodgement figures, reported by The Adviser on 17 September, contain a pair of data points that look like an error until you notice what each one is measuring.
The first: investor pre-approvals dropped 55 per cent from August 2025. The second: investor loan lodgements were still 6.5 per cent higher than in the corresponding period of 2025 on a year-to-date basis.
One of those numbers says the investor segment has more than halved. The other says it is ahead of where it was last year. Both appear in the same report, and both can be true at once, because they are measuring different moments in the same borrower’s journey — and they are separated by the weeks or months it takes a pre-approval to become a lodgement, and a lodgement to become a settlement.
For a brokerage, that gap is not a statistical curiosity. It is the difference between the revenue you have already earned and the revenue you have not yet won.
Key Takeaways
- Loan Market reported investor pre-approvals down 55 per cent from August 2025, and owner-occupied pre-approvals down 12.6 per cent over the same period.
- On a year-to-date basis, investor lodgements were still 6.5 per cent higher than the corresponding period of 2025 — while the year-on-year monthly comparison fell 15.75 per cent.
- First home buyer lodgements rose 6 per cent from July and 7 per cent from June, but remained 12 per cent below a year earlier and 4.4 per cent down year to date.
- Separately, Equifax figures reported by The Adviser put external refinancing almost flat at −0.8 per cent year on year, while same-lender refinancing fell 23 per cent.
- A pipeline weighted to one segment can look stable on trailing reports while the enquiry that would refill it has already gone.
Why pre-approvals move first
A pre-approval is the earliest formal record that a borrower intends to transact. It sits ahead of the property search, ahead of the contract, and well ahead of the lodgement that eventually produces a settlement and a commission. When pre-approval volume in a segment falls, the effect does not show in lodgements immediately — it shows when the borrowers who would have lodged simply are not there.
That is what makes a 55 per cent fall in investor pre-approvals a different kind of signal from a 15.75 per cent fall in investor lodgements. The lodgement number reports a slowdown already underway. The pre-approval number describes intent that has not yet been converted, and in August a large share of it was never formed in the first place.
Loan Market’s Shay Waraker, quoted by The Adviser, framed the pre-approval softness in terms of market conditions rather than a collapse in the segment:
“Pre-approvals were lower in August than last, particularly for investors. This could indicate lower competition and a slower than usual spring selling season”
Shay Waraker, Loan Market, quoted by The Adviser, 17 September 2026
That reading matters, and it should temper any impulse to treat a single month as a structural break. A softer spring selling season with fewer competing bidders is a meaningfully different explanation from investors leaving the market permanently — and the two imply different responses from a brokerage. But either way, the near-term consequence for a broker’s forward book is the same: fewer investor files entering the top of the funnel in August than in August last year.
A note on what these figures are. The pre-approval and lodgement movements above come from Loan Market’s own flow, reported by a single trade outlet. They are not an industry-wide census, and they are not ABS or APRA aggregates. Treat them as a well-sourced directional signal from one large network, not as a settled measure of the whole market.
Where demand is actually holding
The first home buyer picture in the same report runs the other way, and it is the more encouraging half of the data. FHB lodgements rose 6 per cent from July and 7 per cent from June. They nonetheless remained 12 per cent lower than a year earlier, and 4.4 per cent down year to date.
“Loan lodgements are down across the board compared to last year, however August did see some green shoots from first home buyers”
Shay Waraker, Loan Market, quoted by The Adviser, 17 September 2026
So the month-on-month direction is up, while the annual direction is still down. That is a recovery from a low base, not a return to last year’s volume, and the distinction is worth holding onto when you set expectations internally.
A separate dataset adds a second layer. Equifax’s August mortgage demand figures, reported by The Adviser on 16 September, showed total mortgage demand down 14.1 per cent year on year — a fifth consecutive monthly decline — with first home buyer demand down 20.1 per cent nationally, which the outlet described as the steepest annual fall since 2022.
Read together, the two sources are not contradictory so much as differently framed: Loan Market is describing its own lodgement flow month to month, Equifax is describing credit enquiry demand year on year. Where they agree is that the annual comparison is negative almost everywhere.
The Equifax release contains one split that deserves more attention from brokers than it usually gets:
| Segment | August movement (year on year) | What it implies |
|---|---|---|
| External refinancing | −0.8% | Close to flat. Borrowers willing to change lender are still doing so. |
| Refinancing with the same lender | −23% | A far sharper fall in internal retention activity. |
| Total mortgage demand | −14.1% | Fifth consecutive monthly annual decline. |
| First home buyer demand | −20.1% | Described as the steepest annual fall since 2022. |
In a market where total demand fell 14.1 per cent, external refinancing was almost unchanged. That is the segment where a broker’s work is most clearly the reason the transaction happens at all — and on this data it held up while nearly everything around it fell. For a brokerage looking at a thinner purchase pipeline, that is the most commercially useful line in either release.
The proportional point. None of this says refinancing is growing. It says refinancing to a new lender declined far less than the rest of the market. In a contracting book, a segment that is merely flat becomes a larger share of your revenue by default — and it is worth knowing that before you decide where the next quarter’s effort goes.
The reporting trap
Most brokerages review performance on settlements, or on lodgements at best. Both are trailing measures. A settlement this month reflects an enquiry from one to three months ago, sometimes longer on construction or complex self-employed files.
That creates a specific and avoidable failure. If your book is weighted toward investor lending, your year-to-date lodgement line may still read positively — the Loan Market data has it 6.5 per cent up on the corresponding 2025 period — while the enquiry flow that would sustain it in the December quarter has already thinned considerably. Reviewing the trailing number alone, you would conclude the segment is fine and allocate accordingly.
The inverse trap applies to first home buyers. A brokerage looking only at the annual comparison sees FHB lodgements down 12 per cent and concludes the segment is deteriorating, missing that the last two months moved up. Those are opposite errors produced by the same habit: reading one time horizon and treating it as the whole picture.
What a mix shift does to revenue timing
Segments do not pay the same way or at the same speed. An investor purchase file and a straightforward external refinance differ in loan size, in time to settlement, in the amount of work per file, and in how likely the client is to return. When the composition of your pipeline moves, your revenue timing moves with it, even if total file count looks steady.
This is why a mix shift is harder to spot than a volume drop. A volume drop announces itself. A mix shift shows up as a normal-looking month that quietly pushes income into a later quarter, or loads more hours onto the same fee.
A forward-book review you can run this week
This is a two-hour exercise for most brokerages, and it does not need new software.
- Split your pipeline by segment, not just by stage. Investor, first home buyer, owner-occupier upgrader, external refinance, and internal variation. Most CRMs will do this with an existing field.
- Count live pre-approvals by segment, and compare with the same point last year. This is the single number that tells you what the next quarter looks like. If you have never pulled it, pull it now — you are looking for the direction and size of the change, not precision.
- Calculate your own pre-approval-to-lodgement conversion rate by segment. Market-level movements only matter to the extent they show up in your funnel. Your conversion rate is what translates one into the other.
- Identify your concentration risk. If any one segment is more than roughly 40 per cent of your forward pipeline, write down what happens to your revenue if that segment’s enquiry flow halves. The August investor figure is a reminder that a halving is not a hypothetical.
- Check your expiring pre-approvals. Pre-approvals issued in a different rate environment may no longer reflect what a lender will do today. Borrowers holding one may need a current conversation rather than an assumption.
- Review your existing database for refinance candidates. On the Equifax data, external refinancing was the most resilient segment in August. Your back book is where those clients already are.
- Set a diversification target with a date attached. “More commercial” is not a plan. “Two asset finance conversations a week from existing clients by 31 October” is.
If you do only one of these: count your live pre-approvals by segment and compare with the same week last year. It takes twenty minutes and it is the closest thing a brokerage has to a forward order book.
Client conversations this changes
For investor clients, the softer pre-approval environment cuts in a direction some will not have considered. Waraker’s reading — that lower pre-approval volume could indicate lower competition and a slower spring selling season — describes conditions that can favour a prepared buyer. A client who is genuinely in a position to transact may face fewer competing bidders than they would have a year ago. That is a legitimate observation about market conditions, and it is not a recommendation to buy. Whether a purchase suits a particular client depends on their circumstances, objectives and capacity, and that assessment belongs in the file.
For first home buyers, the useful framing is the borrowing capacity conversation. Waraker’s comment on the rate outlook was explicitly conditional:
“It’s positive momentum, though if the cash rate does increase again this year as many economists have predicted, borrowing capacities will be impacted, which could lead to a slow down”
Shay Waraker, Loan Market, quoted by The Adviser, 17 September 2026
That is a forecast attributed to economists, not a certainty, and it should be presented to clients as exactly that. What it does support is a practical point: a client holding a pre-approval issued months ago should not assume the figure still stands, and the responsible move is to check rather than to reassure.
Compliance framing. Nothing in this data changes a broker’s obligations, and none of it should be used as a reason to accelerate a client toward a transaction. The Best Interests Duty and responsible lending obligations under the National Consumer Credit Protection Act 2009 apply to the recommendation you make for each individual client, on their circumstances — not to market conditions. Where market timing enters a client conversation, it is context, and your file notes should show that the recommendation rested on the client’s objectives and capacity. For how these obligations apply to your own processes, your licensee or aggregator compliance team is the right source.
What to watch next
Three things will tell you whether August was a turning point or a soft patch.
- Whether the FHB month-on-month improvement continues into September and October. Two months of gains from a low base is a trend only if a third follows.
- Whether investor pre-approvals stabilise once the spring selling season is fully underway. If the slower-season explanation holds, the gap against 2025 should narrow.
- Whether external refinancing keeps outperforming. A segment that is flat while the market falls 14.1 per cent is doing something structurally different, and it is worth knowing if that persists.
The strategic point
The August data does not tell brokers that the market is collapsing, and it does not tell them it is recovering. It tells them something more specific and more useful: that the leading indicator and the lagging indicator for the same borrower segment have separated, and that the trailing number is the more comfortable of the two to read.
A brokerage that plans from lodgements and settlements alone is steering from a report about decisions borrowers made months ago. The pre-approval line is the nearest thing the channel has to a forward view, and in August it was saying something the settlement line was not. That is worth twenty minutes of your week — well before it becomes worth a quarter of your revenue.
Frequently Asked Questions
They measure different points in time. The year-to-date lodgement figure accumulates applications made across the whole year, including stronger earlier months. The pre-approval figure compares a single month against the same month a year earlier and captures borrowers at the very start of the process. A strong first half can keep a year-to-date total positive well after new enquiry has slowed.
Not automatically. Some borrowers proceed without a formal pre-approval, and conversion rates from pre-approval to lodgement vary between brokerages and over time. That is why the practical step is to measure your own conversion rate by segment rather than applying a market-level movement directly to your own numbers.
On the Equifax figures reported by The Adviser, external refinancing fell just 0.8 per cent year on year while same-lender refinancing fell 23 per cent. External refinancing is the activity most closely associated with broker-assisted transactions. In a market where total demand fell 14.1 per cent, a near-flat segment becomes a larger proportion of available business.
Market conditions are context, not a recommendation. Lower competition may be a relevant fact for a client who is already in a position to transact, but whether a purchase is appropriate depends on that client’s circumstances, objectives and capacity. Your obligations attach to the individual recommendation and the reasoning recorded on the file. Confirm your own process with your licensee or aggregator compliance team.
The lodgement and pre-approval figures come from Loan Market’s own flow as reported by The Adviser, and the demand figures from Equifax as reported by the same outlet. They are directional signals from large datasets, but they are not official statistics. ABS lending indicators and APRA’s ADI statistics remain the authoritative sources for market-wide lending volumes.
Breaking News for Modern Brokers
Practical, broker-first analysis of the data, policy and lender changes that affect your book.
Interactive · Broker Tool
Forward Book Exposure Check
Enter the rough share of your current pipeline in each segment. The tool applies the published August market movements to show where your forward book is most exposed.
Step 1 — Your pipeline mix (approximate %)
Where the pressure sits in your mix
What to look at first
Run the seven-step forward-book review in the article alongside this, and compare your live pre-approval count with the same week last year.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator's compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.