A regional bank just bought distribution in one state
Bendigo completed the RACQ Bank loan and deposit book migration on 18 November 2026. Its own full-year numbers show which channel is growing.
What completed on 18 November
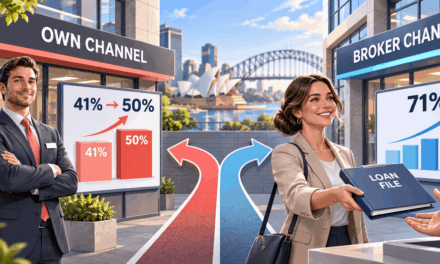
Where Bendigo’s home lending came from in FY26
Growth in the bank’s own digital origination over the year to 30 June 2026.
Decline over the same year, which the bank attributes to its exit from the legacy mortgage partner channel.
Bars are indicative of direction, not to scale against each other. Residential lending overall was down slightly across the year.
How the deal got here
The takeaway. Ninety thousand Queensland borrowers have a new lender, a new app and new statements this week. That is the most reachable your migrated clients will be all year — and the same week a referral pathway into 1.7 million members was due to switch on. Open the CRM, filter for RACQ Bank, and call them before someone else does.
Sources: Bendigo Bank media release, “Bendigo Bank completes RACQ acquisition, passes 3 million customer milestone”, 18 November 2026; Bendigo Bank media release, “Bendigo Bank to acquire RACQ Bank loan and deposit book”, 4 December 2025; Bendigo and Adelaide Bank, “Financial Results for the full year ended 30 June 2026”, 24 August 2026. Figures are as published by Bendigo and Adelaide Bank and are not independently verified by The Broker Times.
Bendigo’s Third-Party Home Lending Fell 5.5% While Its Digital Channels Grew 13%. It Just Added 90,000 Queensland Customers — and a Referral Deal With 1.7 Million RACQ Members
A completed book migration looks like corporate housekeeping. Read it next to the bank’s own channel numbers and it is a distribution story — arriving in the regional tier rather than at the majors.
Key takeaways
- Bendigo confirmed on 18 November 2026 that it had completed the RACQ Bank loan and deposit book migration: 90,000 customers, about $2.7 billion in loans and $2.4 billion in deposits.
- In its FY26 results the bank reported residential lending growth of 13.0% through digital channels and a 5.5% decline through third party originated channels, which it attributes to exiting its legacy mortgage partner channel.
- The December 2025 announcement said that on completion Bendigo would enter a referral arrangement with RACQ — covering deposits, savings and home loans — for an organisation with 1.7 million members. The completion release does not mention it.
- Queensland was flagged to rise from 15% to 18% of the bank’s residential lending portfolio.
- For brokers the immediate action is operational: identify clients whose loan has just moved, confirm the post-migration terms, and document any recommendation — including a recommendation to stay.
In this article
On 18 November, Bendigo Bank confirmed it had completed the migration of RACQ Bank’s loan and deposit book. The headline numbers are the kind that usually get a paragraph in the trade press and then disappear: 90,000 customers, about $2.7 billion in loans, about $2.4 billion in deposits, and a bank that passed three million customers nationwide the week before.
The number worth your attention is not in that release. It is in Bendigo’s full-year results from August, in a single sentence about where its residential lending came from: “Residential lending was down slightly over the year, with strong growth in digital channels (up 13.0%) offset by a decline in third party originated channels (down 5.5%) following our exit from the legacy mortgage partner channel.”
Thirteen per cent up through its own channels. Five and a half per cent down through third party. And this week, a completed acquisition that lifts Queensland from 15% to 18% of its residential lending portfolio and — on the terms the bank announced last December — switches on a home loan referral arrangement with an organisation that has 1.7 million members.
That is a distribution story, and it is happening at the regional tier rather than among the majors, where most of the channel-share conversation has been.
What actually completed this week
Bendigo’s own release of 18 November 2026 states that the bank “welcomed 90,000 new customers from Queensland following the successful acquisition of RACQ’s banking business”, and that the acquisition “will add approximately $2.7 billion in loans and $2.4 billion in deposits to Bendigo Bank’s portfolio of more than $100 billion in assets”.
“Our teams have worked hard to ensure a smooth transition for our new customers leveraging the repeatable customer migration capability we have built. This acquisition is important to our agenda of sustainable growth and expands Bendigo Bank’s already strong Queensland presence.”
Richard Fennell, Chief Executive Officer, Bendigo Bank, 18 November 2026
Former RACQ Bank members now have access to Bendigo’s digital and phone banking and, per the release, “in-person support at our 70 branches across Queensland”.
The deal was first announced on 4 December 2025. In that announcement, Bendigo put the book at $2.7 billion in loans and $2.5 billion in deposits as at 30 June 2025 — the deposit figure has moved by about $100 million between announcement and completion, which is unremarkable over eleven months but worth knowing if you are quoting numbers to a client.
The same December announcement contained the line that matters most for the broker channel: “Upon completion, Bendigo Bank will enter into a referral arrangement for deposits, savings and home loans with RACQ which has 1.7 million members.”
Note what is and is not established here. The referral arrangement was announced in December 2025 as commencing on completion. The completion release of 18 November does not mention it. So the honest position is that the arrangement was announced to start now, and the bank has not said anything further about it this week. If you are working in Queensland, it is worth asking your Bendigo business development manager directly how that referral pathway operates and whether it touches home loans the broker channel would otherwise see.
Read the channel numbers properly
It would be easy, and wrong, to turn “third party down 5.5%” into “brokers are deserting Bendigo”. The bank’s own explanation is specific: the decline followed its exit from the legacy mortgage partner channel. That is a deliberate withdrawal from a white-label and mortgage-manager arrangement, not a verdict on broker support. The Adviser’s reporting on the same results noted growth in the broker product suite on the Bendigo Lending Platform partly offsetting the decline from the legacy Mortgage Partners portfolio and lower white-label volumes.
So the accurate version is narrower and more useful: Bendigo’s third-party originated residential lending contracted over FY26, largely because the bank closed a legacy third-party pathway, while its own channels grew 13.0% off a platform it now has everywhere. In the same results, the bank said around 80% of its home loans are written through the Bendigo Lending Platform, following the full rollout of that platform to all branches, and that almost half of all digitally eligible customers are joining through the Bendigo Bank app.
Residential lending overall was down slightly across the year. Total lending balances rose 3.5% over the second half, and Bendigo said it “regained lending momentum following a return to growth in our residential lending book through the second half”.
On the market-share figures. The Adviser reported Bendigo’s residential lending at $66.4 billion as at 30 June 2026, down 0.4% over the year, with its national home lending market share slipping from 2.77% to 2.57%. Those two figures appear in that outlet’s reporting rather than in the bank’s media release, so treat them as that outlet’s numbers rather than established fact, and check them against APRA’s monthly statistics if you intend to repeat them.
Why a 1.7 million-member referral pathway is a different kind of competitor
Brokers are used to competing with proprietary channels. A branch network and a call centre are a known quantity: they convert the customers who walk in or ring up.
A membership referral arrangement is a different shape. RACQ’s 1.7 million members did not join a bank; they joined a motoring and insurance organisation, and they have an existing relationship and a reason to open the email. That is a warm distribution list of a size no individual brokerage can match, pointed at deposits, savings and home loans.
This is the same structural question that has been running at the majors — how much of the book the lender’s own channels write, and how fast that share is moving — arriving in the regional and customer-owned tier. The difference is that a regional bank cannot out-advertise the majors, so buying or partnering its way to distribution is the rational move. On that logic, this is unlikely to be the last deal of its shape.
For brokers the practical consequence is not a crisis. It is that in one state, the pool of borrowers who will be prompted to consider one particular lender directly just got considerably larger.
The integration sits on top of a heavy change agenda
Worth knowing before you set turnaround expectations for a client. Across FY26 and into FY27, Bendigo is carrying:
- A non-financial risk rectification plan announced in August 2026, which the bank described as a multi-year program expected to require an initial estimated provision of $70 million, included in the FY26 result.
- A Financial Crime Transformation Program that commenced in December 2025, focused on enterprise-wide AML/CTF risk management including transaction monitoring.
- Phase two of a productivity program underpinned by strategic partnerships with Infosys and Genpact, with $29 million (pre-tax) of restructuring costs in FY26 and a further $56 million to $66 million expected in FY27.
- The completed consolidation of core banking systems — from eight systems in 2019 to one by the end of calendar 2025.
The bank’s track record on migrations is genuinely good: it moved 180,000 Adelaide Bank customer accounts onto its core platform before this one, and it cited that “repeatable customer migration capability” in both the results and the completion release. But a lender running a $70 million risk remediation, an AML/CTF transformation, an outsourcing-led restructure and a 90,000-account integration in the same window is a lender whose service levels are worth verifying rather than assuming. If you have a time-critical Queensland file, confirm current assessment timeframes before you commit a client to a cooling-off period or a finance clause date.
What to do this week
1Identify your RACQ-settled clients
Search your CRM for RACQ Bank as lender. Those loans have moved. Your client’s statements, product name, online banking and possibly their fee and feature set have changed, and they have been told to download a different app. Migrated borrowers are, for a short window, unusually receptive — they are already being asked to re-engage with their banking.
2Check what changed on the product, not just the brand
Before you form any view, get the actual numbers: the current rate, whether an offset or redraw carried across on the same terms, annual package fees, and whether any discount applied by RACQ Bank has been preserved. A brand migration is not automatically a detriment, and you cannot advise either way until you have the post-migration terms in front of you.
3Treat the review as credit assistance, because it is
If a migrated client calls you and you survey the market and conclude they should stay where they are, that conclusion is credit assistance. RG 273.117 is explicit that it does not matter whether you have provided credit assistance to that consumer before — if you suggest a consumer remain in a home loan you previously helped them obtain, you need to act in their best interests in making that suggestion. Document the comparison and the reason, whichever way it falls.
4Sense-check your own panel coverage in Queensland
If a meaningful share of your book is Queensland and your accreditations do not include the lenders now competing hardest there, that is a commercial problem before it is a compliance one. RG 273.112 asks you to be satisfied that the credit products you can access and recommend are sufficient to allow you to act in your consumers’ best interests, and RG 273.113 says you should be accredited with a reasonably representative panel of credit providers, using your judgement on whether your panel’s composition is sufficient.
5Ask the referral question out loud
Put it to your BDM: is the RACQ referral arrangement live, what products does it cover, and does a referred member who asks about a home loan end up in a proprietary channel? You are entitled to know the shape of the channel you are competing with, and the answer will tell you how much weight to put on points 1 and 4.
What to watch next
Three things. Whether Bendigo discloses the referral arrangement’s commencement and scope — the completion release was silent on it. Whether the next half-year result, due early in 2027, shows third-party originated residential lending stabilising now that the legacy mortgage partner exit has washed through, or continuing to fall while digital channels grow. And whether other regional and customer-owned banks follow the same playbook: buy a book, inherit a membership, and reach borrowers without paying for distribution per file.
The takeaway
A bank that holds a low single-digit share of the national mortgage market has just added 90,000 customers and about $2.7 billion in loans, and lifted Queensland from 15% to 18% of its residential lending portfolio, at a point where its own channels are growing at 13% and its third-party channel is not. None of that makes Bendigo a worse lender to deal with, and none of it changes a single credit policy. What it changes is the competitive geometry in one state, and the size of the list of borrowers who will be invited to go direct.
The brokers who do well out of this week are not the ones who read a completion notice as bad news. They are the ones who open their CRM, find the clients whose loan just moved, and ring them before the new lender does.
Common questions
Nothing in the 18 November release or the FY26 results addresses broker accreditation or remuneration arrangements. The releases deal with the customer migration, the balance sheet effect and the bank’s channel performance. Any question about your own accreditation, commission or lodgement process should go to your aggregator or your Bendigo business development manager rather than being inferred from a corporate announcement.
The December 2025 announcement said Bendigo would enter the referral arrangement with RACQ, covering deposits, savings and home loans, upon completion. Completion occurred on 18 November 2026. The completion release itself does not mention the referral arrangement, and Bendigo has not published further detail about its scope or start date, so its current status is not something this article can confirm. Ask your BDM.
You can only recommend what is in the client’s best interests on the facts, and you need the post-migration terms before you can form that view. A migration is not by itself a reason to move. Establish the current rate, features, fees and any retained discount, compare properly, and record the reasoning — including if the answer is to stay. Your licensee’s process governs how that comparison is documented.
The bank does not say that, and the figure does not support that reading on its own. Bendigo attributes the decline to its exit from the legacy mortgage partner channel — a specific white-label and mortgage-manager pathway it closed. What the number does show is that the growth in its residential book over FY26 came from its own digital channels rather than third party origination.
Breaking news for modern brokers
Lender policy, regulator action and market data — read for what it changes on your files.
Sources: Bendigo Bank, “Bendigo Bank completes RACQ acquisition, passes 3 million customer milestone”, media release, 18 November 2026; Bendigo Bank, “Bendigo Bank to acquire RACQ Bank loan and deposit book”, media release, 4 December 2025; Bendigo and Adelaide Bank Limited, “Financial Results for the full year ended 30 June 2026”, 24 August 2026; The Adviser, “Bendigo finalises RACQ Bank takeover”, 19 November 2026; ASIC Regulatory Guide 273, Mortgage brokers: Best interests duty, June 2020, at RG 273.112, RG 273.113 and RG 273.117. Corporate figures are as published by Bendigo and Adelaide Bank and are not independently verified by The Broker Times.
Migrated-client review planner
For a client whose loan has just moved to a new lender in a book migration. Work the checklist, pick where the file landed, and take away a next step and a file note.
Step 1 · Confirm what actually changed
You cannot form a view until these are in front of you. Tick each one you have verified in writing.
0 of 7
Step 2 · Where did the file land?
Choose the outcome your comparison supports. Each one produces a different next step — and all three need to be recorded.
The planner will show the next step for that outcome and a file-note skeleton you can adapt.
Before you use any of this on a live file: the file-note wording here is a skeleton, not a compliance product. Your licensee's process, templates and record-keeping requirements govern. Check it against them, and raise anything uncertain with your aggregator's compliance team.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.