Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: A 40-Year Business Loan Takes $425 Off the Monthly and Adds $613,515 in Interest. RG 273.5 Says the Best Interests Duty Doesn’t Reach the File
The Broker Times · At a glance
The 40-Year Business Loan, in Numbers
First Federal stretched its business loan term from 30 years to 40 on 5 November 2026. Here is what the extra decade buys, what it costs, and where the file sits in the regulatory perimeter.
The product envelope
As published on First Federal’s First Business 40 broker page, with rates stated as correct as at October 2026.
What the extra decade costs
A $1,000,000 principal-and-interest loan at the advertised 7.24% starting rate, fees excluded. The Broker Times’ calculation.
Where the pricing actually sits
Fees as published on the lender’s broker page, applied to a $1,000,000 loan secured by residential property at 75% LVR.
| Fee | As published | On $1m |
|---|---|---|
| Establishment (residential) | 0.75% | $7,500 |
| Application | Higher of $1,950 or 0.20% | $2,000 |
| Risk fee (under 80% LVR) | 1.50% | $15,000 |
| Valuation | At cost | — |
| Ongoing | 0.10% per month | $1,000/mth |
| Discharge | $880 | $880 |
| Upfront fees, excluding valuation | $24,500 (2.45%) | |
The perimeter, in three steps
ASIC’s own statements of where the National Credit Code and the best interests duty reach.
ASIC says the Code applies where credit is provided wholly or predominantly for personal, domestic or household purposes, or to purchase, renovate or improve residential property for investment.
The best interests obligations “apply only in relation to credit products that are regulated under the National Credit Act”.
An anti-avoidance provision bans schemes whose sole or non-incidental purpose is avoiding Part 3-5A. ASIC says it is more likely to scrutinise schemes with no commercial purpose beyond avoidance.
Why this matters on a business-purpose file
On ASIC’s own description of scope, a loan genuinely and predominantly for business purposes sits outside both the Code and the best interests duty — even when the security is the client’s home. The consumer protections that would normally sit over a 40-year, 80% LVR mortgage are not there.
Whether any particular file is genuinely business purpose is a question of fact, not a question of paperwork. Check the characterisation with your licensee before you rely on it.
On a $1m loan the extra decade reliably buys about $425 a month of cash flow and costs roughly $613,515 in interest. Whether it also buys capacity depends on the term the lender assesses over, which its page does not state — and on a genuine business-purpose file, the note that records all of this is one you write by choice.
A 40-Year Business Loan Takes $425 Off the Monthly and Adds $613,515 in Interest. RG 273.5 Says the Best Interests Duty Doesn’t Reach the File
First Federal extended its maximum business loan term from 30 years to 40 on 5 November 2026, at up to $3 million and 80% LVR against residential or commercial security. The arithmetic is unforgiving — and on a genuine business-purpose file, the consumer protections that would normally sit over a mortgage that size are not there at all.
Five rate rises in nine months have changed what brokers reach for. The Reserve Bank lifted the cash rate target to 4.85% effective 4 November 2026, the fifth 25 basis point increase of 2026, taking the target from 3.60% before February’s rise to 4.85% today. When capacity tightens that fast, the levers that remain are the ones that stretch the loan rather than the borrower — and the longest of those levers just got longer.
What First Federal actually launched
On 5 November 2026, non-bank lender First Federal launched First Business 40, extending its maximum business loan term from 30 years to 40. Australian Broker reported the launch, noting the lender is also accepting commercial property as security for the first time on this product, and pitching it at SME clients refinancing existing business debt — including Australian Taxation Office liabilities — consolidating debts, and funding additional business assets.
“A longer loan term isn’t just about borrowing capacity.”
“For us, it’s about making business lending easier and giving brokers another way to say yes to borrowers.”
Two separate statements by James Angus, Chief Executive, First Federal, quoted in Australian Broker, 5 November 2026The lender’s own broker page for the product sets out the envelope. The advertised starting rate is 7.24% per annum, variable, with rates stated as correct as at October 2026. Loan amounts run from $250,000 to $3,000,000, to a maximum 80% LVR, secured by a registered first mortgage over residential or commercial property, with exclusions noted and all locations considered. Repayments are principal and interest, or interest only for a maximum of five years on investment properties. The page also advertises low income verification requirements, no minimum credit score, unlimited cash out, unlimited debt consolidation including tax debts, extra repayments without penalty, and SMSF availability.
That combination — a 40-year term, 80% LVR, up to $3 million, light income verification, no credit score floor — is an unusually wide envelope by Australian standards. It deserves more scrutiny than a product bulletin usually gets.
What the extra decade buys, and what it costs
Take a $1,000,000 principal-and-interest loan at the advertised 7.24% starting rate and run it over 30 years against 40. The figures below are The Broker Times’ own calculation on that rate, excluding every fee.
| Measure | 30-year term | 40-year term |
|---|---|---|
| Monthly repayment | $6,814.98 | $6,389.39 |
| Total interest over the term | $1,453,393 | $2,066,908 |
| Interest as a multiple of principal | 1.45× | 2.07× |
| Principal retired after 10 years | $137,093 | $62,449 |
| Balance outstanding after 10 years | $862,907 | $937,551 |
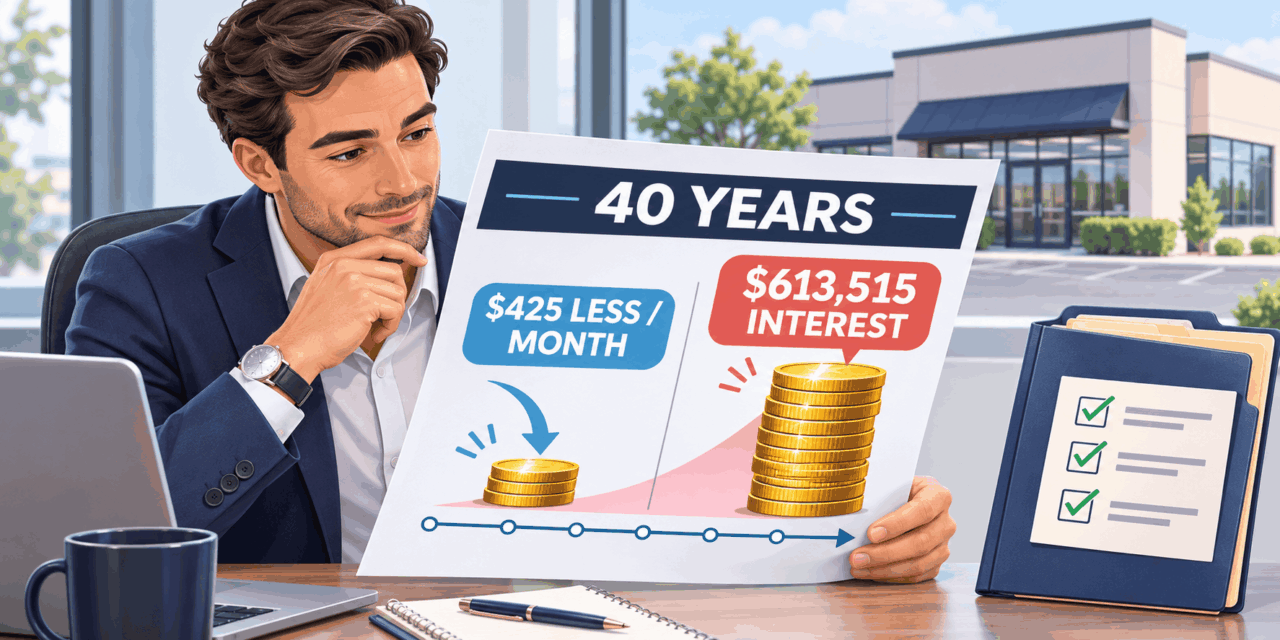
The trade is stark. The 40-year term lowers the monthly repayment by $425.59 — a touch over 6% — and raises total interest by $613,515. The client is buying roughly $425 a month of breathing room for something close to six hundred thousand dollars.
The ten-year column matters more than the headline, because ten years is the horizon on which most of these decisions are actually tested — a refinance, an equity release, a sale. On the 40-year schedule the borrower has retired $62,449 of principal after a decade, against $137,093 on the 30-year schedule. That is a $74,644 gap in equity built in the security property — which is, on these files, very often the family home. If the business needs to refinance, release equity, or sell into a softer market in year eight, the 40-year client is standing on a thinner slab.
Scale the numbers down and the logic holds. On the $250,000 minimum, the 40-year term saves $106.40 a month and adds $153,379 in interest. The ratio of relief to cost is roughly the same at every loan size: about one dollar of monthly relief for every $1,440 of extra interest.
The capacity claim needs one question answered
A longer term lifts borrowing capacity only to the extent the lender assesses the loan over that longer term. Hold the repayment constant at $6,000 a month and a 40-year amortisation at 7.24% supports about $939,056 against about $880,413 over 30 years — an uplift of roughly $58,600, or 6.7%. Useful at the margin. Not transformative, and nowhere near enough to rescue a file that is 20% short.
But that is the arithmetic of the contract term, not of the assessment. The lender’s published product page sets out the maximum term; it does not state the term over which servicing is assessed. Until you have that figure in writing from the lender or its credit team, the capacity benefit of the extra decade is unquantified. It is a single question, and it is the first one to ask:
- Over what term is servicing assessed on a 40-year First Business 40 loan?
- Is the assessment rate the actual rate, a floor, or the rate plus a buffer — and what figure applies today?
- Are the ongoing and risk fees included in the servicing calculation, or do they sit outside it?
If the loan is assessed over a shorter term than 40 years, the extra decade delivers cash-flow relief after settlement and no capacity at the point of assessment. That is still a legitimate reason to use it. It is a very different conversation from “this gets the deal over the line”, and the file should say which one you had.
The fee stack is where the pricing really sits
The 7.24% starting rate is not the cost of this loan. The lender’s published schedule adds an establishment fee of 0.75% on residential security (0.95% commercial), an application fee of the higher of $1,950 or 0.20% of the loan amount, a risk fee that steps from 0.95% below 60% LVR to 1.25% below 70% and 1.50% below 80% on residential security, a valuation at cost, a discharge fee of $880, and an ongoing fee of 0.10% per month.
On a $1,000,000 loan at 75% LVR against residential property, the published upfront fees come to $24,500 before valuation — about 2.45% of the loan. The ongoing fee is the one to pause on. At 0.10% per month it is 1.20% per annum. If it is charged on the loan balance, it adds about $1,000 a month at the outset and pushes the effective cost of funds from 7.24% toward roughly 8.44%. The lender’s page does not state what the 0.10% is calculated on, so that is a question to settle before you put a number in front of a client, not an assumption to make.
At an effective 8.44%, the 40-year repayment on $1m rises to about $7,285 a month — roughly $896 more than the rate-only figure, and more than twice the monthly saving the extra decade delivers. The term discount and the fee load move in opposite directions, and the fee load is larger.
The duty does not follow the loan
Here is the part that most placement conversations skip. ASIC’s own guidance states that the National Credit Code applies to credit contracts where, among other conditions, the credit is provided wholly or predominantly “for personal, domestic or household purposes” or “to purchase, renovate or improve residential property for investment purposes”. Business purposes are not on that list.
The best interests duty is tied to the same perimeter. ASIC’s Regulatory Guide 273 puts it in one sentence at RG 273.5:
“The best interests obligations apply only in relation to credit products that are regulated under the National Credit Act—that is, products provided to consumers for personal, domestic or household purposes or for the purchase or improvement of residential investment property.”
ASIC, Regulatory Guide 273: Mortgage brokers: Best interests duty, RG 273.5RG 273.133 confirms the duty is broad within that perimeter — it “applies to any credit assistance you provide”, including standalone credit products and products packaged with a mortgage. But RG 273.5 is what draws the perimeter in the first place. On ASIC’s own description of scope, a loan that is genuinely and predominantly for business purposes sits outside the Code and outside the duty, even where the security is the client’s own home and the term runs four decades.
So on a First Business 40 file, the obligations that would ordinarily shape a 40-year, 80% LVR recommendation — presenting more than one option, weighing features by benefit to the consumer, documenting why this product over the alternatives — are not legally required. Nothing in that makes the product improper. It does mean the discipline is yours to supply. The thinking you would be obliged to record on a regulated file is thinking the client needs just as much here, and the only thing that will put it on the file is you deciding to.
Two cautions on the characterisation itself. First, whether a loan is genuinely business purpose is a question of fact about the substance of the transaction, not a question of which form was signed. The Broker Times reported in October that AFCA had found a broker-arranged business purpose declaration ineffective where the broker knew the funds were clearing home loan arrears. Second, RG 273.14 records ASIC’s position that the best interests obligations “cannot be avoided by any notice or disclaimer provided to or signed by the consumer”. None of this is a substitute for your licensee’s view on a specific file.
Section 158T is the other half of that sentence
If a longer term, a bigger fee pool and no best interests duty sounds like an incentive, the legislation anticipated it. RG 273.180 describes an anti-avoidance provision whose effect is that a person must not enter into or begin to carry out a scheme if it would be concluded they did so for the sole or non-incidental purpose of avoiding any provision of Part 3-5A, and the scheme has achieved or would achieve that purpose. RG 273.181 notes a person may be liable for a civil penalty for breaching section 158T.
ASIC also sets out how it intends to use it. At RG 273.184 it says it is “more likely to scrutinise schemes that appear to have no commercial purpose other than to avoid the application of the best interests duty, conflict priority rule and conflicted remuneration provisions”. At RG 273.185 it says it is “unlikely to scrutinise schemes that are normal commercial transactions conducted in the ordinary course of business”.
Read together, those two paragraphs are a reasonably clear map. A genuine business borrower refinancing genuine business debt over a long term is an ordinary commercial transaction. A consumer file dressed as a business file to reach a product with a longer term, a lighter verification standard and no duty attached is the other thing. The distinguishing feature is commercial purpose, and commercial purpose is something you evidence at the time, not something you argue later.
Where the product genuinely earns its place
None of the above is an argument against the product. There is a real and growing problem it speaks to directly.
The Australian Taxation Office, responding on 30 June 2026 to an Australian National Audit Office report on its management of small business collectable debt, confirmed that small business debt accounts for around 66% of total collectable debt, with around $35.9 billion owed as at 30 June 2025. The ATO described that debt as “largely undisputed and predominantly self-reported” and said “addressing this debt is critical to maintaining a level playing field”. Australian Broker, citing ANAO figures, reported the small business collectable tax debt had risen 118% since 2018–19.
An unsecured ATO payment arrangement, or short-term unsecured business credit at a factor rate, is expensive and short. A secured facility at a single-digit rate, amortised over a long term, consolidating a tax liability into something a business can actually carry, is a materially better structure for a borrower with usable property equity and a viable business. That is the case for First Business 40, and it is a decent one.
The place it stops being a decent case is where the 40 years is doing the work that the business plan should be doing. If the business only services the debt at a 40-year amortisation with light income verification, the term is not solving a cash-flow timing problem — it is concealing a serviceability problem, against the client’s home, for four decades. That distinction is the whole judgement call on these files, and no regulation is going to make it for you.
What to review on your next business-purpose file
A seven-point file review for long-term business lending
- Characterise the purpose in substance, in writing. What the funds actually do, in your words, with the evidence you relied on. Not just the declaration.
- Get the assessment term in writing. Ask the lender over what term servicing is assessed, and at what rate. Record the answer and the date you got it.
- Price the fee stack, not the rate. Establishment, application, risk fee at the actual LVR band, valuation, ongoing fee — and confirm what the ongoing fee is calculated on.
- Show the term comparison. Put the 30-year and 40-year repayment and total interest side by side for the actual loan amount, and note why the longer term was chosen anyway.
- Note the equity consequence. How much principal is retired by year five and year ten on the chosen term, especially where the security is the client’s residence.
- Record the alternatives you considered. Shorter term, lower LVR, a different lender, a shorter-dated facility with a refinance plan. You are not obliged to on a business file. Do it anyway.
- Diarise the review. A 40-year facility with extra repayments permitted and no penalty is a product that should be actively managed, not set and forgotten. RG 273.168 notes that how long records should be kept may vary depending on factors such as the loan term — the same logic applies to how long you keep the client in view.
Key takeaways
- First Federal extended its business loan term from 30 to 40 years on 5 November 2026, at up to $3m, 80% LVR, and an advertised 7.24% starting rate.
- On a $1m loan, the extra decade lowers the repayment by $425.59 a month and raises total interest by $613,515. After ten years the borrower has retired $62,449 of principal instead of $137,093.
- Holding the repayment constant, the 40-year amortisation supports about 6.7% more debt — but only if the lender assesses over 40 years, which its published page does not state.
- Published upfront fees total about $24,500 on a $1m loan at 75% LVR before valuation, with an ongoing fee of 0.10% per month on top.
- RG 273.5 confines the best interests obligations to credit regulated under the National Credit Act, so a genuine business-purpose loan sits outside the duty — while section 158T targets schemes designed to get there.
Questions brokers are asking
Does the best interests duty apply to a business loan secured by a home?
ASIC states at RG 273.5 that the best interests obligations apply only in relation to credit products regulated under the National Credit Act — that is, credit for personal, domestic or household purposes, or for the purchase or improvement of residential investment property. On that statement of scope, credit genuinely and predominantly for business purposes sits outside the duty, regardless of what secures it.
That is general information, not advice on your file. Whether a particular transaction is genuinely business purpose is a question of fact, and the consequences of getting it wrong sit with you and your licensee. Confirm the characterisation with your licensee or compliance adviser before you rely on it.
So is a business purpose declaration enough on its own?
No. The declaration is a form; the purpose is a fact. The Broker Times reported in October that AFCA had found a broker-arranged business purpose declaration ineffective in circumstances where the broker knew the funds were clearing home loan arrears. ASIC also records at RG 273.14 that the best interests obligations cannot be avoided by any notice or disclaimer provided to or signed by the consumer.
The practical implication is that your file should evidence the purpose independently of the declaration.
How much extra capacity does a 40-year term really deliver?
At a constant $6,000 monthly repayment and 7.24%, a 40-year amortisation supports about $939,056 against about $880,413 over 30 years — roughly 6.7% more. That is the arithmetic of the contract term.
The capacity you can actually use depends on the term the lender assesses over, which the published product page does not state. Ask before you model it.
Is 7.24% the real cost of the loan?
It is the advertised starting rate on the lender’s broker page, stated as correct as at October 2026, on a variable product. The published schedule adds establishment, application and risk fees upfront and an ongoing fee of 0.10% per month. On a $1m loan at 75% LVR the upfront fees alone come to about $24,500 before valuation.
If the 0.10% monthly fee is charged on the balance, it is 1.20% per annum, which would take the effective cost closer to 8.44%. The page does not specify the basis, so confirm it with the lender before quoting a client.
When does a 40-year business loan clearly make sense?
Where a viable business with usable property equity is carrying expensive short-dated debt — an ATO liability, a factor-rate facility, accumulated trade debt — and refinancing it into a secured, amortising facility materially improves the business’s cash position. The ATO has confirmed around $35.9 billion of small business collectable debt as at 30 June 2025, so the problem is widespread.
It makes much less sense where the business only services the debt because the term is 40 years. At that point the term is covering a serviceability gap rather than a timing gap.
- First Federal, First Business 40 broker product page (rates stated correct as at October 2026)
- Australian Broker, “First Federal stretches business loan terms to 40 years”, 5 November 2026
- Reserve Bank of Australia, Cash Rate Target statistics (4.85% effective 4 November 2026)
- ASIC, Regulatory Guide 273: Mortgage brokers: Best interests duty (RG 273.5, 273.14, 273.133, 273.168, 273.180–273.185)
- ASIC, National Credit Code guidance (application of the Code)
- Australian Taxation Office, response to the ANAO audit on management of small business collectable debt, 30 June 2026
Breaking news for modern brokers
Policy shifts, lender moves and the compliance detail behind them — twice a day, written for brokers.
More at The Broker Times →Broker tools
Long-Term Business Lending: Cost Explorer and File Check
Two things to do before you place a 40-year business facility: price what the term actually costs, and decide what your file will carry when no duty requires it.
What does the extra decade cost this client?
Enter the file’s numbers and compare a shorter amortisation against the longer one. Principal and interest, fees excluded, rate held constant for illustration.
What will your file carry?
On a genuine business-purpose loan, RG 273.5 means the best interests duty does not apply. These are the items a broker would choose to record anyway. Tick what is already on the file.
0 of 7 on the file
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.