Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
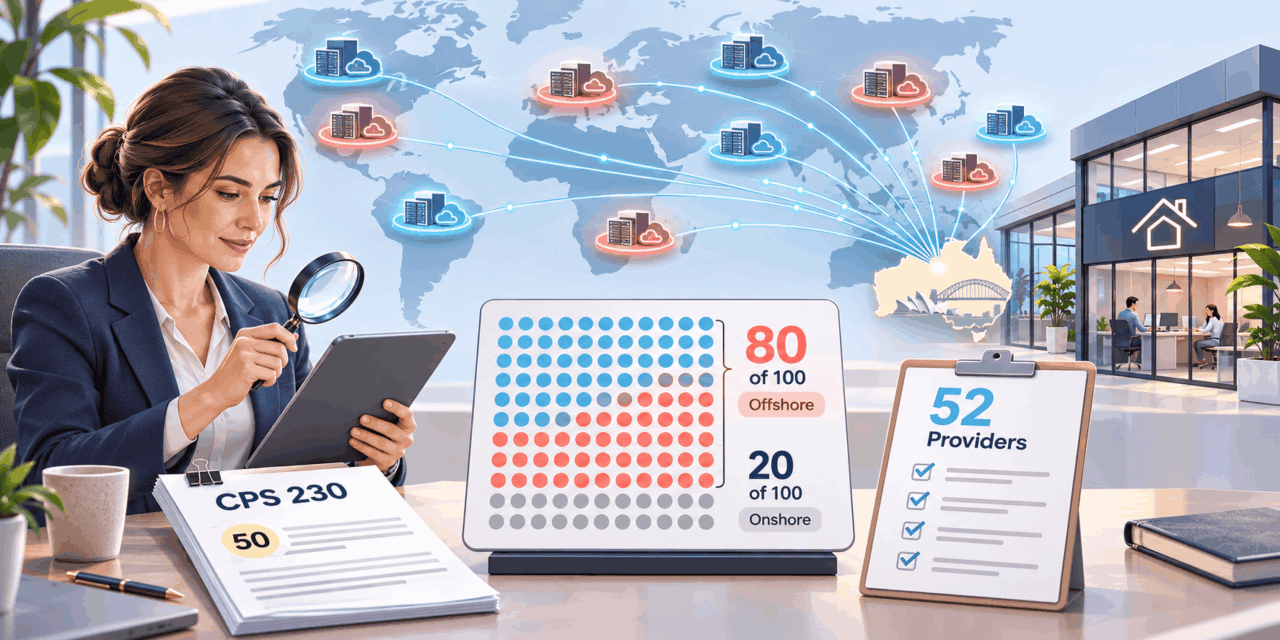
This audio version covers: 80 of the Top 100 Material Service Providers Sit Offshore. CPS 230 Paragraph 50 Names ‘Mortgage Brokerage’ — and the Median Bank Lists 52
Mortgage Brokerage Is a Named Service in CPS 230
APRA’s System Risk Outlook of 12 November 2026 maps how concentrated the service-provider chain behind Australian banks has become. The standard behind that map names broking directly.
The numbers APRA published
Material service providers, by industry (median, 2025)
Where a broker sits in the chain
The ADI
Holds every CPS 230 obligation. Must keep a register of material service providers (¶49) and submit it to APRA annually (¶51).
Mortgage brokerage
¶50 requires an ADI to classify a provider of credit assessment, funding and liquidity management, or mortgage brokerage as material — “unless it can justify otherwise”.
Usually the aggregator
Signs the formal agreement with the minimum terms set by ¶54, including data ownership, audit access, liability and termination rights.
Your brokerage
¶54(d) requires disclosure of sub-contracting the provider materially relies on. ¶54(e) puts liability for sub-contractor failure on the service provider above you.
What it is — and is not
What CPS 230 does do
- Names mortgage brokerage as presumptively material for an ADI (¶50)
- Requires due diligence that assesses geographic location and concentration (¶53)
- Requires formal agreements with minimum terms (¶54)
- Gives APRA access and on-site visit rights at the service provider (¶55)
- Requires ongoing monitoring of both parties’ compliance (¶58)
What it does not do
- Impose any direct obligation on a broker or brokerage — it binds APRA-regulated entities
- Make mortgage brokerage a critical operation; ¶36(a) lists payments, deposit-taking and management, custody, settlements and clearing
- Trigger the 20-business-day APRA notification in ¶59(a), which is keyed to critical operations
- Replace or alter your obligations under the NCCP Act or the best interests duty
Four answers worth having in writing
Where does client data physically live? By country, not by brand name. Footnote 16 turns on where work is performed, not where a vendor is incorporated.
What do you materially depend on? Which systems, if unavailable for a week, would stop you submitting files.
What happens when it breaks? A one-page continuity answer for a multi-day CRM or platform outage.
Who owns your client data? And what happens to it if you change aggregator. ¶54(b) puts ownership and control of data in the agreement above you.
The takeaway
Being named in paragraph 50 is scope, not status. The obligation is your lender’s, but it reaches you through contracts, due diligence and sub-contractor terms — and APRA has now said it intends to formalise its data collection for material service providers. Expect the questions to become more structured, not fewer.
80 of the Top 100 Material Service Providers Sit Offshore. CPS 230 Paragraph 50 Names ‘Mortgage Brokerage’ — and the Median Bank Lists 52
APRA’s November System Risk Outlook maps how concentrated the service-provider chain behind Australian banks has become. The prudential standard that produced that map names mortgage brokerage directly — and the regulator has just said it intends to collect more data on it.
APRA published its latest System Risk Outlook on 12 November 2026. Most of the coverage went where you would expect — housing prices, household debt, whether competition between lenders is quietly loosening credit standards.
The paragraphs worth a broker’s time sit further down, in the section on material service providers. APRA reports that of the top 100 material service providers named by APRA-regulated institutions, 80 are headquartered or principally operate outside Australia, that some individual providers support institutions holding more than half of all APRA-regulated financial assets, and that the median significant bank identified 52 material service providers in 2025.
None of that is about broking. But the standard those numbers come from is. Prudential Standard CPS 230 Operational Risk Management contains a paragraph that names mortgage brokerage by name — as a service an authorised deposit-taking institution must classify as material, unless it can justify otherwise.
That paragraph has been in force since July 2025. What changed this month is that APRA said it intends to formalise its data collection for material service providers — the register your lender already files once a year is about to get more structured. This is a reasonable week to understand where you sit in it.
What paragraph 50 actually says
CPS 230 is made under section 11AF of the Banking Act 1959, among other provisions, and it commenced on 1 July 2025. Paragraph 7 gave lenders a transition for contracts already on foot: those arrangements came into scope at the earlier of the contract’s next renewal date or 1 July 2026. On any reading, that transition has now passed.
Paragraph 49 sets the general rule. An APRA-regulated entity must identify and maintain a register of its material service providers, and manage the material risks of using them. Material service providers are defined as “those on which the entity relies to undertake a critical operation or that expose it to material operational risk.”
Paragraph 50 then removes the guesswork for certain services. An APRA-regulated entity must, at a minimum, classify a provider of the following services as a material service provider, “unless it can justify otherwise” — and for an ADI, the listed services are “credit assessment, funding and liquidity management and mortgage brokerage.”
“for an ADI: credit assessment, funding and liquidity management and mortgage brokerage” — CPS 230, paragraph 50
Mortgage brokerage is not an inference drawn from a general risk test. It is a named category, sitting alongside credit assessment and funding, in a standard that governs how every bank on your panel manages the firms it depends on.
What it does not say
This is where precision matters more than headlines, so it is worth being exact about the limits.
First, the obligation is the bank’s. CPS 230 applies to APRA-regulated entities — ADIs, insurers, superannuation licensees. It does not impose a duty on you. Your own obligations as a broker continue to come from the National Consumer Credit Protection Act 2009, your licensee or credit representative arrangements, and ASIC’s guidance on the best interests duty in RG 273. CPS 230 is prudential regulation of your lender. It is not a second compliance regime pointed at your file notes.
Second, “material” is not the same as “critical”. CPS 230 keeps two separate lists. Paragraph 36(a) sets out the business operations an ADI must classify as critical operations unless it can justify otherwise: payments, deposit-taking and management, custody, settlements and clearing. Mortgage brokerage is not on that list. It appears on the material service provider list in paragraph 50, which is a different test with different consequences.
That distinction carries weight. Paragraph 59(a) requires an ADI to notify APRA as soon as possible, and not more than 20 business days after, entering into or materially changing an agreement for a service it relies on to undertake a critical operation. Paragraph 60 requires internal audit to review proposed material arrangements involving the outsourcing of a critical operation. Both hooks are keyed to critical operations — so neither attaches to a mortgage brokerage arrangement by force of paragraph 50 alone.
“Material” and “critical” are separate tests in CPS 230. Mortgage brokerage is on the material list in paragraph 50, not the ADI critical-operations list in paragraph 36(a). Conflating the two overstates what the standard requires.
Anyone telling you that CPS 230 means your aggregator agreement must be reported to APRA within 20 business days is reading across two lists the standard deliberately keeps apart. The narrower position is still significant: mortgage brokerage is a presumptively material service, which triggers the register, the due diligence, the contract terms and the monitoring — not the critical-operations notification.
Where brokers actually sit in the chain
In practice, a bank’s counterparty for “mortgage brokerage” is usually not an individual broker. It is the aggregator, or sometimes a large brokerage contracting directly. That is the arrangement that goes on the register, which paragraph 51 requires be submitted to APRA annually. Which puts most broker businesses one rung further down — and CPS 230 has language for that rung too.
Paragraph 54 requires a formal, legally binding agreement for every material arrangement, with a set of minimum terms. Two of them reach down the chain. Subparagraph (d) requires the agreement to “require notification by the service provider of its use of other material service providers that it materially relies upon in providing the service to the APRA-regulated entity through sub-contracting or other arrangements.” Subparagraph (e) requires “the liability for any failure on the part of any sub-contractor to be the responsibility of the service provider.”
Read together, the commercial logic is obvious. The aggregator carries contractual liability upstream for failures that happen downstream. That is not a theory about how aggregators might behave — it is a term the standard requires in the agreement. It is also the most direct explanation available for why accreditation questionnaires, security attestations and re-accreditation reviews have grown more demanding: the entity asking you is answering to a clause it did not write.
“require the liability for any failure on the part of any sub-contractor to be the responsibility of the service provider” — CPS 230, paragraph 54(e)
The standard also uses the term “fourth party”, defined in a footnote as “a party that a service provider relies on in delivering services to an APRA-regulated entity.” Paragraph 48 requires the bank’s service provider management policy to cover risks associated with fourth parties that material service providers rely on to deliver a critical operation — tied, again, to critical operations. The vocabulary exists; the obligation around it is scoped.
The clauses that flow downhill
If you want to know why a lender’s onboarding pack asks what it asks, the answers are mostly in paragraphs 53 to 58.
Paragraph 53 requires the bank, before entering into or materially modifying a material arrangement, to undertake appropriate due diligence — including an appropriate selection process and an assessment of the provider’s ability to deliver the service on an ongoing basis — and to assess the financial and non-financial risks of relying on that provider, “including risks associated with geographic location or concentration of the service provider(s) or parties the service provider relies on in providing the service.”
Paragraph 54 sets the minimum contract terms: services and service levels; the rights and responsibilities of each party, including ownership of assets, ownership and control of data, dispute resolution, audit access, liability and indemnity; provisions ensuring the entity can meet its legal and compliance obligations; the sub-contracting terms above; a force majeure provision; and termination rights.
Paragraph 55 is the one brokers tend to find most surprising. The formal agreement must include provisions that allow APRA access to documentation, data and other information related to the provision of the service; allow APRA the right to conduct an on-site visit to the service provider; and ensure the service provider agrees not to impede APRA in fulfilling its duties as prudential regulator.
Paragraph 56 requires the bank to identify and manage risks that could affect ongoing provision, manage step-in and contagion risk, ensure it can execute its business continuity plan, and ensure it can conduct an orderly exit. Paragraph 58 requires ongoing monitoring and senior management reporting, including regular assessment of performance against agreed service levels, the effectiveness of controls, and “compliance of both parties with the service provider agreement.”
Both parties. Monitoring under CPS 230 is not a one-off questionnaire at accreditation — it is a standing obligation on the lender to keep assessing the arrangement, and through the chain, to keep asking.
The offshoring question
One definition deserves separate attention, because a growing number of Australian brokerages run loan processing, document collection or client administration through offshore teams.
Footnote 16 defines a material offshoring arrangement as a material arrangement where the service provided is undertaken outside Australia. It then draws a line that is easy to get backwards: offshoring “includes arrangements where the service provider is incorporated in Australia, but the physical location of the service being provided is undertaken outside Australia”, and it “does not include arrangements where the physical location of a service is performed within Australia, but the service provider is not incorporated in Australia.”
The test is where the work happens, not where the company is registered. Paragraph 59(b) requires the ADI to notify APRA prior to entering into any material offshoring arrangement, or when a significant change is proposed, “including in circumstances where data or personnel relevant to the service being provided will be located offshore.”
That notification duty is the bank’s, about the bank’s own arrangements — not a filing obligation on your brokerage. But it explains why questions about where your processing staff sit and where client data is stored have started appearing in aggregator and lender due diligence. APRA’s November findings — 80 of the top 100 providers headquartered or principally operating offshore, and a warning that “geopolitical instability could further disrupt access to overseas providers and complicate recovery” — are the concentration the standard is trying to make visible.
Why the questions are about to get more structured
The November System Risk Outlook is candid that APRA’s view of this chain is still incomplete. It says information collected under CPS 230 is improving its visibility of material service providers supporting critical operations, and that further work is needed to assess each provider’s systemic importance and substitutability, including recovery options.
Among its stated supervisory priorities is “improving visibility of system-wide exposures”, including “formalising APRA’s data collection for material service providers”. That is the sentence with the forward edge. A register filed annually in a bank’s own format is harder to aggregate than a structured collection — and when the collection becomes structured, the questions that generate it tend to become standardised too. Standardised questions arrive as a form, with fields, on your desk.
The same document sets out APRA’s AI priorities, including deeper supervisory engagement on how institutions manage AI risk and examining preparedness for AI-amplified cyber threats. It notes AI is accelerating the discovery and exploitation of software vulnerabilities, leaving less time to patch. APRA and ASIC ran nine frontier AI roundtables in June and July 2026, involving more than 380 entities and more than 600 attendees, with managing shared dependencies among the five priorities identified. APRA has also said its 2027 System Stress Test will explore how AI-driven economic disruption could affect banks, superannuation funds and life insurers.
For a broker, the practical read is simple. Operational resilience and third-party risk are where APRA has told the market it is investing supervisory attention. Lenders will respond by tightening what they ask of the chain, because that is the lever they have.
What to review this week
None of the following is a legal obligation on your brokerage. It is what CPS 230 requires your lender to have covered, reframed as the questions you are most likely to be asked. Treat it as preparation, not compliance.
- Find your contractual position. Read the sub-contracting, liability and indemnity clauses in your aggregator or lender agreement. Paragraph 54(e) pushes liability for sub-contractor failure onto the service provider above you. Know what that means for your business before someone explains it to you during an incident.
- Write down where client data physically lives. Not the brand name of the software — the country. CRM, document storage, email, any offshore processing or virtual assistant arrangement. Footnote 16 turns on where the work is performed, not where the vendor is incorporated.
- List your own material dependencies. The median significant bank identified 52. Your number will be far smaller, but the exercise is the same: which systems, if unavailable for a week, would stop you submitting files? Name them.
- Have a one-page continuity answer. Paragraph 56 requires lenders to satisfy themselves they can execute their BCP and exit an arrangement in an orderly way. The downstream version: what do you do if your CRM or aggregator platform is down for days? A written answer beats a confident one.
- Check your audit access and data ownership terms. Paragraph 54(b) requires ownership and control of data and audit access to be addressed upstream. Make sure you know who owns your client data under your current agreement, and what happens to it if you move.
- Review your security fundamentals honestly. Multi-factor authentication everywhere, a current list of who has access to what, offboarding that actually revokes credentials. “Strong cyber fundamentals” was the first of the five priorities from the APRA and ASIC roundtables, and it is the part of this that is entirely within your control.
- Ask your aggregator one question. Whether your brokerage is identified in any lender’s CPS 230 register or sub-contractor disclosures, and what information they provide about your business when a lender asks. The answer tells you how much of this reaches you directly.
What to watch next
Whether APRA’s formalised data collection turns up as a new reporting standard or a change to existing collections, since that determines how much flows downhill. Whether the detailed findings of the 2026 Trans-Tasman Stress Test, which APRA says will be published later this year, address third-party and cyber dependencies in the mortgage chain. And whether the 2027 System Stress Test scoping touches origination channels at all.
The practical significance
It would be easy to read paragraph 50 as a status upgrade — proof that broking is now recognised as critical financial infrastructure. That reading is flattering and mostly wrong. Being named as a presumptively material service provider is not recognition. It is scope.
The useful reading is narrower. A standard that governs every bank on your panel names mortgage brokerage as a service that must be treated as material unless the bank can justify otherwise. It requires formal agreements with specified terms, due diligence that explicitly considers geographic concentration, liability for sub-contractor failure sitting above you, regulator access rights, and continuous monitoring of both parties’ compliance. And the regulator has just said it intends to see that chain more clearly than it does now.
The brokers who find the next two years easiest will be the ones who can answer where their data sits, what they depend on, and what they do when it breaks — in writing, before anyone asks. That is not a compliance project. It is a page.
Because this touches both prudential standards and your own credit licensing obligations, confirm anything specific to your business with your licensee or aggregator’s compliance team.
Key takeaways
- The numbers. APRA’s System Risk Outlook of 12 November 2026 reports that 80 of the top 100 material service providers named by APRA-regulated institutions are headquartered or principally operate outside Australia, and that the median significant bank identified 52 material service providers in 2025.
- The paragraph. CPS 230 paragraph 50 requires an ADI to classify a provider of credit assessment, funding and liquidity management, or mortgage brokerage as a material service provider — “unless it can justify otherwise”.
- Whose obligation it is. CPS 230 binds APRA-regulated entities, not brokers. It reaches broker businesses indirectly, through due diligence, contract terms and sub-contractor disclosure — not as a compliance duty of their own.
- The limit worth knowing. Mortgage brokerage is not on the ADI critical-operations list in paragraph 36(a), so the 20-business-day APRA notification in paragraph 59(a) and the internal audit review in paragraph 60 are not triggered by paragraph 50 alone.
- What changes next. APRA has listed “formalising APRA’s data collection for material service providers” among its supervisory priorities. Structured collection upstream tends to produce standardised questions downstream.
Broker questions answered
No. CPS 230 is made under provisions including section 11AF of the Banking Act 1959 and applies to APRA-regulated entities — ADIs, insurers and superannuation licensees. It does not impose duties on credit licensees or credit representatives.
Your own obligations continue to come from the National Consumer Credit Protection Act 2009, your licensee or credit representative arrangements, and ASIC’s guidance on the best interests duty. What CPS 230 changes is what your lenders must do about the firms they rely on — which is why the questions reach you.
Probably not directly. A bank’s counterparty for mortgage brokerage is usually the aggregator, or in some cases a large brokerage contracting directly. That is the arrangement that goes on the register submitted to APRA annually under paragraph 51.
Most broker businesses sit a rung below, as sub-contractors. Paragraph 54(d) requires the agreement to compel disclosure of sub-contracting the provider materially relies on, and paragraph 54(e) places liability for sub-contractor failure on the service provider above you. Your aggregator can tell you what, if anything, it discloses about your business.
Not for you. Paragraph 59(b) requires the ADI to notify APRA before entering into any material offshoring arrangement of its own, or when a significant change is proposed, including where data or personnel relevant to the service will be located offshore.
The definition is worth knowing, because it is easy to get backwards. Footnote 16 says offshoring includes arrangements where the provider is incorporated in Australia but the service is physically performed outside Australia, and does not include arrangements where the service is performed within Australia but the provider is not incorporated here. The test is where the work happens.
CPS 230 requires the lender to do specific things before and during a material arrangement: due diligence including an assessment of risks associated with geographic location or concentration (paragraph 53); a formal agreement covering service levels, data ownership and control, audit access, liability and termination (paragraph 54); provisions allowing APRA access to documentation and data and the right to an on-site visit at the service provider (paragraph 55); and ongoing monitoring of performance, control effectiveness and both parties’ compliance (paragraph 58).
Each of those has to be satisfied with information from somewhere. The entity asking you is answering to clauses it did not write.
They are separate lists with separate consequences. Paragraph 35 defines critical operations as processes which, if disrupted beyond tolerance levels, would have a material adverse impact on customers or the entity’s role in the financial system. Paragraph 36(a) requires an ADI to classify payments, deposit-taking and management, custody, settlements and clearing as critical operations unless it can justify otherwise.
Material service providers are defined in paragraph 49 as those the entity relies on to undertake a critical operation or that expose it to material operational risk. Mortgage brokerage appears on the paragraph 50 material list, not the paragraph 36(a) critical list.
- APRA, System Risk Outlook, November 2026 (published 12 November 2026)
- APRA, Prudential Standard CPS 230 Operational Risk Management, July 2025 (commenced 1 July 2025)
Breaking news for modern brokers
Regulatory change, lender policy shifts and market data — read through the lens of what it does to your files.
More at The Broker Times →Third-Party Readiness Check for Brokers
Seven questions drawn from what CPS 230 requires your lender to cover. Answer honestly — the point is to find the gap before a questionnaire does.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.