Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: A Bank Traced About $191,000 Into an Unaccredited Broker’s Account. The Tribunal Ruled Only on the Banker — the Referral Boundary Is What Brokers Should Read
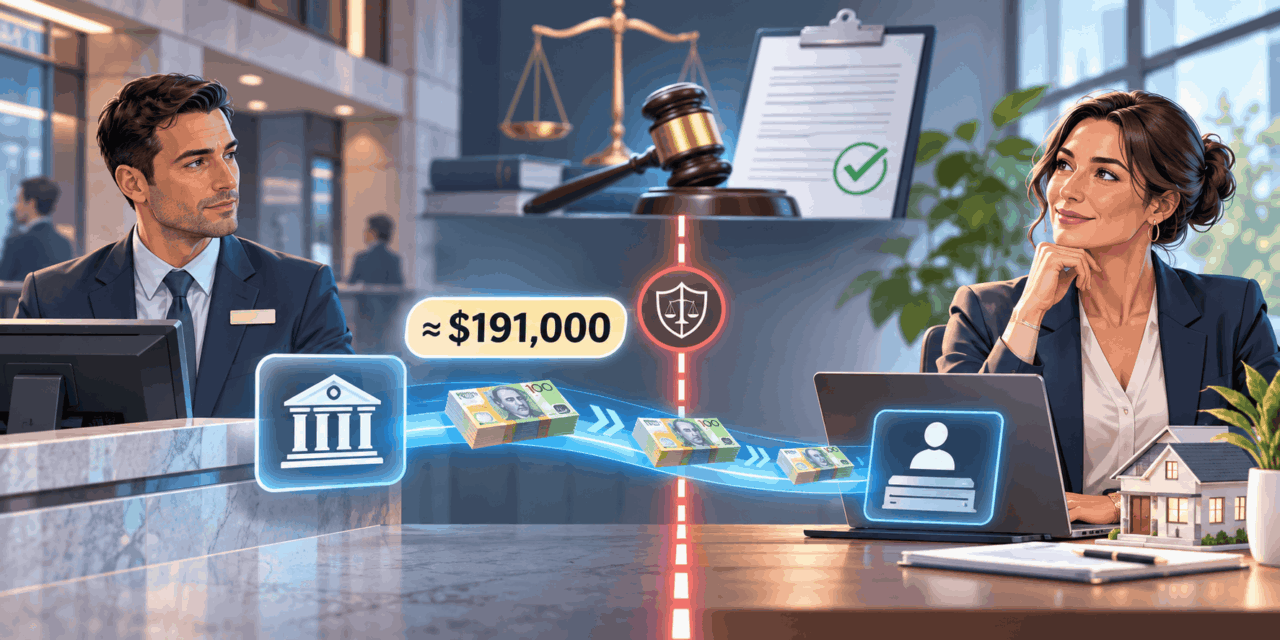
How One Bank Reconstructed a Referral Relationship
A Fair Work Commission decision published this month sets out, step by step, the evidence a major lender assembled about who was really introducing its loans — and the referral boundary that sat underneath it.
The payments the bank traced
Reported transaction descriptions included “service fee” and “referral fee”. The three streams add to about $191,000 between August 2023 and February 2025. Figures as reported by Australian Broker, Mortgage Professional Australia and The Adviser.
The referral book under review
The evidence trail, in order
- 19 November 2024An anonymous internal report names the banker and four other employees. A preliminary review clears him.
- Late 2024 – early 2025The bank widens the review to the loans he refinanced from his former employer, and a pattern appears: self-employed borrowers, two referral partners, one accounting firm.
- April 2025Both referral partners are removed from the bank’s referral program.
- 14 May 2025At interview he says he has “no idea” who the broker is. Forensic analysis of his work phone finds a saved contact whose number matches the broker’s own customer profile at the bank.
- 29 July 2025He is dismissed. He lodges an unfair dismissal claim on 18 August 2025.
- 2 November 2026The Fair Work Commission dismisses the claim, finding the dismissal “wholly justified and not unfair”.
What the decision did not find
This was an employment case, not a fraud case. The Commission ruled on whether one bank was entitled to dismiss one employee. It made no finding that kickbacks were paid.
The broker was not a party. No finding was made against him, against either referral partner, or against the accounting firm. The bank’s suspicion about how clients were being introduced is recorded as the bank’s concern — not as a conclusion of the Commission or any court.
Four signals that put a file into a pattern
One source, one accountant
Every borrower from a single referrer arriving with financials prepared by the same firm.
Third-party money near settlement
Payments described as “service fee” or “referral fee” moving around the time a loan is processed.
Self-employed, but wages on the statements
Regular salary credits sitting in the bank statements of a borrower assessed as self-employed.
Mixed channels in one chat
A group chat combining lender staff, a referrer and an unaccredited third party, carrying leads and approvals.
The broker’s own three checks
Know the boundary
A referrer may point a client to you and disclose what they are paid. Once they shape the product or lender choice, that is credit assistance.
Verify at the source
Take income documents and financials from the client or the issuer, not from the referrer’s inbox.
Write the reason down
Record why the recommendation suits the client, independently of where the client came from.
The takeaway
A referral arrangement that works commercially can still fail on paper. The documents that decided this case — a phone contact list, a group chat, bank statements and a payment trail — are the same records that would be pulled from a broker’s file. Brokers should confirm their referral arrangements with their licensee or aggregator’s compliance team.
A Bank Traced About $191,000 Into an Unaccredited Broker’s Account. The Tribunal Ruled Only on the Banker — the Referral Boundary Is What Brokers Should Read
A Fair Work Commission decision handed down on 2 November sets out, in unusual detail, how a major lender reconstructed who was really introducing its loans. For brokers, the value is not the verdict. It is the evidence list.
Unfair dismissal decisions rarely matter to mortgage brokers. This one does — not because of who won, but because the published reasons walk through exactly which records a lender pulled, in what order, to work out whether a referral relationship was what it appeared to be. Those are the same records that sit in a broker’s own file.
What was actually decided — and what was not
On 2 November 2026, Deputy President Gerard Boyce of the Fair Work Commission dismissed an unfair dismissal claim brought by a former senior home lending executive at the Commonwealth Bank. The bank had dismissed him on 29 July 2025; he lodged his claim on 18 August 2025. Boyce found the dismissal “wholly justified and not unfair”, and assessed the applicant’s evidence as “wholly unreliable” — describing it, in a line that has travelled through the trade press this week, as “a chaotic collection of lies, nonsense, poorly matched ideas, and manufactured responses”.
Before going further, it is worth being precise about the limits of that decision, because the commentary around it has been looser than the record supports.
Three things this decision is not
It is not a fraud finding. The Commission was deciding whether one employer was entitled to dismiss one employee. It made no finding that kickbacks were paid.
It is not a finding against a broker. The broker at the centre of the bank’s concerns was not a party to the proceedings. No finding was made against him, against either of the two referral partners, or against the accounting firm that prepared many of the borrowers’ financials. What the bank suspected is recorded as the bank’s suspicion.
It is not a regulatory ruling. Nothing in it changes a broker’s obligations. It is an employment decision that happens to describe a credit process in detail.
With that said, the detail is the point. Reporting by Australian Broker, Mortgage Professional Australia and The Adviser sets out a sequence that most brokers never get to see: how a single anonymous tip became a reconstructed referral network.
The evidence trail a lender can assemble
It started with an anonymous report to the bank’s internal whistleblower service on 19 November 2024, naming the executive and four other employees. A preliminary review cleared him. That is the first lesson, and it is not a comfortable one: the initial look found nothing.
What found something was widening the lens. The bank reviewed the loans the executive had refinanced across from his previous employer, and a shape emerged. A high proportion of the borrowers were self-employed. They had been introduced by two accredited referral partners. And many of them arrived with company financials prepared by the same accounting firm.
None of those three facts is wrong on its own. A broker or banker with a niche will naturally see clustered borrower types, repeat introducers and familiar accountants. The signal was the three appearing together, repeatedly, inside one person’s book. Across the two partners, reporting puts the volume at 23 customers, 35 applications and 28 funded loans; the larger of the two partners alone accounted for 17 customers and 29 applications between April 2024 and January 2025, 22 of which were funded.
From there the bank moved to transactional evidence, and traced money into the account of a broker who was not an accredited referrer under its program. Three streams were reported: six payments from the first referral partner totalling $81,146.44; six from the second totalling $61,441.62; and $48,595.50 from five of the referred customers themselves, moving around the time their loans were processed or approved. Transaction descriptions included “service fee” and “referral fee”. Together the three streams come to roughly $191,000 between August 2023 and February 2025.
Then came the device evidence. Asked at a 14 May 2025 interview who the broker was, the executive said he had “no idea”. Forensic analysis of his work phone found a saved contact whose number matched that broker’s own customer profile at the bank, along with messages and missed calls. One customer had texted to thank the executive and the broker together. A later explanation — that the man was someone he knew by a different surname — was rejected by Boyce as “unbridled nonsense” and a “complete fabrication”.
Finally, the channel itself. The executive admitted joining a group chat, named after the referral partner, that included the approved referrer and the unaccredited broker, and admitted that loan leads arrived there and that he reported back whether loans were approved or settled. He had deleted the chat and declined to hand over his personal phone. Boyce observed that what was actually discussed in it will never be known.
Where a referral stops being a referral
The structural issue underneath this case is the one brokers deal with every week: the line between a referral and credit assistance.
Under the National Consumer Credit Protection regime, a narrow licensing exemption lets a referrer do very little — in substance, tell a consumer that a licensee can help with credit and pass on how to contact them, while disclosing any benefit the referrer receives for doing so. The exemption is deliberately thin. Once a third party starts shaping which lender or which product the client should pursue, the activity looks like credit assistance, and credit assistance requires a licence or an appointment as a credit representative. The precise conditions are set out in the regulations and are easy to breach by accident, so the sensible step is to have your licensee or aggregator’s compliance team confirm how each of your arrangements is documented rather than relying on how it has always worked.
Lenders police their side of that line through their own program rules. In this case, the bank’s referral program reportedly prohibits mortgage brokers and builders from participating directly or indirectly, restricts contact with the referrer during assessment to the bank’s own business development staff, and prohibits sharing customer information with referrers. The group chat cut across all three.
Why the “indirectly” matters. A program that bars brokers “directly or indirectly” is not satisfied by a broker simply not being the named referrer. If a broker is in practice sourcing the clients and an accredited entity is the one on the paperwork, the arrangement is the thing being tested, not the label on it.
For brokers, the practical read-across is about introducers flowing the other way. If a referrer sends you clients and is also being paid by those clients, or is also preparing their financials, or is also talking to a lender about their files, your arrangement has more moving parts than your referral agreement probably describes.
The two admissions that matter most to a broker
The misleading-the-investigator finding was the contested one. But the two allegations the executive admitted are the ones that map most directly onto broker work.
1. Income that was not verified because verifying it was hard
He left PAYG employment income out of two applications and had the borrowers assessed as self-employed, even though their bank statements showed regular wage credits. He first told investigators he had forgotten. He later said he had been “lazy to verify the PAYG income” because it was “hard to verify”.
Set aside the candour of the phrasing. The mechanism is ordinary: an income stream that complicates a file gets left out, and a servicing position that would not otherwise work does. Any broker who has felt the pull of a clean self-employed assessment over a messy mixed-income one knows the shape of this. The borrower’s own statements were the thing that gave it away — which is to say, the document already on the file.
2. Customer information moving through a consumer chat app
Sharing loan progress with a referrer and a third party through a group chat was found to breach the bank’s technology policy. Brokers are not bound by that policy, but the privacy and record-keeping exposure is comparable, and worse in one respect: a broker who conducts client business in a chat app has created file records that sit outside the CRM and may not be retrievable when an audit, a complaint or a licensee review asks for the complete file. Deleting the chat did not help here. It left a gap that the decision-maker simply read against the person who created it.
Why this lands now
The timing is what lifts this above a one-off employment dispute.
ASIC has flagged a review of lender conduct within its banking supervisory agenda, expected to begin in the third quarter of 2026–27, covering three things in particular: the effect of changes banks made to proprietary lender incentives, lenders’ use of referrers and the controls around third-party introducer arrangements, and how lenders monitor broker-originated lending — including accreditation and re-accreditation, application quality, fraud indicators and customer outcomes.
That review will be conducted against a backdrop brokers already know. The Commonwealth Bank self-reported suspected fraudulent home lending to authorities in February 2026, with reporting putting the figure at around $1 billion and industry-wide estimates since reported above $3 billion. AUSTRAC’s Fintel Alliance work found the same intermediaries recurring across suspect applications at multiple banks. The MFAA has been developing referrer risk standards; its chief executive, Anja Pannek, has made the point that fraud does not respect organisational or distribution boundaries. And ASIC’s Report 840, published on 13 October 2026, found gaps in how brokers demonstrate that their recommendations serve the customer’s best interests, particularly where a cheaper loan was available.
Put those together and the direction is clear enough. Lender oversight of the third-party channel is going to be examined using exactly the artefacts this decision describes.
The best interests dimension. The best interests duty sits in sections 158LA and 158LE of the National Credit Act, and the conflict priority rule in sections 158LB and 158LF. ASIC’s Regulatory Guide 273 is explicit that brokers must not place the interests of credit providers or third parties ahead of the consumer’s (RG 273.9), and that conflicts arising from commercial relationships with third parties must be identified (RG 273.155). A referral source you are commercially dependent on is precisely such a relationship. This is general information, not advice on your arrangements — your licensee is the right place to test them.
Your referral source audit: six checks worth running this week
Work through these for each active referral source
- Name the arrangement on paper. Is there a current written referral agreement, and does it describe what actually happens — including what the referrer is paid, by whom, and when?
- Test the boundary. Does the referrer ever name a lender, suggest a product or discuss structure with the client? If yes, that goes beyond a bare referral and needs your licensee’s view before it continues.
- Follow the money both ways. Do you know whether the referrer charges your clients a separate fee? A client paying a third party near settlement, described as a “service fee”, is the exact pattern a reviewer is now primed to look for.
- Check document provenance. Are income documents and financials reaching you from the client or the issuing institution, or from the referrer’s email? If one accounting firm prepares financials for every client from one referrer, note it and verify independently.
- Reconcile stated income to the statements. For every self-employed assessment, scan the transaction listing for regular wage credits. If they are there, they belong in the file — explained, verified, or both.
- Move the conversation into the system. Pull client and referrer discussion out of personal chat apps and into the CRM, so the complete file is the file. Avoid group channels that mix lender staff, referrers and other third parties.
Key takeaways
- The Fair Work Commission dismissed a former bank lending executive’s unfair dismissal claim on 2 November 2026, finding the dismissal “wholly justified and not unfair”. It made no finding that kickbacks were paid, and made no finding against the broker, the referral partners or the accounting firm involved.
- The bank’s review began with an anonymous internal report that a preliminary look did not substantiate. What produced a case was widening the review across one person’s refinanced book and finding a repeated combination of borrower type, referrer and accountant.
- About $191,000 was reportedly traced into the account of a broker who was not an accredited referrer, across three streams between August 2023 and February 2025, with descriptions including “service fee” and “referral fee”.
- The two admitted failures — unverified PAYG income on files assessed as self-employed, and client information shared through a consumer chat app — are both ordinary broker-file risks, not exotic ones.
- ASIC’s flagged review of lender conduct, expected to start in the third quarter of 2026–27, covers referrer arrangements and lender oversight of broker-originated lending directly.
- Brokers should confirm how each referral arrangement is documented with their licensee or aggregator’s compliance team rather than assuming a long-standing arrangement is compliant.
What to watch next
Three things are worth tracking into 2027. The first is the scope of ASIC’s lender-conduct review when it formally begins, and in particular whether its broker-oversight limb results in changes to accreditation and re-accreditation practice at individual lenders — the kind of change that arrives as a panel notice rather than a regulatory announcement.
The second is introducer programs themselves. Reporting notes that two of the major banks continue to operate them while two closed theirs years ago, and that industry voices have called for them to be scrapped entirely. If a bank withdraws from introducer referrals, the referral flow does not disappear; it looks for another channel, and brokers are the obvious one. That is an opportunity, and it comes with the obligation to document the arrangement properly from day one.
The third is the quiet one: file completeness. The case turned substantially on records that existed outside the official system — a phone contact list, a deleted chat, a payment trail. Brokers who can produce a complete, coherent file from a single system are in a materially different position from brokers who cannot, and that gap is widening as reviewers get better at asking.
None of this requires a broker to treat good referral partners with suspicion. It requires the arrangement to be written down accurately, the money to be visible, the documents to come from their source, and the conversation to happen somewhere it can be retrieved. That is a modest amount of work set against the cost of explaining, later, a relationship that was only ever informal.
Frequently asked questions
No. It is an unfair dismissal decision about one bank and one former employee. It creates no new obligation for brokers. Its value is descriptive: it shows which records a lender used to test whether a referral relationship was what it appeared to be.
No. The broker was not a party to the proceedings and no finding was made against him. The payments traced into his account were recorded as part of the bank’s investigation and its concerns. The Commission ruled only on the conduct of the employee before it, and specifically made no finding that kickbacks were paid.
The licensing exemption for referrers is narrow. In substance it covers telling a consumer that a licensee can assist with credit, passing on contact details, and disclosing any benefit the referrer receives for the referral. Suggesting a particular lender or product goes further and looks like credit assistance, which requires a licence or an appointment as a credit representative. The conditions sit in the National Consumer Credit Protection Regulations, and because the detail matters, confirm how your specific arrangements are structured with your licensee or compliance adviser.
Not by itself — it is a normal consequence of working a niche or a referral relationship. What drew attention in this case was the combination: the same referrer, the same accounting firm and the same borrower profile recurring together across one person’s book. The practical response is not to avoid the accountant but to make sure verification does not depend on a single intermediary, and to note the concentration on file so it is explained before anyone asks.
As flagged in its banking supervisory agenda, the review is expected to begin in the third quarter of 2026–27 and to cover the effect of changes to proprietary lender incentives, lenders’ use of referrers and controls over third-party introducer arrangements, and how lenders monitor broker-originated lending — including accreditation, application quality, fraud indicators and customer outcomes. It is a review of lender conduct, so for brokers the effects are most likely to arrive through lender and aggregator requirements.
Sources consulted
- “Former CBA exec’s denial of broker relationship unravels before tribunal”, The Adviser, 5 November 2026.
- “‘Lazy to verify’: Senior CBA lender who denied knowing ‘Hugo’ loses unfair dismissal case”, Australian Broker, 3 November 2026.
- “Tribunal determines former CBA exec mislead bank over mortgage broker relationship”, Mortgage Professional Australia, 3 November 2026.
- “Brokers call for ‘level playing field’ as ASIC probes lender oversight”, Broker Daily, 1 October 2026.
- ASIC Regulatory Guide 273, Mortgage brokers: Best interests duty.
- ASIC Report 840, Mortgage brokers: Review of best interests duty and complaints, 13 October 2026.
Breaking news for modern brokers
Compliance developments, lender policy shifts and market data — read in the time you actually have.
More at The Broker Times →Referral Source Audit: How Would One of Your Arrangements Read on Paper?
Pick one active referral source and answer honestly for that source alone. Twelve checks across four areas, drawn from the records that decided the case above. Nothing is sent anywhere.
Whether the arrangement as written matches the arrangement as it runs.
Whether the source stays on the referral side of the line, or drifts into credit assistance.
Whether every payment around the file is visible to you and explainable.
Whether your file would hold together if someone else had to read it.
Start ticking the checks you can confirm. Anything you leave unticked will be listed below as a gap worth raising with your licensee.
Gaps to raise
This tool is a prompt for discussion, not a compliance assessment. It does not record or transmit your answers, and it is not a substitute for advice from your licensee, aggregator compliance team or a legal adviser on your own arrangements.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.