Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: CAFBA Says a Midsized Broker Could Have to Renegotiate Up to 50 Lender Accreditations. The Trust Tax Bills Cleared Their Senate Committee With 12 Rules Still Unwritten
The Broker Times · At a glance
The discretionary trust bills: what is proposed, where it stands, and the three doors
Proposed law only. Neither bill had passed the Senate at the time of writing.
Four numbers
How it has moved, and what is dated ahead
The three doors a trust client can walk through
1. Stay and absorb
- Trustee pays the minimum tax
- Non-corporate beneficiaries get a non-refundable offset
- Corporate beneficiaries get no offset
- Structure, licence and accreditations unchanged
2. Elect into the EET regime
- Open to eligible trusts in existence on 1 July 2028
- Nominate beneficiaries, fix their shares
- Departing from the proportions may revoke the election
- Cannot be combined with the rollover
3. Restructure
- Rollover relief 1 Jul 2027 – 30 Jun 2030
- Income tax relief only — state and territory duties still apply
- New operating entity
- Licence, accreditation and facility consequences
Compiled from the bills as reported, the Senate committee process, and public statements from COSBOA, CAFBA, the MFAA, CPA Australia and the Family Business Association. General information only — not tax, legal or compliance advice.
Compliance · Business structure
CAFBA Says a Midsized Broker Could Have to Renegotiate Up to 50 Lender Accreditations. The Trust Tax Bills Cleared Their Senate Committee With 12 Rules Still Unwritten
Most of the trust tax coverage has been about what it does to clients. For any broker who operates through a discretionary trust, the licensing and accreditation work lands years before the tax does.
Two bills sitting in the Senate this fortnight have been read across the industry as a tax story about clients. For brokers who run their own business through a discretionary trust, it is also a structure story about themselves — and the slowest-moving parts of it are not the tax return. They are the credit licence, the aggregator agreement and the lender accreditations.
The Treasury Laws Amendment (Tax Reform No. 3) Bill 2026 and the Income Tax Rates Amendment (Minimum Tax on Discretionary Trusts) Bill 2026 were introduced on 14 October 2026. The Adviser reports they cleared the House of Representatives on 29 October, with Senate Economics Legislation Committee hearings on 5 and 6 November. CPA Australia noted the committee’s report was due by 13 November. The committee recommended the bills pass.
Nothing here is law yet, and the measure itself would not start until income years beginning on or after 1 July 2028. But the decision it forces — stay, elect, or restructure — is in front of clients now, because the transitional rollover window opens on 1 July 2027. For brokers, the operational consequences start earlier still.
Key takeaways
- The bills propose a 30% minimum effective tax rate on the net income of certain discretionary trusts, payable by the trustee, for income years starting on or after 1 July 2028. They had not passed the Senate at the time of writing.
- Non-corporate beneficiaries would generally get a non-refundable offset for their share of the trustee’s tax. Corporate beneficiaries would not.
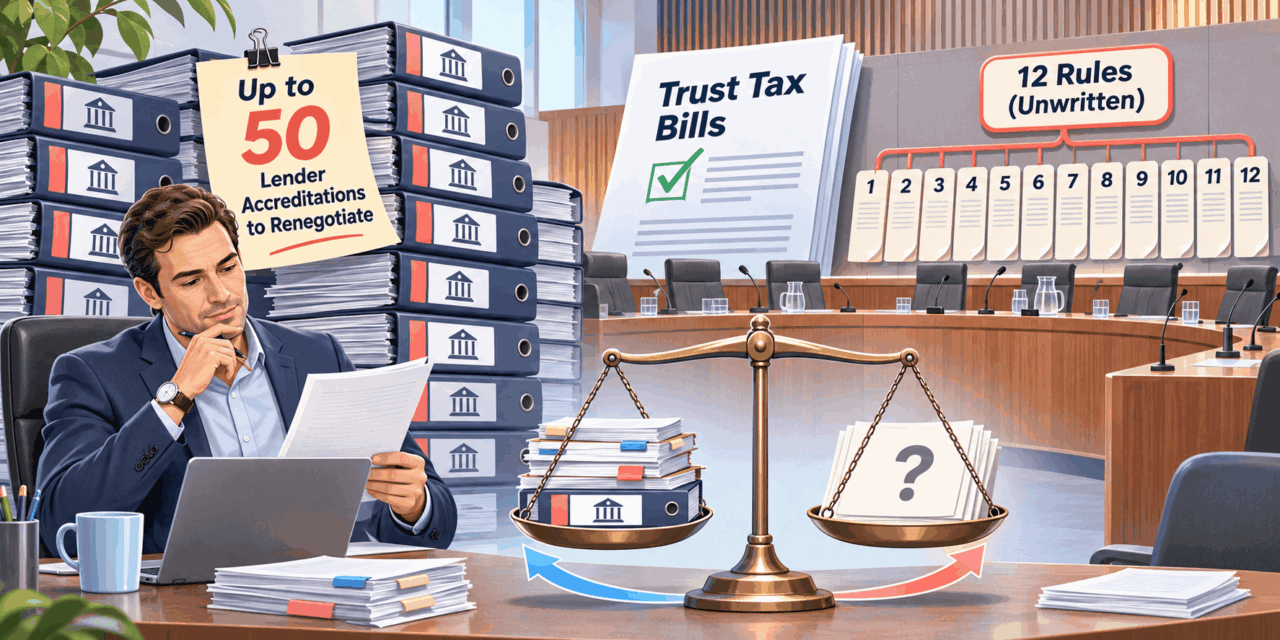
- COSBOA, CAFBA and the MFAA have jointly warned that a restructure is more than a tax exercise. The MFAA says it may require changes to Australian Credit Licence or Credit Representative arrangements; CAFBA says a midsized firm could face renegotiating up to 50 lender accreditation agreements.
- The MFAA has also warned that restructured businesses may be reassessed under current lending policy rather than the policy that applied when their finance was approved.
- CPA Australia reported that 12 rules are left to ministerial instruments that had not been released.
What the bills actually propose
On Russell Kennedy’s reading of the legislation, certain discretionary trusts would face a minimum effective tax rate of 30%. The tax is imposed on the trustee, and it applies “regardless of whether a lower rate would otherwise apply”. Eligible non-corporate beneficiaries would generally receive a non-refundable tax offset for their share of the tax the trustee paid. Corporate beneficiaries cannot claim the offset.
That last line is the one with servicing consequences, and we will come back to it.
There are three ways through. A trust can stay as it is and absorb the minimum tax. It can elect into the excluded election trust (EET) regime, open to eligible trusts in existence on 1 July 2028: the trustee nominates beneficiaries and fixes their shares of income and non-income earnings, and distributions must keep following those proportions. Depart from them and the election may be automatically revoked, with the trustee potentially taxed on the trust’s net income at the top marginal rate plus Medicare levy for that year. CPA Australia notes the election must be made between 1 July 2028 and the last day of the trust’s first income year starting on or after that date.
Or it can restructure, using transitional rollover relief available for eligible restructures between 1 July 2027 and 30 June 2030. That relief lets assets move from a discretionary trust into an alternative structure — a company or a fixed trust — without immediate income tax consequences. It is voluntary, it is not limited to trading businesses, and the trust does not have to be wound up. A trustee cannot use both the EET regime and the rollover.
There are carve-outs. Fixed trusts (with a tightened definition), deceased estates, complying superannuation entities, special disability trusts and employee share trusts sit outside the regime. Excluded income includes primary production income, certain income relating to vulnerable minors, certain charitable and not-for-profit beneficiaries, income subject to non-resident withholding tax, and income from genuine testamentary trusts.
One detail that undercuts the whole timetable. CPA Australia reported that the bill foreshadows further integrity and interaction amendments, and that 12 rules are left to ministerial instruments not yet released. Clients are being asked to choose between three doors while some of the rules behind them are still being drafted.
Where it stood as the Senate came back
The committee split along predictable lines. Senator Lisa Darmanin, the Labor senator for Victoria who chairs the committee, recommended the bills pass, pointing to the EET model as a product of consultation. Greens Treasury spokesman Senator Nick McKim backed passage once the exemption for income paid to unauthorised charities and tax-exempt entities is removed; he has described discretionary trusts as “one of the ways wealthy people minimise their tax”.
Coalition senators dissented. According to Accountants Daily, they recommended the Senate not pass the first bill unless Schedule 1 (the minimum tax) is removed, along with Schedule 3 (the EET regime), and that failing that the start date be pushed back a year to 1 July 2029. They also called for a fuller Senate inquiry reporting no earlier than 30 March 2027.
Because the Coalition opposes the bill, the government needs Greens support in the Senate. The Adviser reported that eight sitting days remain this year and that the government is targeting a Senate vote in the third week of November. In other words, by the time most brokers read a settled explainer on this, the vote may already have happened.
The part that is about brokers, not clients
On 10 August 2026, COSBOA, CAFBA and the MFAA issued a joint statement that got far less attention than the tax modelling. Its argument was that the policy debate had skipped the operational consequences for regulated small businesses — of which broking is one.
Skye Cappuccio, Chief Executive Officer of COSBOA, put it plainly: “The focus has understandably been on the tax implications, but that’s only part of the story.”
Anja Pannek, Chief Executive Officer of the MFAA, was more specific. “Restructuring a business that operates through a discretionary trust is far more than a legal or accounting exercise,” she said, and: “For mortgage brokers, it may require changes to Australian Credit Licence or Credit Representative arrangements.” Professional indemnity cover and compliance documents may need updating too.
David Gandolfo OAM, Chair of Advocacy at CAFBA, supplied the number that should stop a principal broker mid-scroll. Commercial finance brokers, he noted, “arrange around 72 per cent of Australia’s commercial equipment finance”. A midsized firm forced to restructure could be looking at “renegotiating up to 50 separate lender accreditation agreements without any assurance that the new agreements will be accepted”.
Gandolfo also flagged the asset finance version of the same problem: a restructure can mean significant break costs “if loan assignments are impossible (e.g., with commercial chattel mortgages)”.
What ASIC’s guidance says — and what it does not
It is worth being precise here, because this is the kind of question brokers get wrong in both directions.
ASIC’s Regulatory Guide 204, Applying for and varying a credit licence, does not set out a mechanism for transferring a credit licence in the sections dealing with applications. What it does say, at RG 204.111, is that if your “business changes after you are granted a licence, you should apply for a variation to your licence”. RG 204.34 makes the same point: where “your business changes, or the people who manage your business change, you may need to apply for a variation of your licence”.
There is one feature of the guide that cuts the other way, and brokers in trust structures should know it exists before assuming the worst. RG 204.67 deals with multiple trustees, where the licensed entity is treated as a notional person, and says “the trustees of the trust can change from time to time without affecting the licence”. RG 204.68 adds that “A person who is a sole trustee of a trust cannot apply as a multiple trustee.”
Whether any of that helps your particular structure is a question for your licensee and your own lawyer, not for an article. The MFAA’s warning is that changes may be required — not that they certainly are. The point of raising it now is that a licence variation, an aggregator agreement novation and a lender accreditation round are all measured in months, not weeks, and none of them can be started retrospectively.
If you operate as a credit representative under an aggregator’s licence rather than as a licensee in your own right, the question is easier to ask and not necessarily easier to answer: your authorisation attaches to a legal entity, and your aggregator agreement names one. Ask your aggregator which entity is on the paperwork, and what their process is if it changes.
Then there is the client book
The Adviser reports that about 350,000 small family businesses use discretionary trusts, and that the ATO confirmed roughly 99% of discretionary trusts reporting business income in 2023–24 were micro or small businesses. That is not a wealth-management niche. That is the self-employed segment of a commercial book, and a good slice of the self-employed residential book as well.
In its submission to Treasury the MFAA set out what a restructure does to finance already on foot. Existing loans may need review and could require lender consent. Facilities may need refinancing. Guarantees and security may need replacing. Lease and equipment finance documents may need amending.
And then the sentence that matters most for a broker’s pipeline: businesses may be reassessed under current lending policy rather than the policy in place when their finance was approved — creating what the MFAA called “additional cost, delay and uncertainty”.
Translate that into a file. A client who obtained finance in 2023 through a trust and restructures into a company in 2028 is not making an administrative change. They are a new application, from a new entity with no trading history of its own, assessed against that year’s HEM benchmarks, that year’s buffers and that year’s credit appetite. If the original approval relied on policy that has since tightened, the restructure is the event that re-exposes them to it.
The servicing question nobody has answered yet
For clients whose servicing has been built on distributed trust income, two things move at once. The trustee pays the minimum tax, and the individual beneficiary receives a non-refundable offset rather than cash. An EET election fixes the distribution proportions, which may help a lender’s view of income consistency — or may strip out exactly the flexibility the structure existed to provide.
Corporate beneficiaries get no offset at all. Any servicing position sitting behind a bucket-company strategy deserves a conversation with the client’s accountant now, rather than a discovery in 2028.
No lender has published an assessment approach for post-reform trust distributions, because the reform is not law and 12 of its rules are unwritten. That makes this a question to put to your BDMs and your aggregator’s credit team early, not a gap to fill with assumptions on a file note.
What it costs to move
The Family Business Association, in a statement issued on 16 November, cited Australian Chamber of Commerce and Industry figures putting the median net business income of small business trusts at about $75,000, and restructuring costs including stamp duty at “likely to exceed $100,000” for most small businesses that own their premises.
Catherine Sayer, the association’s Chief Executive Officer, who gave evidence in Canberra on 6 November, said: “This is death by a thousand cuts for a family that runs a trading business through a trust.” On the sequencing, she added: “Families are being asked to make decisions they cannot take back while key rules are still unwritten.”
The rollover relief is income tax relief. CPA Australia notes that state and territory duties still apply — which is where a six-figure restructure bill comes from when the business owns its premises.
On 15 November, five bodies — ACCI, COSBOA, the Housing Industry Association, Master Builders Australia and the Property Council of Australia — wrote jointly to all senators. The Adviser reported survey findings that 60% of small and medium residential and commercial developers expect the policy to affect project timing or viability, and that 37% of those said one or more projects would be cancelled. Those figures appear in that outlet’s reporting; we have not seen the underlying survey, so read them as reported rather than settled.
What to review this week
- Name your own structure, in writing. Is the entity that holds your ACL, or that is named as credit representative on your aggregator agreement, a trustee company? Is the trust discretionary or fixed? Most principals know the answer. Fewer have it recorded somewhere a lawyer could work from in an afternoon.
- Ask your aggregator one question, now. “If our operating entity changed, what is your process, how long does it take, and which lender accreditations would need to be re-done?” The answer is the single most useful piece of planning information available to you, and it costs one email.
- Count your accreditations. CAFBA’s number is up to 50 for a midsized commercial firm. Yours may be eight or eighty. Knowing which is the difference between a manageable project and an unplanned quarter.
- Segment the client book by structure, not by product. Run your CRM for borrowers where a trust is the applicant, the guarantor or the source of servicing income. That list is your 2027 conversation pipeline, and nobody else is building it for them.
- Flag the clients with security the business owns. They carry the stamp duty exposure, and they are the ones whose restructure is genuinely expensive rather than merely inconvenient.
- Route the advice properly. You are not their tax adviser and you should not be drafting the structuring recommendation. Referring the client to their accountant early — and documenting that you did — is both better service and a cleaner file.
- Do not re-paper anything yet. The bills had not passed the Senate at the time of writing, amendments were still in play, and 12 instruments were unreleased. Preparation is warranted. Irreversible action is not.
What to watch next
Four things, in order of how soon they would change a broker’s planning. Whether the Senate votes before the summer break and in what amended form. Whether the 12 ministerial instruments are released with enough lead time to be useful. Whether any state or territory signals duty relief for rollover restructures, because that is the number that determines how many clients actually move. And whether lenders publish how they will assess trust-distribution income and newly incorporated entities with no trading history — which, on current form, will arrive as scattered policy notices rather than an announcement.
The strategic read
The commercially useful thing here is not predicting the Senate. It is noticing that this reform hands brokers a reason to call every self-employed client in their database with a structural question that has a date attached to it — at a point in the cycle when new lending volumes are under pressure and most brokers are hunting for a reason to re-engage a quiet book.
The brokers who handle this well will not be the ones with the strongest view on trust taxation. They will be the ones who knew, in November 2026, which of their clients sat in a discretionary trust, and who had already asked their aggregator what a change of entity involves. Both of those are afternoon jobs. Neither of them gets easier if the bills pass on Thursday.
Frequently asked
No. Both bills had passed the House of Representatives and been through a Senate committee at the time of writing, but had not passed the Senate. The Coalition opposes the package and the government needs Greens support. Amendments remain possible, and CPA Australia reported that 12 rules are left to ministerial instruments that had not been released.
As drafted, for income years beginning on or after 1 July 2028. The transitional restructure rollover would be available for eligible restructures between 1 July 2027 and 30 June 2030, which is why the planning conversation is live well before the tax is.
No. Staying put and absorbing the minimum tax is one of the three available paths, as is electing into the EET regime if the trust is eligible and the fixed-proportion requirement suits the business. Whether any path is right for a particular firm is a question for that firm’s accountant and lawyer.
Not automatically, and this article does not assert that it would. The MFAA has warned that restructuring may require changes to Australian Credit Licence or Credit Representative arrangements. ASIC’s RG 204.111 says that where your business changes after a licence is granted you should apply for a variation. RG 204.67 notes that for a multiple trustee the licensed entity is a notional person and the trustees can change without affecting the licence. How those apply to a given structure is a matter for your licensee and your own legal advice.
The MFAA’s submission says a restructure is not simply a transfer of the business: existing loans may need review and lender consent, facilities may need refinancing, guarantees and security may need replacing, and lease and equipment finance documents may need amending. It also warns that businesses may be reassessed under current lending policy rather than the policy in place when their finance was approved.
No. CPA Australia notes the rollover is income tax relief and that state and territory duties still apply. The Family Business Association, citing ACCI, put restructuring costs including stamp duty at likely to exceed $100,000 for most small businesses that own their premises.
Stay ahead of what lands on your files
The Broker Times covers the regulatory and lender changes that reach broker desks — twice a day, written for brokers.
Interactive · Broker planning tool
Three doors, and the questions a broker should be asking behind each one
Switch between the paths a trust client — or your own business — could take, then work through the readiness checklist below.
Stay as you are
The trustee pays the proposed minimum tax. Nothing structural changes.
What happens
- Trustee liable for the minimum tax on the trust's net income from income years starting on or after 1 July 2028
- Eligible non-corporate beneficiaries generally receive a non-refundable offset for their share
- Corporate beneficiaries receive no offset
- No change to the operating entity
What a broker should check
- Does any servicing position rely on distributions routed to a corporate beneficiary?
- How does the client's net distributable income change, and over what period will a lender want to see it?
- Is there an existing facility with covenants tied to distributions?
- Nothing to do on licensing or accreditation — this is the only path with no structural consequences
Elect into the excluded election trust regime
Trade flexibility for exemption. Open to eligible trusts in existence on 1 July 2028.
What happens
- Trustee nominates beneficiaries and fixes their shares of income and non-income earnings
- While the election is in force, the minimum tax does not apply
- Distributions must keep following the nominated proportions
- Departing from them may automatically revoke the election, with the trustee potentially taxed at the top marginal rate plus Medicare levy for that year
- Cannot be combined with the restructure rollover
What a broker should check
- Fixed proportions can make distributed income look more consistent year to year — worth raising with a BDM, not assuming
- They also remove the ability to flex distributions in a bad trading year, which is the flexibility some servicing cases quietly depend on
- Does the client understand the revocation consequence before they sign?
- Coalition senators recommended removing this regime entirely — it is not settled
Restructure using the transitional rollover
The path with the longest lead time and the most moving parts for a broker.
What happens
- Eligible restructures between 1 July 2027 and 30 June 2030
- Assets can move to a company or fixed trust without immediate income tax consequences
- Voluntary, not limited to trading businesses, and the trust need not be wound up
- Income tax relief only — state and territory duties still apply
What a broker should check
- Existing loans may need review and lender consent; facilities may need refinancing (MFAA)
- Guarantees and security may need replacing; lease and equipment finance documents may need amending (MFAA)
- The business may be reassessed under current lending policy, not the policy at original approval (MFAA)
- A new company has no trading history of its own — check each lender's position on that
- Asset finance can carry break costs where loan assignment is impossible (CAFBA)
Readiness checklist
Seven things that can be done before the Senate votes. Tick them off — this runs entirely in your browser and nothing is sent anywhere.
0 of 7 complete
Start with the first one — it takes about ten minutes.
General information only. Not tax, legal, structuring or compliance advice. Confirm every point with your licensee, aggregator and professional advisers.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, tax, compliance, or financial advice. The legislation discussed had not passed the Senate at the time of writing and remains subject to amendment. Brokers should consult their aggregator's compliance team, their own accountant, and where required seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC's responsible lending guidelines.