The Broker Times · Compliance Briefing
REP 846 at a Glance: What ASIC Found Inside 24 Private Credit Funds
ASIC’s second private credit surveillance, published 10 November 2026, covering November 2025 to August 2026.
The Headline Numbers
Wholesale and retail funds reviewed under compulsory information-gathering powers.
Combined assets under management across those 24 funds.
Funds that passed the full economic benefit of interest and borrower fees to investors.
Interim stop orders since September 2026 — two on PDSs, four on TMDs.
Where the Borrower’s Money Went
ASIC defines the retained margin as the weighted average rate charged to borrowers less the weighted average rate paid to investors across the loan book. The figures are the top of a range, not a sector average.
How Complex the Structures Got
18 of 24 funds used layered intermediary entities
Special purpose vehicles, fund-of-funds structures and warehouse vehicles. ASIC says some funds did not clearly disclose them or explain what they meant for investors.
Up to 500+ SPVs in a single fund’s history
Funds used anywhere from zero to more than 500 SPVs cumulatively since inception, depending on portfolio size and nature.
17% of one fund’s assets moved in a year
Transferred to related funds run by the same management group. A second fund moved 15%. ASIC says neither was fully disclosed to investors.
38 cents per $1 to a related party
For every dollar distributed to investors in one fund, a related party of the operator received 38 cents. Undisclosed benefits exceeded four times disclosed management costs.
The Word That Isn’t in the Report
What Happens Next
The Broker Takeaway
REP 846 is a review of how private credit funds treat their investors. It did not assess how those funds treat borrowers, and it makes no finding about any fund’s willingness or ability to settle a loan. What it gives brokers is published, sourced evidence about governance, fee transparency and structural complexity at entity level — the kind of thing worth knowing before you put a client’s commercial deal, and your own name, behind a funder.
Source: ASIC media release 26-273MR and Report 846, Private credit funds: Do investors know what they’re getting?, both published 10 November 2026. Figures quoted are ASIC’s own. The “more than $250 billion” private credit market estimate cited in REP 846 is attributed by ASIC to an Australian Financial Review article of 16 September 2026 referencing Alvarez & Marsal statistics.
Compliance · Private Credit
Two of 22 Private Credit Funds Passed the Full Economic Benefit to Investors
REP 846 never mentions brokers — but ASIC says it will keep scrutinising the whole private credit value chain, and two of its ten principles are written about borrowers.
What’s in this article
On 10 November, ASIC published the findings of its second major private credit surveillance. The report is addressed to fund operators, distributors and financial advisers, and its central question is whether investors understand what they are buying. For a finance broker, that sounds like someone else’s problem. It isn’t — because the funds in question are the ones writing the commercial, bridging and construction loans that brokers increasingly rely on when a bank says no.
What ASIC published on 10 November
Report 846, Private credit funds: Do investors know what they’re getting?, sets out what ASIC found after reviewing 24 wholesale and retail private credit funds responsible for a combined $18 billion in assets under management. The surveillance ran from November 2025 to August 2026 and used ASIC’s compulsory information-gathering powers. It also took in a sample of personal financial advice given to retail clients about private credit.
The report builds on REP 820, published a year earlier, and the headline is that the problems did not get fixed. ASIC’s own summary is that “many of the poor fee, disclosure, distribution and conflict-management practices identified in ASIC’s first private credit report, released in November 2025, remain”. The surveillance produced six interim stop orders — two on product disclosure statements and four on target market determinations — plus multiple referrals for further enforcement investigation.
For scale: REP 846 notes that “by some estimates, loans issued by private credit lenders have swelled to more than $250 billion in 2026”. ASIC attributes that estimate to an Australian Financial Review article of 16 September 2026 referencing Alvarez & Marsal statistics, rather than to its own data. Treat it as an industry estimate, not a regulator’s count.
“Investors should not need forensic skills to understand how a fund operates. They provide the capital and they bear the risk — they are entitled to understand how their money is being used, how risks and conflicts are managed, and whether decisions are made in their interests.”
Simone Constant, ASIC Commissioner, quoted in ASIC media release 26-273MR, 10 November 2026
Where the borrower’s money actually went
This is the part of the report that sits closest to a broker’s desk, because it is about fees your client pays.
ASIC reports that only two of the 22 retail and wholesale funds reviewed passed the full economic benefits of interest earned and borrower fees through to investors. The rest kept some portion. Specifically, seven of 10 retail funds and nine of 12 wholesale funds did not fully pass establishment or origination fees to investors, and five of 10 retail funds and seven of 12 wholesale funds did not fully pass default fees. Two funds did not disclose the retention of establishment or origination fees at all.
On margins, ASIC measured the difference between the weighted average rate charged to borrowers and the weighted average rate paid to investors across the loan book for calendar 2025. The retained margin ranged from 0.00% — where everything was passed through — to a maximum of 5.6% for retail funds and 5.9% for wholesale funds. Those upper figures are the top of a range, not a sector norm, and it is worth being precise about that when the number gets repeated.
In one case the arithmetic is stark. ASIC found that the undisclosed borrower fees, interest margin and default interest retained by a related-party lender exceeded four times that fund’s disclosed management costs, and that for every $1 distributed to investors, a related party of the fund operator received 38 cents during the relevant calendar year.
Read that from the borrower’s side of the table. An establishment fee, an extension fee, a rollover fee and default interest are all real costs in a client’s deal. ASIC’s finding is not that those fees were unlawful or that borrowers were overcharged — it is that investors were often not told who was keeping them. But it tells a broker something useful anyway: in parts of this market, the economics between the fund, the manager and the related-party lender are complicated enough that the regulator needed compulsory powers to see them.
The structures between the investor and the loan
ASIC found 18 of the 24 funds used multiple layers of intermediary entities — special purpose vehicles, fund-of-funds structures and warehouse vehicles. SPVs were a material part of the structure in 10 of 12 wholesale funds and three of 12 retail funds, and funds used anywhere from zero to more than 500 SPVs cumulatively since inception depending on the size and nature of the portfolio.
ASIC is careful to say these structures “may serve commercial and operational purposes” — isolating risk, accommodating investors with different risk appetites, improving efficiency. The criticism is about disclosure, not the existence of SPVs. But the report notes the structures “could affect who legally owned the underlying assets, who controlled key decisions”, and in some cases funds obtained exposure through intermediary vehicles or contractual arrangements rather than direct ownership of the loans and security.
Then there is the movement of assets. In one case, around 17% of a fund’s assets were transferred to related funds managed by the same group within a single year. In another, 15%. ASIC says neither was fully disclosed to investors.
Be careful what you conclude from this
REP 846 is a review of investor-facing disclosure, fee transparency, governance and distribution. It did not assess whether these funds are good or bad lenders, and it makes no finding about any fund’s willingness or capacity to settle a loan a broker submits.
It also names no brokers, alleges no broker misconduct, and the six stop orders are interim disclosure-related orders, not findings of guilt against anyone. Any mention of named entities elsewhere in ASIC’s private credit work should be read the same way.
The word that isn’t in the report
Search the 58 pages of REP 846 for the word “broker” and you will not find it. That is worth saying plainly, because the trade conversation around this report has drifted toward what it means for the broker channel, and the honest answer is that ASIC was not writing about finance broking at all.
What the report does name is a longer list of participants. ASIC says it “will continue to scrutinize conduct of participants across the value chain of private credit from underwriters and originators through trustees and responsible entities to valuers and auditors”, and that “fund operators, distributors, intermediaries and financial advisers should carefully consider the findings of this report and act now”.
Those words carry a specific meaning in this context. “Distributors” and “intermediaries” here are the people putting investors into funds, not the people putting borrowers into loans. A broker who writes a commercial deal funded by a private credit fund is not the distributor ASIC is addressing. The distinction matters, and it is the reason this article is not a compliance warning.
The point is narrower and more practical. Two of ASIC’s ten principles of private credit done well are written to include borrowers explicitly. Principle 5 says fees and costs should be “fair and transparent, giving investors and borrowers a clear view of total costs”, and asks participants to “avoid complex fee and margin structures that obscure the true cost”. Principle 6 frames conflict management as promoting “fair treatment of investors, borrowers and other parties”, and asks funds to disclose related-party transactions and multiple exposures to the same borrower.
So the regulator’s own better-practice framework for this sector already contemplates the borrower’s view of total cost. A broker asking a funder to meet that standard is not being difficult. They are asking for something ASIC has published as good practice.
Why best interests duty probably doesn’t reach this
It is tempting to frame funder selection as a best interests duty question. For most private credit deals, it isn’t — and getting this wrong in a file note is worse than not mentioning it.
RG 273 is explicit about scope. At RG 273.5, ASIC states that “the best interests obligations apply only in relation to credit products that are regulated under the National Credit Act — that is, products provided to consumers for personal, domestic or household purposes or for the purchase or improvement of residential investment property”. The duty itself sits in sections 158LA and 158LE of the National Credit Act, within Part 3-5A.
A genuine business-purpose commercial, bridging or construction facility is generally not a regulated credit contract, so the statutory best interests duty and the conflict priority rule generally do not attach to it. Where a broker is providing credit assistance on regulated consumer credit, RG 273.112 to RG 273.115 are the relevant paragraphs on panel and accreditation adequacy: ASIC says a broker “must be satisfied that the credit products you can access and recommend are sufficient to allow you to act in your consumers’ best interests”, should be “accredited with a reasonably representative panel of credit providers”, and “must not provide credit assistance” at all where they are not satisfied the available products and credit providers allow them to act in the consumer’s best interests.
That last sentence is the one worth sitting with. It is written about consumer credit, but it describes a discipline any broker can borrow: if you are not satisfied the funder in front of you lets you do right by the client, the answer can be to decline the deal.
This is general information, not advice on your obligations. Whether a particular facility is regulated, and what your licence requires of you, is a question for your licensee or aggregator compliance team and, where the stakes warrant it, your own lawyer.
What changes in early 2027
The forward-looking part of REP 846 is the one brokers should diarise. ASIC says it expects to consult in early 2027 on changes to a range of regulatory guidance, and gives one concrete example: expanding the scope of Regulatory Guide 45 Mortgage schemes: Improving disclosure for retail investors from mortgage schemes to all types of private credit funds, including proposing a definition of “private credit fund” for which the disclosure benchmarks and principles would apply.
RG 45 works through disclosure benchmarks and principles — standardised things a scheme discloses so investors can compare like with like. Broadening it would mean more private credit funders producing comparable, published information about their portfolios on a routine basis. ASIC also says it continues to advocate for stronger data collection powers over managed investment schemes.
None of that is law yet; it is a flagged consultation. But the direction is more disclosure from non-bank funders, and published disclosure is useful to anyone trying to assess a funder, whether they are investing in it or placing a client’s deal with it.
Alongside that, ASIC has made poor practices in private credit a 2026–27 enforcement priority and says it has several well-progressed enforcement investigations underway.
Key takeaways
- ASIC reviewed 24 private credit funds holding $18 billion and found that many of the fee, disclosure, distribution and conflict-management practices it flagged in November 2025 remain.
- Only two of the 22 funds analysed for lending income passed the full economic benefit of interest and borrower fees through to investors; establishment, origination and default fees were commonly retained.
- The report is about investor disclosure, not lending conduct. It makes no finding about how these funds treat borrowers, and names no brokers.
- The statutory best interests duty generally won’t apply to a genuine business-purpose facility — RG 273.5 limits the obligations to credit regulated by the National Credit Act.
- Early 2027 is the date to watch, when ASIC expects to consult on expanding RG 45 from mortgage schemes to all private credit funds.
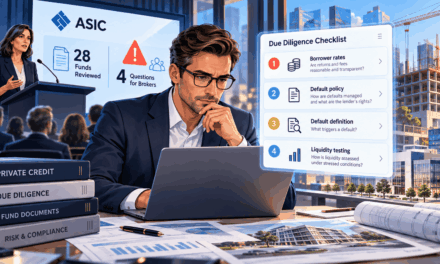
A funder due-diligence checklist
Not a compliance requirement — a commercial discipline, built from the things ASIC says good practice looks like.
- Ask who keeps the borrower fees. Establishment, origination, extension, rollover and default fees are your client’s money. Ask the funder, in writing, which entity receives each one. ASIC’s Principle 5 says borrowers are entitled to a clear view of total cost.
- Ask what sits between the fund and the loan. Is the lender on the mortgage the fund itself, an SPV, a warehouse vehicle or a related-party originator? Who actually makes the decision to extend, vary or enforce?
- Ask about related-party involvement. Does a related party of the manager earn fees on your client’s loan? Is the same group lending, managing and valuing?
- Check the published disclosure. For retail funds there is a PDS and a TMD. ASIC issued four interim TMD stop orders and two PDS stop orders out of this surveillance, so the quality is uneven — read them rather than assuming.
- Price the exit, not just the entry. Default interest and extension fees are where a short-term facility gets expensive. Model the scenario where the client’s settlement or refinance is three months late.
- Write down what you asked and what you were told. Even outside the National Credit Act, a file that records the funder questions you asked is the file that holds up if a deal sours.
- Take licence questions to your licensee. Whether a facility is regulated, and what your accreditation and licence obligations are, is their call, not an article’s.
What this changes in client conversations
Most brokers placing commercial and bridging deals already know that non-bank and private credit funding is where the flexibility lives, and that flexibility is priced. What REP 846 adds is a published, citable basis for a conversation that used to rely on instinct.
When a client asks why one funder’s indicative rate looks better than another’s, the retained-margin and retained-fee findings give you a way to explain that the headline rate is not the whole cost, and that the structures behind some funders are complex enough that the regulator needed compulsory powers to map them. That is a more credible explanation than “trust me, read the fine print”.
It also sharpens the referral conversation. If an accountant or financial adviser asks you about a private credit investment — not a loan — REP 846 is squarely relevant to them, and that is their regulated territory, not yours. ASIC found that among advice files recommending more than 20% of a portfolio in private credit funds, 88% did not demonstrate compliance with the best interests duty, with the highest single-fund allocation observed at 87% of a portfolio. ASIC is careful to add the context: it reviewed only a small sample, chosen using a mix of random selection and risk indicators, says the findings are “not representative of the broader financial advice sector”, and found that most advisers reviewed did demonstrate compliance with their obligations. Worth knowing that this is a different best interests duty, under different legislation, applying to advisers — and that it is not a broker’s job to opine on it. The right move is to send the question back to someone licensed to answer it.
What to watch next
- Early 2027: ASIC’s consultation on revised guidance, including the proposed expansion of RG 45 to all private credit funds and a definition of “private credit fund”.
- Industry standards: ASIC acknowledges industry bodies’ work on enhanced standards built on its ten principles, and says what matters is whether they are adopted and embedded.
- Enforcement: poor private credit practices are a 2026–27 ASIC enforcement priority, with several well-progressed investigations and multiple referrals from this surveillance.
- Funder disclosure quality: if the funders on your panel start publishing more detailed portfolio and fee information, that is the practical effect of all this reaching your desk.
The bottom line
REP 846 is not a broker story, and anyone telling you it is has read the headline rather than the report. But the funds it examines are a growing part of where Australian business and construction borrowing now comes from, and a regulator has just spent ten months establishing, with compulsory powers, that in much of this sector the money is harder to follow than it should be.
Brokers do not need a new obligation to act on that. They need the questions in the checklist above, asked in writing, before the deal goes in — and a file that records the answers. The funders who can answer quickly and clearly are telling you something. So are the ones who can’t.
Frequently asked
No. It is a surveillance report about private credit funds and how they disclose fees, structures, conflicts and risks to investors. It creates no new broker obligation, names no brokers, and does not mention broking. Any change to your own obligations would come from your licence, the National Credit Act, or future ASIC guidance — and your licensee is the right source on that.
Generally not, for a genuine business-purpose facility. RG 273.5 says the best interests obligations apply only to credit products regulated under the National Credit Act — broadly, consumer credit for personal, domestic or household purposes, or for buying or improving residential investment property. Whether a specific deal is regulated is a question for your licensee or compliance adviser, not a general article.
No. ASIC’s findings on establishment, origination and default fees are about whether those amounts were passed through to, and disclosed to, investors. The report makes no finding that borrowers were overcharged and did not assess the funds’ lending conduct toward borrowers.
Out of this surveillance ASIC issued two interim stop orders on product disclosure statements and four on target market determinations, all since September 2026. Interim stop orders are disclosure-related interventions that halt offers while issues are addressed; they are not findings of guilt, and ASIC has said previous stop orders in this area were lifted once the identified issues were fixed.
No. REP 846 says that “by some estimates” private credit lending has grown beyond $250 billion in 2026, and footnotes that to an Australian Financial Review article of 16 September 2026 referencing Alvarez & Marsal statistics. The $18 billion figure is ASIC’s own — it is the combined assets under management of the 24 funds reviewed.
Stay across what actually changes on your files
The Broker Times tracks the regulatory and lender shifts that reach Australian brokers’ desks — with the primary sources attached.
Sources: ASIC, 26-273MR ASIC finds private credit practices continue to leave investors in the dark, 10 November 2026; ASIC, Report 846 Private credit funds: Do investors know what they’re getting?, 10 November 2026; ASIC, Regulatory Guide 273 Mortgage brokers: Best interests duty, June 2020. All figures and quotations are taken from those documents.
Interactive · Broker Tool
Funder Due-Diligence Self-Check
Work through the questions ASIC’s own better-practice principles imply, then check what REP 846 does and does not actually say.
Tick each question you have actually asked a funder and received a clear written answer to on your current deal. Nothing is stored or sent — this is a prompt for your own file note, not a compliance assessment.
0 of 8 answered in writing
Start ticking to see where the gaps are on this deal.
Reports like this get summarised quickly and inaccurately. Tap each statement to see what ASIC actually published.
The fee findings are about whether interest and borrower fees were passed through to, and disclosed to, investors. ASIC makes no finding that borrowers were overcharged, and the surveillance did not assess the funds’ conduct toward borrowers.
The word “broker” does not appear in the report. ASIC says it will keep scrutinising participants across the value chain “from underwriters and originators through trustees and responsible entities to valuers and auditors”, and addresses fund operators, distributors, intermediaries and financial advisers — meaning those who distribute funds to investors, not brokers placing borrowers into loans.
5.9% is the top of a range for wholesale funds in calendar 2025; the range starts at 0.00%, where all interest income was passed through. The retail range tops out at 5.6%. ASIC defines the figure as the weighted average rate charged to borrowers less the weighted average rate paid to investors across the loan book.
ASIC issued six interim stop orders — two on product disclosure statements and four on target market determinations. These are disclosure interventions that pause offers while issues are addressed, not findings of guilt. ASIC has noted that earlier stop orders in this area were lifted once the identified issues were fixed.
RG 273.5 states the best interests obligations apply only to credit products regulated under the National Credit Act — broadly, consumer credit for personal, domestic or household purposes or for buying or improving residential investment property. A genuine business-purpose facility generally falls outside that. Whether a particular deal is regulated is a question for your licensee or compliance adviser.
ASIC writes that “by some estimates” private credit lending exceeded $250 billion in 2026, and footnotes it to an Australian Financial Review article of 16 September 2026 referencing Alvarez & Marsal statistics. ASIC’s own figure is the $18 billion in combined assets under management across the 24 funds it reviewed.
General information only. This tool reflects ASIC’s published findings and better-practice principles. It is not legal or compliance advice and does not assess your obligations. Raise questions about your licence, accreditation or a facility’s regulatory status with your licensee or aggregator compliance team.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.