Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: Investor Loans Fell 30.6% in a Quarter While Owner-Occupier Fell 5.3%. Refinancing Fell Too — the Usual Offset Isn’t There
The Broker Times · Data Brief
One Quarter, Two Very Different Markets
ABS Lending Indicators, September quarter 2026 — released 11 November 2026. Seasonally adjusted. Dwelling commitment series exclude refinancing.
The quarterly fall, segment by segment
Where the fall actually came from
About four-fifths of it was investors
Working back from the ABS seasonally adjusted changes, roughly 15,600 of the quarter’s fall of about 19,900 loans sits in the investor segment — close to 78%. This is a Broker Times calculation from the published figures, not an ABS statement.
Investors are now 31.6% of new lending
35,301 of 111,878 commitments by number, and 30.4% by value. The turn was fast: annual growth in the number of investor loans moved from +24.9% in the December quarter 2025 to −38.5% in the September quarter 2026.
Owner-occupier falls led by Queensland
Quarterly falls in owner-occupier loan numbers were led by Queensland (−10.4%), Victoria (−6.6%) and New South Wales (−4.1%). The investor falls were broad-based across every state and territory.
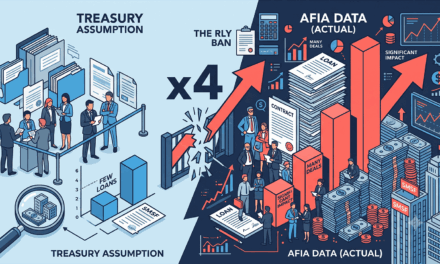
The offset that didn’t arrive
Purchases fall
New dwelling commitments down 15.0% by number to 111,878.
Refinancing usually fills the gap
External refinancing is now nearly as large as new lending: 97,618 commitments worth $64.0b.
This quarter it fell too
Owner-occupier refinancing down 3.8%, investor refinancing down 6.0%, by number.
So the hedge is thinner
Both halves of the standard broker pipeline contracted in the same quarter.
The takeaway
No broker’s pipeline fell 15%. A book weighted to investors had a far worse quarter than the headline; a book weighted to owner-occupiers and first home buyers barely moved by comparison. Before acting on the market number, work out which number describes your business.
Source: Australian Bureau of Statistics, Lending Indicators, September quarter 2026, released 11 November 2026. All figures seasonally adjusted. Derived shares and the contribution-to-fall estimate are Broker Times calculations from the published ABS figures and are approximate.
Market Data · The Broker Times
Investor Loans Fell 30.6% in a Quarter While Owner-Occupier Fell 5.3%. Refinancing Fell Too — the Usual Offset Isn’t There
The Australian Bureau of Statistics published the September quarter Lending Indicators at 11:30am on 11 November. The headline is the largest quarterly fall in new home lending since the series began in 2002. The more useful number for your business is the one underneath it.
What’s in this article
Every broker will see the same headline this week: new home lending fell 15.5% in the September quarter, the biggest quarterly drop the ABS has recorded since it began the series in September quarter 2002. It is a real number and it is seasonally adjusted, so it is not a calendar artefact.
It is also a number that describes almost nobody’s pipeline. Underneath that single figure sit two markets that behaved nothing alike. Owner-occupier lending fell 5.3% by number. Investor lending fell 30.6%. If you run a book weighted toward investors, your September quarter was far worse than the headline suggested. If you run a book weighted toward owner-occupiers and first home buyers, it was a soft quarter rather than a historic one. The planning decisions that follow — hiring, marketing spend, whether to diversify, whether to panic — should be made off your number, not the market’s.
What the ABS actually published
The release covers the September quarter 2026 and was published on 11 November. All the figures below are seasonally adjusted, and the dwelling commitment series exclude refinancing — refinancing is reported separately, which matters for the point further down.
| Segment | Number | Qtr change | Annual change | Value | Qtr change |
|---|---|---|---|---|---|
| Total new dwelling loans | 111,878 | −15.0% | −21.4% | $81.2b | −15.5% |
| Owner-occupier | 76,578 | −5.3% | −9.8% | $56.5b | −5.3% |
| Investor | 35,301 | −30.6% | −38.5% | $24.7b | −32.3% |
| First home buyers (owner-occupier) | 26,415 | −8.6% | −12.3% | $16.2b | −8.0% |
| External refinancing — owner-occupier | 63,475 | −3.8% | −5.9% | $40.6b | −3.3% |
| External refinancing — investor | 34,143 | −6.0% | −7.9% | $23.4b | −6.5% |
The ABS describes the investor result as the third consecutive quarterly decline, and the largest quarterly fall on record for both the number and the value of investor commitments. It also notes the investor falls were broad-based, with strong declines in every state and territory — this was not one city dragging a national series around.
The turn is recent and it is sharp. Annual growth in the number of investor loans moved from 24.9% in the December quarter 2025 to minus 38.5% in the September quarter 2026. That is a swing of more than 60 percentage points in three quarters, in the segment that had been carrying the market.
The fall has one address
Work backwards from the published seasonally adjusted changes and the arithmetic is stark. The quarter lost roughly 19,900 new dwelling commitments. About 15,600 of those — close to four-fifths — were investor loans. The owner-occupier segment contributed around 4,300.
A note on that figure. The 78% estimate is a Broker Times calculation derived from the ABS seasonally adjusted percentage changes, not a figure the ABS published. It is approximate, and seasonally adjusted series do not reconcile perfectly when reversed. Treat it as an order of magnitude, not a precise split.
The composition consequence is the part worth writing down. Investors are now 31.6% of new dwelling commitments by number and 30.4% by value. Twelve months ago that share was materially higher — applying the ABS annual changes to the published figures puts it at roughly 40%, a Broker Times calculation rather than an ABS figure. The market you are selling into in the December quarter is therefore not a smaller version of last year’s market. It is a differently shaped one, with a smaller investor slice and a proportionally larger owner-occupier and first home buyer slice.
That changes practical things. It changes which lenders matter on your panel, because investor pricing and investor-specific policy carry less weight in a book that is 31% investor than one that is 40%. It changes which referral partners are productive — a buyer’s agent pipeline built on investor clients is drawing from a pool that has shrunk by more than a third in a year. And it changes what a realistic conversion target looks like, because the enquiry mix arriving at the top of your funnel has moved.
The offset that didn’t arrive
The standard broker response to a falling purchase market is to work the back book. When people stop buying, they refinance, and the channel absorbs some of the shock. That has been the reliable hedge through most recent cycles.
It did not operate this quarter. External refinancing fell in both segments: owner-occupier refinancing down 3.8% by number to 63,475, investor refinancing down 6.0% to 34,143. By value, owner-occupier refinancing fell 3.3% to $40.6b and investor refinancing fell 6.5% to $23.4b. Across both segments, refinancing commitments fell on an annual basis as well.
Scale matters here. Combined external refinancing ran to 97,618 commitments worth $64.0b in the quarter, against 111,878 new dwelling commitments worth $81.2b. Refinancing is now close to the size of the purchase market by number. When it contracts at the same time as purchases, there is no second engine to switch to.
It is worth being precise about what this does and does not mean. The ABS reports what happened; it does not explain why refinancing fell. Falling property values compress available equity and can close the exit for borrowers who would otherwise switch, and rising rates narrow the gap between a front book and a back book rate. Both are plausible contributors. Neither is established by this release, and a broker quoting a cause to a client should say which part is data and which part is inference.
The operational consequence is simple enough. If your 2027 business plan assumes refinancing volume fills the hole left by purchase volume, that assumption is currently running against the data. It may reassert itself. It did not hold in the September quarter.
Where it landed on the map
The owner-occupier falls had a geography. The ABS reports that quarterly falls in owner-occupier loan numbers were led by Queensland at 10.4%, Victoria at 6.6% and New South Wales at 4.1%. A Queensland brokerage writing owner-occupier business had roughly double the national segment fall to absorb.
The investor side had no such refuge. The ABS describes those declines as broad-based, with strong falls in every state and territory. A brokerage that diversified geographically within the investor segment has not been protected by doing so.
For principals comparing their own numbers to the market, this is the level of granularity worth using. The national figure is a poor benchmark. Your state’s owner-occupier change and the national investor change, weighted by your own book, is a far better one.
What held up
Two things in the release moved better than the rest.
First home buyers fell — 8.6% by number in the quarter, after a 4.4% fall in the June quarter, and 12.3% lower than a year earlier. But the ABS notes they continued to account for more than one-third of owner-occupier commitments. On the published figures that is 26,415 of 76,578, or 34.5%. Measured by value, first home buyer lending fell 3.7% over the year against 4.6% for owner-occupiers overall. In a quarter where the investor segment lost almost a third of its volume, a segment down single digits is comparatively robust, and it is a segment with high advice dependency and long client lifetimes.
The other mover is in a different table entirely. Personal fixed-term lending for road vehicles rose 1.8% in the quarter to $4.8b — the only one of the housing and personal series set out above to rise. It was still 2.7% lower than a year ago, and total personal fixed-term lending fell 3.9% to $9.3b, so this is not a boom. But for brokers already accredited in asset finance, a segment that grew while housing fell 15% is a data point worth having in front of you when you plan the next quarter.
A caution on diversification. Moving volume into commercial and asset finance changes your regulatory position as well as your revenue mix. The best interests duty under the National Consumer Credit Protection Act applies to credit assistance for consumer credit; much commercial and asset finance work sits outside it, and different obligations and disclosure practices apply. That is a conversation for your licensee or compliance adviser before you write the business, not after.
“Beyond borrowing costs”: the client conversation
The ABS attached an unusually direct piece of commentary to this release.
Read that as a statistician’s observation about what the data is consistent with, not as a forecast or a policy position. The ABS is not predicting tax changes, and this article does not either.
What it tells a broker is something about the nature of the hesitation sitting in their investor pipeline. If investors were stepping back purely because repayments had risen, the fix would be a servicing conversation: a different lender, a different structure, a different loan amount. If part of the hesitation is about expected values and possible policy change, a servicing conversation will not resolve it, because the client is not asking whether they can afford the loan. They are asking whether they want the asset.
That distinction is worth making explicitly at the fact-find. A client who cannot proceed and a client who has decided not to proceed are different files, with different follow-up timing and different file notes. Treating the second as the first produces a lot of wasted re-presentation and a frustrated client.
The file: a non-linear process still needs a record
Quarters like this one generate a particular kind of file: the one that starts, stalls, gets re-scoped three months later with a different lender and a smaller loan amount, and settles — or does not. Applications sit longer, clients change their minds, and a recommendation made in July is reconsidered in November against different pricing and different policy.
ASIC’s guidance anticipates exactly this. Regulatory Guide 273 says at RG 273.169 that taking notes and keeping records contemporaneously “may help you to accurately capture your thinking and reasoning at each relevant point in time”, and that drafting notes only at the end of the process “may not be as effective”. At RG 273.170 it goes further:
ASIC adds that the summary “should be evidence based and supported by contemporaneous records”. This is guidance on how ASIC approaches the obligations, not a prescriptive rule, and RG 273 sets out ASIC’s views rather than creating separate requirements of its own. Your licensee’s process is the one that governs your file. But the practical logic is sound and it is cheap to apply: a file that was reopened twice is harder to read back than a file that ran straight through, and the narrative summary is the thing that makes the second one legible a year later.
A reasonable working habit in a quarter like this: when a file goes quiet, write three lines before you close the tab — what was recommended, what the client decided, and why the process paused. It takes a minute and it is the difference between a complete record and a reconstruction.
What to review this week
Broker action checklist
- Calculate your own investor weighting. Pull the last four quarters of settled volume and split it investor versus owner-occupier. Whichever side of 31.6% you sit on tells you whether the national headline overstates or understates your exposure.
- Rebuild your benchmark. Compare your owner-occupier volume to your own state’s change, not the national one. Queensland fell 10.4%, Victoria 6.6%, New South Wales 4.1%.
- Stress-test the refinance assumption. If your forward plan relies on refinancing absorbing a weak purchase market, model it again with refinancing flat to down. Both segments fell this quarter.
- Segment your stalled investor files. Separate “cannot proceed on servicing” from “has decided not to proceed”. They need different follow-up intervals and different notes.
- Look again at first home buyers. Still more than a third of owner-occupier commitments, and the mildest annual fall by value in the housing table.
- Check your asset finance accreditations. Road vehicle lending rose 1.8% in the quarter. If you are not accredited, find out what your aggregator requires — and confirm with your licensee which obligations attach outside the consumer credit regime.
- Write the narrative summary on reopened files. Three lines, contemporaneously, on anything that has stalled and restarted.
Key takeaways
- New home lending fell 15.5% by value in the September quarter 2026 to $81.2b — the largest quarterly fall since the ABS series began in September quarter 2002.
- The fall was concentrated: investor commitments fell 30.6% by number, owner-occupier commitments 5.3%. On Broker Times calculations from the ABS figures, roughly four-fifths of the fall in loan numbers sits in the investor segment.
- External refinancing did not offset it. Owner-occupier refinancing fell 3.8% and investor refinancing 6.0% by number, so both halves of the typical broker pipeline contracted together.
- First home buyers fell 8.6% but the ABS notes they remain more than one-third of owner-occupier commitments. Road vehicle personal lending rose 1.8%, the only one of the series set out above to rise.
- The national headline is a poor benchmark for an individual brokerage. Your investor weighting and your state’s owner-occupier change are the numbers that describe your business.
Questions brokers are asking
It is the largest quarterly fall in the value of new dwelling loan commitments since the ABS series began in the September quarter 2002. The series does not extend further back than that, so it is a record for the series rather than for all time.
No. The ABS states that the dwelling loan commitment series exclude refinancing. External refinancing is published separately, and this quarter it fell as well — 3.8% for owner-occupiers and 6.0% for investors, by number.
No. Dr Mish Tan, the ABS head of finance statistics, said the data suggests investor activity is being influenced by factors beyond increasing borrowing costs, “including the potential impacts of tax changes and expectations of lower house prices”. That is an observation about what the data is consistent with. The ABS did not announce or forecast any tax change.
It is a Broker Times calculation, not an ABS figure. Reversing the published seasonally adjusted quarterly changes gives a fall of roughly 19,900 commitments in total, of which about 15,600 were investor loans. Seasonally adjusted series do not reconcile exactly when worked backwards, so the figure is approximate.
The best interests duty in the National Consumer Credit Protection Act applies to credit assistance for consumer credit regulated by that Act. Commercial and much asset finance lending generally sits outside that regime, and different obligations apply. The boundary turns on the specific product and purpose, so confirm the position for your own panel with your licensee or compliance adviser before relying on it.
The September quarter was not a uniformly bad quarter for the broker channel. It was a very bad quarter for one segment of it, a mildly soft quarter for another, and a quarter in which the usual counterweight did not swing. Those three facts point in different directions for different brokerages, which is precisely why the single national number is the least useful figure in the release.
The work this week is not forecasting. It is measurement. Find out which of these markets your business actually sits in, benchmark against that, and plan the December quarter off a number that describes you.
Breaking news for modern brokers
Market data, lender policy and compliance developments, read for what they change on your desk.
Sources
- Australian Bureau of Statistics, Lending Indicators, September quarter 2026, released 11 November 2026 — abs.gov.au
- Australian Bureau of Statistics media release, Largest quarterly falls on record led by loans to investors, 11 November 2026 — abs.gov.au
- ASIC, Regulatory Guide 273: Mortgage brokers — Best interests duty, June 2020, RG 273.169–RG 273.170 — asic.gov.au
Interactive · Broker Tool
Which Market Is Your Book Actually In?
The national headline was a 15.0% fall in new loan numbers. Almost no brokerage sits on that number. Set your own mix and see which figure describes your business.
By number of loans over the last four quarters. The national figure this quarter was 31.6%.
The ABS published quarterly owner-occupier falls for these states. Choose “National” for anywhere else.
The headline overstates your fall. On this mix, a book like yours saw a shallower decline than the national figure. Benchmarking against −15.0% would flatter a flat quarter and hide an underperforming one.
Three things to do with this number
- Benchmark honestly. If your indicative figure is well below the national headline, a quarter that merely matched the market was a good quarter for your segment mix — and vice versa.
- Check the refinance assumption. Whatever your mix, external refinancing fell this quarter too (owner-occupier −3.8%, investor −6.0% by number). It is not currently filling the gap.
- Decide before you spend. Marketing, hiring and diversification decisions made off the national number will be wrong in both directions for most brokerages.
How this is calculated: investor share × −30.6% plus the remaining share × your selected owner-occupier change. It applies published ABS seasonally adjusted quarterly changes for the September quarter 2026 to a hypothetical mix. It is an indicative illustration of segment weighting only — not a measurement of your business, a forecast, or financial advice. Source: ABS Lending Indicators, September quarter 2026.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator's compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC's responsible lending guidelines.