Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: SME Liquidity Fell 7.3% While Sales Fell 2.2%. The Second-Strongest Industry on Shift’s New Index Lost 38.4% of Its Cash
The Broker Times · SME Data Snapshot
Cash Is Draining Faster Than Revenue
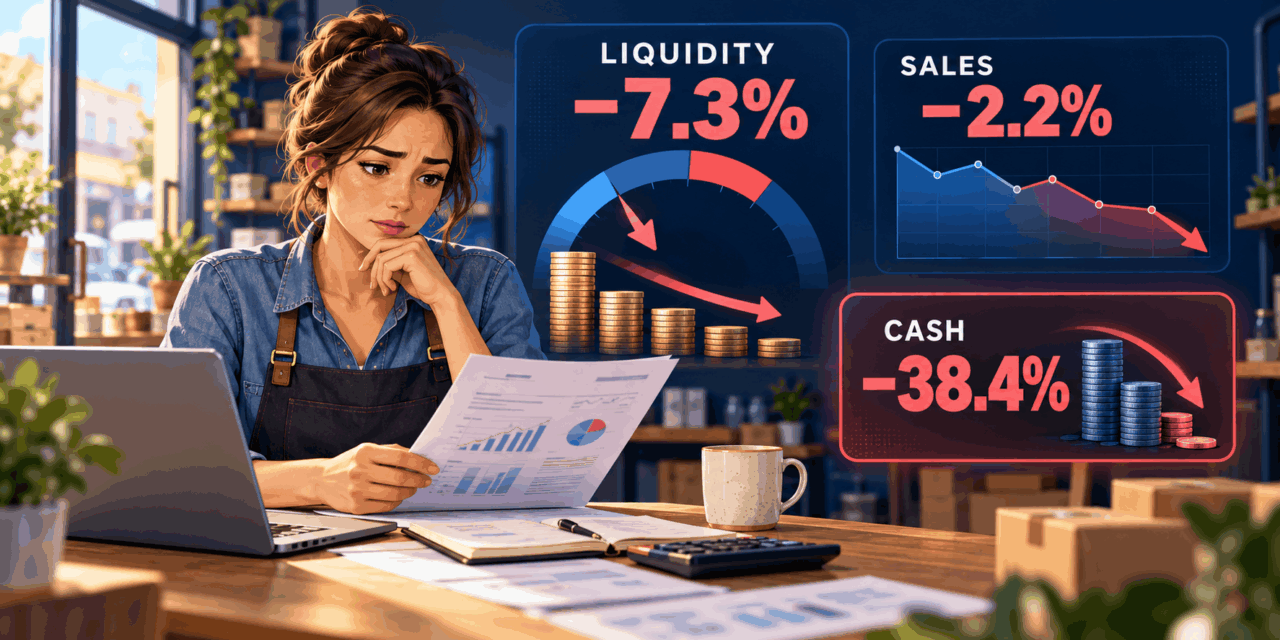
Shift’s first SME Economy Index, covering data to 30 September 2026, reads 49.4. The sharper signal sits underneath it: average monthly liquidity fell more than three times as fast as average monthly sales.
The headline numbers
Index, September 2026. Down 0.9 pts on the month, 2.7 pts on the year. Neutral is 50.
Average monthly sales per business. −2.2% year on year.
Average monthly liquidity — cash on hand. −7.3% year on year.
Average monthly cash held by Small businesses. −13.1% year on year.
Momentum by industry, September 2026
Bars are scaled for comparison across the 44–52 range; the vertical marker is the neutral 50 line. Blue sits at or above 50, coral below.
Where momentum and cash disagree
Reads strong, holds least cash
Rental, Hiring & Real Estate Services posted 50.5 — the second-highest industry reading — while its average liquidity fell 38.4% to $141k, the largest fall of any industry, and sales ran 22.1% below a year earlier.
Reads soft, selling more
Transport, Postal & Warehousing sat below neutral at 49.1, yet rose 2.3 pts on the month — the largest industry gain — with average sales 8.5% higher than a year earlier.
Why it matters on a file: the Index measures how many businesses are growing revenue, not how much cash they hold. Screening a business or asset finance deal on momentum alone can point you at the segment with the thinnest buffer in the sample.
The state picture
| State | Index | MoM | YoY |
|---|---|---|---|
| NSW | 50.6 | little changed | −1.8 |
| South Australia | 50.1 | little changed | −2.9 |
| Queensland | 50.0 | −0.7 | −1.4 |
| Victoria | 48.1 | −1.5 | −4.7 |
| Western Australia | 47.9 | −2.4 | −2.7 |
Victoria fell the most on the year, by 4.7 pts. On cash rather than momentum, the report names Queensland (down 18.8%) and Western Australia (down 13.3%) as the largest liquidity falls, with NSW the only state higher, up 6.1%.
The takeaway
Average monthly sales across the sample are close to where they were a year ago. The cash sitting behind those sales is not. For brokers writing business and asset finance, the question a trailing turnover figure cannot answer is how many weeks of buffer a new repayment schedule would consume — and that is the question worth putting in the file.
Source: Shift SME Economy Index and Report, first edition, data to 30 September 2026, published by Shift Financial Pty Ltd and drawn from aggregated information on more than 6,000 Shift customers. Figures are averages across that customer base, not an economy-wide survey.
SME Liquidity Fell 7.3% While Sales Fell 2.2%. The Second-Strongest Industry on Shift’s New Index Lost 38.4% of Its Cash
A new monthly read on Australian small business landed this week, and the interesting number is not the headline reading. It is the widening gap between what businesses are selling and what they have left in the account.
On this page
- A new monthly reading, and what it measures
- Cash is falling three times faster than sales
- Where momentum and cash disagree
- The state split is not where you would guess
- Capacity is expanding into a thinner buffer
- A new line item in the bank statements
- What to review on the file this week
- Where your obligations actually sit
Non-bank business lender Shift published the first edition of its SME Economy Index this week, covering data to 30 September 2026 and built from aggregated information on more than 6,000 of its own customers. For brokers writing business, equipment and asset finance, it adds something the existing diet of sentiment surveys does not: a monthly read on cash.
The Index came in at 49.4 in September — below the neutral 50 line, down 0.9 points on August’s 50.3 and 2.7 points below the 52.1 posted a year earlier. On its own that is a soft but unremarkable number, and the report is careful to say so: readings between 49 and 51 reflect average conditions.
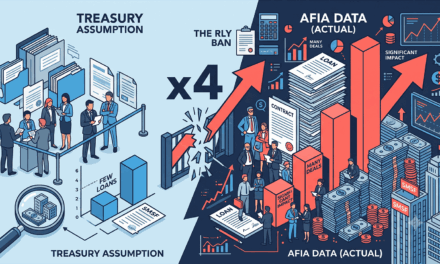
The number worth carrying into your next business finance conversation sits a few pages further in. Across the same customer base, average monthly sales per business were $323,000, down 2.2% on a year earlier. Average monthly liquidity — the cash those businesses actually hold — was $104,000, down 7.3%. Revenue has barely moved. The buffer behind it has fallen more than three times as fast.
That gap is a broker problem, because almost everything a business finance assessment runs on is a revenue figure.
A new monthly reading, and what it measures
Shift’s stated reason for publishing is a gap in the data. “There is no consistent, timely measure of how Australia’s SMEs are faring,” the report says. “Government agencies define an SME in different ways, and much of the current commentary draws on sentiment surveys.” Shift chief executive Jamie Osborn puts it more bluntly in the report: “SMEs are too important, and too poorly measured, to sit at the margins of the national conversation.”
The methodology matters if you intend to use it. The Index is a diffusion measure anchored at 50, tracking how many SMEs are growing their revenue rather than how much revenue there is. A reading below 50 means fewer businesses than usual are growing; it does not mean total revenue is falling. The report treats readings above 51 as strong and below 49 as soft, with the band between the two as ordinary. This first edition runs from June 2021 to September 2026 and is authored by Daniel Straton, CFA, of Shift’s strategy and data team, with data analyst Phillip Kristyono.
One limitation is worth stating plainly, and the report does not hide it: this is a lender’s own book. The figures are averages across more than 6,000 Shift customers, not an economy-wide survey, and businesses that have taken working capital finance are not a random sample of Australian SMEs. Read it as a timely signal from one sizeable slice of the market, not as a national statistic.
Cash is falling three times faster than sales
The longer series is where the divergence becomes hard to dismiss. Averaged by financial year, monthly sales rose every year from FY2022 to reach $331,000 in FY2026, and sit at $323,000 for FY2027 to date. Monthly liquidity peaked at $131,000 in FY2023 and has fallen in every year since, reaching $104,000 for the September quarter. Five years of flat-to-rising turnover; five years of thinning cash.
Split by business size, the squeeze is clearly bottom-weighted. Liquidity was lower than a year earlier in all three segments the report tracks, but Small businesses were down 13.1% to an average $29,000, against 8.9% to $110,000 for Established businesses and 7.8% to $441,000 for Corporate. On momentum the same pattern shows up: Corporate was the only segment above 50, at 50.2 and essentially unchanged on the month, while Small sat at 49.7 and Established at 49.0 — the weakest of the three.
Why $29,000 is the number to hold onto. It is an average monthly cash position, not a loan size. Set it against a short-term facility with weekly or daily repayments and the arithmetic becomes immediate: a repayment schedule that consumes a few thousand dollars a week is consuming a meaningful share of the buffer that average represents. A turnover figure from the last financial year will not tell you that. A current bank statement will.
Warren Hogan, managing director of EQ Economics, supplies the economist’s view in the report and attributes the slowdown to “a series of shocks” — the reversal of the 2025 interest rate cuts, higher energy costs after war broke out in the Middle East, and weaker established housing markets. He also notes that the Reserve Bank’s late-September cash rate rise, the fourth this year, is not yet in the Index. On his reading, “smaller businesses are bearing the brunt, while Corporate businesses have held up.”
Where momentum and cash disagree
Here is the finding that should change how brokers screen a business finance opportunity. Of the seven industries tracked, only two sat above 50 in September: Manufacturing at 50.8 and Rental, Hiring and Real Estate Services at 50.5.
Rental, Hiring and Real Estate Services also recorded the largest liquidity fall of any industry — 38.4%, to an average $141,000 — with average sales 22.1% below a year earlier. The industry with the second-strongest momentum reading in the sample holds the worst-deteriorating cash position in it.
Run the comparison the other way and it inverts again. Transport, Postal and Warehousing sat below neutral at 49.1, yet posted the largest monthly gain of any industry, up 2.3 points, with average sales 8.5% higher than a year earlier. Construction read 49.6 and was one of only two categories in the whole report where liquidity rose, up 3.3%, with sales 7.9% higher. Manufacturing sales were up 3.3%.
The genuine casualty is hospitality. Accommodation and Food Services recorded the lowest industry reading at 45.6, a 10-point fall in a single month — the largest move in the report — with average sales down 14.8% to $180,000 and cash reserves down 29.4% to $50,000. Hogan describes it as the most volatile industry of 2026. A hospitality file assessed on trailing twelve-month turnover is being assessed on a trading period the business is no longer in.
The practical rule: momentum and liquidity are answering different questions. The Index tells you whether businesses in a category are more likely than usual to be growing. It tells you nothing about whether they can absorb a repayment shock. Use both, or you will end up confidently pointing at the thinnest balance sheet in the sample.
The state split is not where you would guess
NSW recorded the highest state reading at 50.6, little changed on the month and down 1.8 points on the year, and was the only state where liquidity rose, up 6.1%. Hogan notes it has held up despite falling Sydney house prices and has shown tentative signs of rising momentum.
Western Australia posted the lowest reading at 47.9, after the largest monthly fall of any state at 2.4 points — though from a high base, following what the report describes as several years of above-average growth. WA nonetheless records the highest average monthly sales of any state, at $416,000, alongside a 13.3% fall in liquidity. Victoria sat at 48.1 and fell the most over the year, by 4.7 points.
Queensland is the quiet one. At 50.0 it reads precisely neutral and down just 1.4 points on the year, the smallest annual fall of the five states — and it carries the steepest liquidity fall of the five states, at 18.8%, on the lowest average monthly sales of any state at $287,000. A broker screening by state momentum alone would file Queensland under “fine”.
Capacity is expanding into a thinner buffer
The timing is what makes this more than an interesting chart. In the same week the Index landed, Bizcap doubled the maximum on its Fast Business Loan from $500,000 to $1 million, without property security, as reported by Broker Daily on 28 October. Chief credit officer Tony Truong framed the move around urgency: “Businesses don’t suddenly become less time-sensitive because they need $750,000 rather than $250,000.” Co-founder and co-chief executive Zalman Blachman cited “strong demand from businesses and our referral partners for larger, more flexible funding options.”
None of that is a criticism of the product or the lender. Larger unsecured limits are a genuine expansion of what brokers can solve, and demand for them is real. But the two data points sit together uncomfortably, and brokers are the people standing between them: the facilities available without property security are getting bigger at the same moment the average cash buffer underneath them is getting smaller. Whatever the lender’s credit appetite allows, the conversation about whether the client can carry the repayments belongs in your file.
A new line item in the bank statements
One side finding is worth a broker’s attention for a different reason. Among Shift customers who pay for software subscriptions, 19.2% paid OpenAI in September 2026, up from 2.2% in June 2023. Anthropic sat below 1% until January 2026 and has since reached 9.9%. The typical spend differs sharply: the median business paying Anthropic spent $153 in September, up from $34 in January, against roughly $32 a month for OpenAI since 2023.
Spending is concentrated — in September, the 18% of AI-paying businesses using both providers accounted for 52% of AI spending — and the report notes these figures cover direct payments to those two providers only, so they understate total AI spend. For brokers, the point is mundane and useful: AI subscriptions are now a recurring, growing and visible line in business transaction data. When you are reconstructing a borrower’s cost base from bank statements, it is a category that did not meaningfully exist two years ago and is no longer rounding error.
What to review on the file this week
- Convert the repayment into weeks of buffer, not a percentage of turnover. Take the client’s current average cash position from recent statements, not a prior-year figure, and work out how many weeks of that the proposed schedule consumes. Record the result.
- Ask for current-period trading, not just the last full year. A 10-point single-month move in one industry is the clearest argument in this report against relying on trailing twelve-month data for a cash-flow-sensitive deal.
- Screen on industry and cash, not industry alone. Hospitality and rental, hiring and real estate are the two categories where cash has deteriorated fastest, and only one of them looks weak on momentum.
- Re-run the numbers on deals in your pipeline from before late September. The report’s own economist flags that the September cash rate rise is not yet in the data. Anything priced or assessed before it may be carrying a stale assumption.
- Document the conversation, not just the outcome. If the client’s buffer is thin and they want the facility anyway, the file should show that you raised it, what you compared, and why you landed where you landed.
- Check what your business-lending clients would do if revenue slipped a month. On these figures, for a small business, the answer is increasingly “not much” — and that is a retention conversation as much as a credit one.
Where your obligations actually sit
A word of caution on the compliance overlay, because it is easy to over-apply. The best interests duty and the responsible lending framework attach to credit assistance on regulated consumer credit. Whether a particular business or equipment facility is regulated credit — and therefore whether the duty attaches to your assistance on it — turns on the purpose of the credit and how the deal is structured. That is a question for your licensee and compliance team on the specific file, not something to settle with a rule of thumb.
Where the duty does apply, ASIC’s guidance is not ambiguous about the breadth of it. RG 273.133 states that for a mortgage broker, “the best interests duty applies to any credit assistance you provide”, including “any standalone credit products on which you provide credit assistance”. And on what the file should contain, RG 273.165 says ASIC generally expects records to include “the options and ultimate recommendation you gave and the reasons why (including a detailed description of your decision-making process)”, alongside “relevant conversations with the consumer”.
Read against this week’s data, that record-keeping expectation is less a burden than a prompt. If you discussed a client’s cash position, if you weighed a smaller facility against a larger one, if you declined to proceed — that reasoning is exactly what a good file captures, and exactly what nobody can reconstruct twelve months later from a loan amount and a turnover figure.
Key takeaways
- Shift’s first SME Economy Index read 49.4 in September 2026, below the neutral 50 line, down 0.9 points on the month and 2.7 on the year.
- Average monthly sales across the sample fell 2.2% to $323,000. Average monthly liquidity fell 7.3% to $104,000 — more than three times as fast.
- Small businesses hold an average $29,000 of monthly cash, down 13.1% year on year. Liquidity has fallen in every financial year since peaking at $131,000 in FY2023.
- Rental, Hiring and Real Estate Services had the second-highest momentum reading at 50.5 and the largest liquidity fall of any industry at 38.4%. Momentum and cash are not the same signal.
- Accommodation and Food Services fell 10 points in a month to 45.6, with cash down 29.4% to $50,000.
- The figures are averages across more than 6,000 customers of one non-bank lender, not an economy-wide survey, and the late-September cash rate rise is not yet reflected in them.
Common questions
No. The Index is a diffusion measure of how many businesses are growing their revenue, not of the level of revenue. The report states explicitly that a reading below 50 does not mean total revenue is necessarily falling, and treats the 49 to 51 band as ordinary conditions.
Treat them as market context, not as evidence about your client. They are averages across more than 6,000 customers of a single non-bank lender, and businesses holding working capital finance are not a representative sample. Your client’s own current bank statements and trading figures remain the evidence that matters on the file.
Because turnover tells you what came through the business over a period, while liquidity tells you what is available when a repayment falls due. A facility with weekly or daily repayments is serviced from cash on hand, so the buffer is what absorbs a slow month. Turnover can hold steady while that buffer erodes — which is precisely the pattern in this report.
It depends on whether the facility is regulated credit, which turns on the purpose of the credit and the structure of the deal. That is a determination for your licensee or compliance adviser on the specific file. Where the duty does apply, RG 273.133 makes clear it extends to any credit assistance a mortgage broker provides, including standalone credit products.
On cash, Accommodation and Food Services and Rental, Hiring and Real Estate Services recorded the largest liquidity falls, and Queensland and Western Australia the largest falls by state. On momentum, Accommodation and Food Services, Western Australia and Victoria sat furthest below neutral. The two lists only partly overlap, which is the central point of the data.
Stay ahead of the policy and market shifts that hit your files
The Broker Times tracks lender policy, regulator activity and market data for Australian mortgage and finance brokers — daily, and without the fluff.
More at The Broker Times →Sources: Shift SME Economy Index and Report, first edition, data to 30 September 2026 (Shift Financial Pty Ltd), including the economist’s view by Warren Hogan, managing director, EQ Economics; Broker Daily, “Bizcap doubles unsecured business loan limit”, 28 October 2026; ASIC Regulatory Guide 273 Mortgage brokers: Best interests duty, June 2020, paragraphs 273.133 and 273.165.
Interactive · Broker tool
Business File Context Check
Pick your client’s industry and state to see where they sit in Shift’s September 2026 data, then convert a proposed repayment into weeks of cash buffer. Nothing is sent anywhere — this runs in your browser.
Where does the client sit?
Turn the repayment into weeks of buffer
From recent statements, not last year’s accounts.
Your read
Choose an industry and state above, and enter a cash position and repayment, to build the picture.
This is a context and arithmetic aid for your own file notes. It is not a serviceability assessment, a suitability assessment, credit advice or a product recommendation, and it does not take account of your client’s full financial position. Index, sales and liquidity figures are from the Shift SME Economy Index and Report, first edition, data to 30 September 2026, and are averages across more than 6,000 Shift customers rather than economy-wide statistics. Where the report’s commentary does not separately disclose a figure, that is stated.
Lender policy shifts, regulator activity and the market data behind your files — tracked daily.
More at The Broker Times →Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.