Too Busy to Read? We’ve Got You.
Get this blog post’s insights delivered in a quick audio format — all in under 10 minutes.
This audio version covers: 266 Fixed Rates Rose in a Week While Two Lenders Cut Variables. CBA’s Two-Year Now Sits Above the Average Variable Rate
The Broker Times · Rate Brief
Fixed Rates Went Up. Variable Rates Went Down. In the Same Week.
Ten lenders repriced 266 fixed rates in the seven days to 22 September 2026. Two lenders cut variable rates over the same stretch. The fix-or-float conversation your clients are about to start has changed shape.
The week on the rate sheet
Canstar’s count, as reported 18 and 22 September 2026.
How the majors moved
All four repriced fixed inside six days, ahead of the 29 September decision.
- Thursday 17 SeptemberNAB and ANZ lift fixed rates by up to 0.20 percentage points.
- Friday 18 SeptemberWestpac lifts by up to 0.45pp, taking its four-year to 7.09% and five-year to 7.14%.
- Tuesday 22 SeptemberCBA lifts by up to 0.48pp — its two-year moves to 6.82%, close to two standard cash rate rises in one repricing.
- Tuesday 29 SeptemberRBA Monetary Policy Board decision. All four majors forecast a rise to 4.60%.
Where the two-year sits now
Advertised owner-occupier principal-and-interest rates. Eligibility, LVR tiers and package conditions apply and pricing varies by file.
Two gaps worth more than the fix-or-float call
0.93pp on the two-year
CBA’s 6.82% against the market’s cheapest two-year fixed at 5.89%. On the advertised numbers that is close to four standard 0.25pp rate rises — before the RBA has moved at all.
0.85pp on the five-year
Westpac’s 7.14% against Southern Cross Credit Union’s 6.29%. Longer terms carry the widest spread and the longest commitment.
0.21pp above variable
CBA’s two-year fixed now sits above the average owner-occupier variable rate. Fixing there is a bet on hikes that have not happened yet.
The number brokers should check against the calendar
A fixed quote given before 17 September may now be stale. ASIC’s RG 273.121 says that where the credit assistance process is subject to delay, you should consider whether you need to start a new assessment or make further inquiries before making a recommendation. Nothing in this week’s repricing changes a recommendation already made — but it may change one you are about to make.
The broker takeaway
A fixed rate is not a forecast-free option. It is the lender’s own price on the forecast, collected up front. This week the majors raised that price by roughly two cash rate rises. The lenders holding the cheapest advertised fixed rates on Canstar’s 18 September list were not among those that moved.
That makes the lender question larger than the fix-or-float question. On the advertised two-year, the spread across the panel is now wider than the move the RBA is expected to make on 29 September.
Sources: RBA, Cash Rate Target statistics and Monetary Policy Decisions 2026 (cash rate 4.35%, unchanged since 6 May 2026). Canstar rate analysis as published 18 and 22 September 2026, and as reported by Australian Broker, 22 September 2026. ASIC Regulatory Guide 273, Mortgage brokers: Best interests duty, June 2020. Market pricing and bank forecasts as reported by ABC News, 22 September 2026. All rates are advertised rates at the time of writing and are subject to change.
Rates · Broker Analysis
266 Fixed Rates Rose in a Week While Two Lenders Cut Variables. CBA’s Two-Year Now Sits Above the Average Variable Rate
The majors repriced their fixed books before the RBA moved, and the cheapest lenders did not follow. That turns the question your clients will ask this week — should I fix? — into a question about which lender, not which rate type.
In the seven days to 22 September, ten lenders raised 266 fixed rates by an average of 0.33 percentage points, on Canstar’s count as reported by Australian Broker. Over the same week, two lenders cut three owner-occupier variable rates. Both things are true, and the gap between them is where your next twenty client conversations will land.
In this article
What actually moved, and when
The cash rate has not changed since 6 May. The RBA’s own cash rate target table shows three increases of 0.25 percentage points this year — effective 4 February, 18 March and 6 May — taking the target to 4.35%, where the Monetary Policy Board left it in June and again in August. The Board next meets on 28–29 September.
Lender pricing did not wait. Canstar’s tally has 16 lenders increasing fixed rates across September, with all four majors moving inside six days. NAB and ANZ went first on 17 September, lifting by up to 0.20 percentage points. Westpac followed on 18 September with increases of up to 0.45pp. CBA moved on 22 September with rises of up to 0.48pp.
| Fixed term | CBA, from 22 Sep | Westpac, from 18 Sep | Market’s lowest |
|---|---|---|---|
| 1 year | 6.78% | 6.74% | 5.79% — Police Credit Union |
| 2 years | 6.82% | 6.74% | 5.89% — Police Credit Union |
| 3 years | 6.89% | 6.94% | 5.84% — Police Bank |
| 4 years | 6.89% | 7.09% | 6.29% — Southern Cross Credit Union |
| 5 years | 6.94% | 7.14% | 6.29% — Southern Cross Credit Union |
These are advertised owner-occupier principal-and-interest rates on Canstar’s reading, published 18 and 22 September. The lowest-rate column was compiled on 18 September. Package conditions, LVR tiers and membership eligibility apply, and what a given file is actually offered will differ — which is itself part of the point below.
The single largest move was CBA’s two-year, up 0.48 percentage points in one repricing. That is close to two standard cash rate increases delivered in a single morning, before the Board has met.
The detail that makes this week different
Fixed rates rising ahead of an expected cash rate increase is not news. Brokers have watched that pattern for two decades. What makes this week worth a file note is the direction of travel on the other side of the rate sheet.
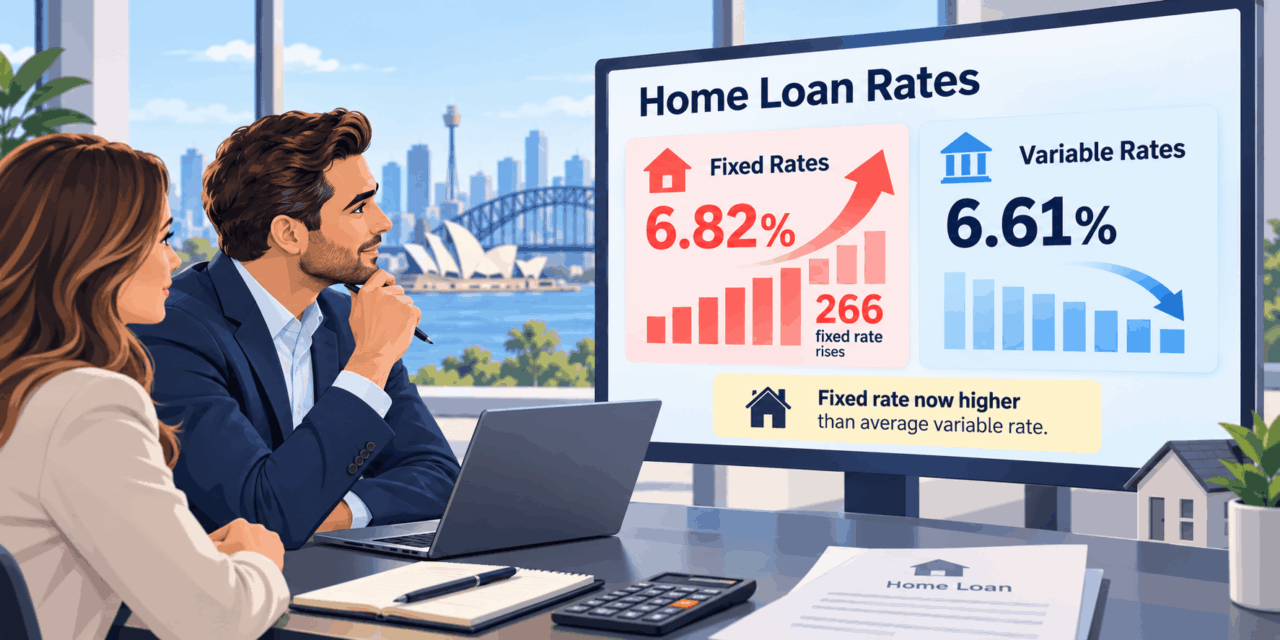
In the same seven days, two lenders cut three owner-occupier variable rates by 0.05 percentage points. The average owner-occupier variable rate sits at 6.61%, with the lowest advertised variable at 5.69% from Pacific Mortgage Group. So while the majors were adding up to half a percentage point to their fixed books, the variable market did not move with them — and in two cases moved the other way.
Run the subtraction. CBA’s new two-year fixed of 6.82% now sits 0.21 percentage points above the average owner-occupier variable rate. A client who fixes there today does not lock in protection at today’s cost. They pay more than the current market average from day one, in exchange for certainty about a rise that has not happened.
That is not an argument against fixing. It is an argument for being able to explain, in writing, exactly what the client is buying and what has to happen for it to pay off.
A fixed rate is a price on a forecast
A fixed rate is not a rate type. It is the lender’s own view of where funding costs are going, converted into a number and collected up front. When a lender lifts its two-year by 0.48pp a week before a board meeting, it is telling you what it expects — and charging for it in advance.
Market pricing has moved the same way. As reported by ABC News on 22 September, futures markets implied roughly a 90% probability of an increase at the September meeting, with a follow-up move in November running at close to even odds. All four majors forecast a 0.25pp rise to 4.60%. ANZ, CBA and Westpac have flagged a possible further move in November that would take the cash rate to 4.85%.
RBA Governor Michele Bullock, speaking at a Committee for Economic Development of Australia event in Sydney on 22 September, framed the Bank’s concern as containing the flow-through rather than the initial shock. As reported by ABC News, she said monetary policy “really just needs to continue to focus on making sure that we limit indirect effects and we try to keep inflation expectations anchored”, and that the Bank needs “to be very careful to ensure that policy is set in a way that minimises the second round and indirect effects which might perpetuate ongoing inflation”.
For the client on the phone, the arithmetic is simple enough to do together. If their variable sits near the 6.61% average and both expected increases are passed on in full, it lands around 7.11%. Against CBA’s 6.82% two-year, fixing wins — but only if those increases arrive and stay for most of the two years. If only one lands, or one is unwound inside a year, the comparison narrows to roughly line-ball. Fixing at a major today is a position on the persistence of the hikes, not on whether they happen.
Canstar’s cost arithmetic gives the other half of the conversation: each 0.25 percentage point increase adds roughly $91 a month to a $600,000 mortgage, or about $364 a month across four such moves.
The spread that matters more than fix-or-float
Here is the number that should reorder your week. On the advertised two-year, CBA’s 6.82% sits 0.93 percentage points above the cheapest two-year in the market at 5.89%. On the five-year, Westpac’s 7.14% sits 0.85pp above Southern Cross Credit Union’s 6.29%.
Nearly a full percentage point. Divided by a standard 0.25pp move, the two-year gap is worth close to four rate rises — more than the RBA is expected to deliver between now and the end of the year, and considerably more than the decision everyone is waiting on next Tuesday.
Put plainly: the difference between two lenders on the same product, on the same day, is currently larger than the difference the central bank is about to make.
Which means the lender question now carries more weight on the file than the rate-type question. A client who fixes with the cheapest available lender is in a materially different position from one who fixes with a major — and the gap between them has nothing to do with what the RBA does on 29 September.
The obvious caveat applies, and it matters. The cheapest advertised fixed rates in that table sit with credit unions and mutuals, which carry membership eligibility rules, narrower credit policy, different turnaround times and in some cases feature sets that will not suit the file. A rate a client cannot access, or a lender whose policy will decline them, is not an option. But “my client probably would not qualify” is a conclusion to reach after looking, not a reason not to look.
What RG 273 actually says
ASIC’s Regulatory Guide 273 on the best interests duty is worth rereading in a week like this, because it addresses this fact pattern directly.
At RG 273.51, ASIC says it generally expects the cost of a credit product — “such as interest rate, fees and charges and the size of repayments” — to be a factor brokers should prioritise. At RG 273.54, it goes further: a failure to consider cost and investigate the lowest cost options available to the consumer may suggest non-compliance with the duty, and any situation where a higher cost loan is recommended will need to be supported by evidence demonstrating why that recommendation is in the consumer’s best interests.
RG 273.56 supplies the balance. The product with the lowest interest rate is not necessarily the lowest cost option for every consumer — an offset account or redraw facility may save a particular client considerably more than a headline rate difference, and annual or establishment fees can reverse the comparison entirely. A 0.93pp gap does not automatically decide the recommendation. It does decide how much explaining the file needs to carry if the recommendation lands on the wider side of it.
The worked example that no longer fits by default
RG 273 contains a worked example almost tailored to this moment. In Example 8, a low-income borrower worried about rising rates is recommended a fixed rate loan “at a similar rate to the lowest cost variable rate loans available” to him. Rates then fall, and he would have been better off on a variable. ASIC’s commentary is that the broker complied with the duty, because the assessment is made at a point in time and, generally, changes occurring after the recommendation are not relevant to whether the duty was met.
Read the condition in that example carefully. The fixed rate was at a similar rate to the lowest cost variable options. That is what made it defensible on cost as well as on certainty. This week, a major-bank two-year at 6.82% is not at a similar rate to the lowest cost variable options — it is above the market average and more than a full point above the cheapest variable on offer. The conclusion in Example 8 does not travel automatically to a rate sheet that looks like this one. The reasoning still does; it just has more work to do.
General information, not compliance advice
This is a plain reading of published ASIC guidance, not advice about your obligations. RG 273 is ASIC’s guidance on the best interests duty, which RG 273.6 sources to sections 158LA and 158LE of the National Consumer Credit Protection Act 2009. How it applies to any particular file depends on facts this article cannot see. Check your process with your licensee or aggregator’s compliance team, and seek independent legal advice where you need a view you can rely on.
The quotes sitting in your pipeline
The operational problem this week is not the client who calls tomorrow. It is the client you quoted a fortnight ago.
Any fixed rate indication given before 17 September predates every major-bank move described above. If that file is still sitting at conditional approval, still waiting on a valuation, or still working through a contract, the number in the client’s head may no longer exist. They will not discover that gently.
RG 273.121 speaks to exactly this: where the credit assistance process is subject to delay, ASIC says you should consider whether you need to start a new assessment or make further inquiries into the consumer’s circumstances before making a recommendation or assisting them to take out a product. A market that repriced 266 fixed rates in a week is a reasonable prompt to ask that question of every file that has been open more than a fortnight.
Rate lock, where a lender offers it, is the other live conversation — and one worth having early rather than at formal approval, since availability, cost and lock periods differ by lender and by product. Check the specific terms on the specific file rather than working from what a lender offered last year.
What to review this week
- Pull every file with a fixed rate quoted before 17 September. Sort by lender. Anything with a major is almost certainly stale. Re-price it and tell the client before they see it somewhere else.
- Re-run your two-year comparison across the whole panel, not the usual five. The spread between the top and bottom of the advertised market has widened to roughly four rate rises. If your shortlist is habitual rather than current, it is now costing clients real money.
- Write the break-even into the file note, not just the recommendation. Today’s variable, today’s fixed, and what has to happen to the cash rate — and for how long — for the fixed option to come out ahead. It is a two-line calculation that turns a preference into reasoning.
- Where you recommend a higher-cost fixed rate, record why. RG 273.54 expects evidence supporting the recommendation. Offset access, redraw, turnaround, policy fit, serviceability or a feature the client specifically asked for are all legitimate — if they are written down at the time.
- Check rate lock terms per lender, per product, now. Availability, fee and lock period vary. Raise it before formal approval rather than after.
- Segment your back book by fixed expiry over the next twelve months. Anyone rolling off a fixed rate set during the cheaper part of the cycle is walking into a materially different market. That is a retention conversation you want to start, not receive.
- Prepare the answer to “should I just fix before Tuesday?” It is coming. The honest answer — that most of the expected move is already in the fixed price, and the bigger variable is which lender — is more useful than a yes or a no, and considerably easier to defend.
What to watch next
Three things over the next fortnight. First, the decision itself on 29 September and whether variable rates move in full, in part, or on a lag — the pass-through, not the headline, is what changes client repayments. Second, whether the lenders that have not yet repriced fixed follow the majors or hold their position; a lender sitting 0.90pp below CBA on a two-year is either about to move or about to win a lot of business. Third, the November meeting, where market pricing currently sits near even and where ANZ, CBA and Westpac have flagged a possible move to 4.85%.
The broader point outlasts all three. The majors have already priced in the hikes; parts of the market have not. For as long as that gap stays near a full percentage point, the most valuable thing a broker does on a fixed rate enquiry is not predicting the RBA. It is knowing, on the day, which lender is charging what — and being able to show the client the working.
Key takeaways
- Ten lenders raised 266 fixed rates by an average of 0.33pp in the week to 22 September, on Canstar’s count, while two lenders cut three owner-occupier variable rates.
- All four majors repriced fixed inside six days: NAB and ANZ on 17 September, Westpac on 18 September, CBA on 22 September with rises of up to 0.48pp.
- CBA’s two-year fixed at 6.82% sits above the 6.61% average owner-occupier variable rate, so fixing there costs more than the market average from day one in exchange for certainty.
- The advertised two-year gap between the majors and the cheapest lenders is around 0.93pp — wider than the rate move the RBA is expected to make. Access, eligibility and policy fit still decide whether that gap is reachable on a given file.
- RG 273.51 and .54 put cost among the factors brokers should prioritise and expect evidence where a higher-cost loan is recommended. RG 273.56 is the counterweight: lowest rate is not always lowest cost.
- Fixed quotes given before 17 September may be stale. RG 273.121 prompts you to consider a fresh assessment where the process has been delayed.
Common questions
Does a fixed rate above the variable rate mean fixing is a bad idea?
No. It means the lender has priced in expected increases, so the client pays for that certainty from day one. Whether it pays off depends on how many increases arrive and how long they persist. If the client’s variable is near the 6.61% average and two 0.25pp increases are passed on in full, it reaches about 7.11% — above CBA’s 6.82% two-year. The useful output is the break-even, written into the file, not a general view on fixing.
Do I have to recommend the cheapest fixed rate in the market?
RG 273.56 is explicit that the lowest interest rate is not necessarily the lowest cost option — offset and redraw access, and annual or establishment fees, can change the comparison. What RG 273.54 says is that failing to consider cost and investigate the lowest cost options available may suggest non-compliance, and that recommending a higher cost loan needs evidence supporting why it is in the consumer’s best interests. Access and eligibility are part of that picture. Confirm how this applies to your process with your licensee or compliance team.
A client fixed last month and rates have moved. Is that a problem for the file?
ASIC’s guidance treats the best interests assessment as a point-in-time judgement made on the information available at the time, including reasonably foreseeable changes to the consumer’s circumstances. The commentary to Example 8 in RG 273 states that changes occurring after a recommendation is made are generally not relevant to whether the duty has been complied with. What matters is the quality of the reasoning recorded when the recommendation was made.
What about files quoted a fortnight ago that have not settled?
Those are the ones to look at first. Every major-bank fixed rate in this article changed between 17 and 22 September. RG 273.121 says that where the credit assistance process is subject to delay, you should consider whether you need to start a new assessment or make further inquiries before making a recommendation or assisting the consumer to take out a product.
Will variable rates follow if the RBA moves on 29 September?
That is the thing to watch rather than assume. Lenders decide their own pass-through, and it can be full, partial or delayed. Two lenders cut owner-occupier variable rates in the same week the majors were raising fixed, which is a reminder that the two sides of the rate sheet do not have to move together.
Sources and method: Cash rate level, 2026 change dates and meeting schedule from the Reserve Bank of Australia, Cash Rate Target statistics and Monetary Policy Decisions 2026. Fixed and variable rate movements, individual lender rates and lowest-rate comparisons from Canstar analysis published 18 and 22 September 2026, and as reported by Australian Broker on 22 September 2026; the 266-rate and 0.33pp figures and the $600,000 repayment arithmetic are Canstar’s as reported by Australian Broker. Market-implied probabilities, major-bank forecasts and the remarks by RBA Governor Michele Bullock at a CEDA event in Sydney on 22 September 2026 are as reported by ABC News, 22 September 2026. Regulatory references are to ASIC Regulatory Guide 273, Mortgage brokers: Best interests duty (June 2020), paragraphs RG 273.51, .54, .56, .116 and .121 and Example 8. Percentage-point gaps between lenders are arithmetic on the advertised rates cited. All rates are advertised rates current at the time of writing, subject to eligibility, LVR and package conditions, and subject to change.
Breaking news for modern brokers
Rate moves, lender policy and compliance developments, read for what they change on your desk.
More at The Broker Times →Broker Tool
Fix or Float: The Break-Even Your File Note Needs
A fixed rate above today’s variable is a price on rate rises that have not happened. This works out how many of them have to stick before fixing comes out ahead — so you can put the reasoning in the file, not just the recommendation.
1. The two rates on the file
2. How many 0.25pp rises stick for the term
3. When they land, and how much is passed on
Fixed — whole term
–Variable — average over term
–Indicative monthly gap
–What to carry into the file note
Record the two rates, the number of rises the client’s decision assumes, and the break-even. A recommendation with the working attached is a different document from one without it — particularly where the rate recommended is not the lowest available. Confirm your own process with your licensee or compliance team.
Disclaimer: This article is for general information and professional development purposes only. It does not constitute legal, compliance, or financial advice. Brokers should consult their aggregator’s compliance team and, where required, seek independent legal advice regarding their obligations under the National Consumer Credit Protection Act 2009 and ASIC’s responsible lending guidelines.